Blog

  • How Long Can You Be Behind on Property Taxes in DeKalb County?

    How Long Can You Be Behind on Property Taxes in DeKalb County

    A breakdown of the DeKalb County delinquent property tax timeline — from the first missed installment to the courthouse steps, the twelve-month redemption window, and the point of no return. Written for owners of vacant land, inherited lots, and unimproved acreage.

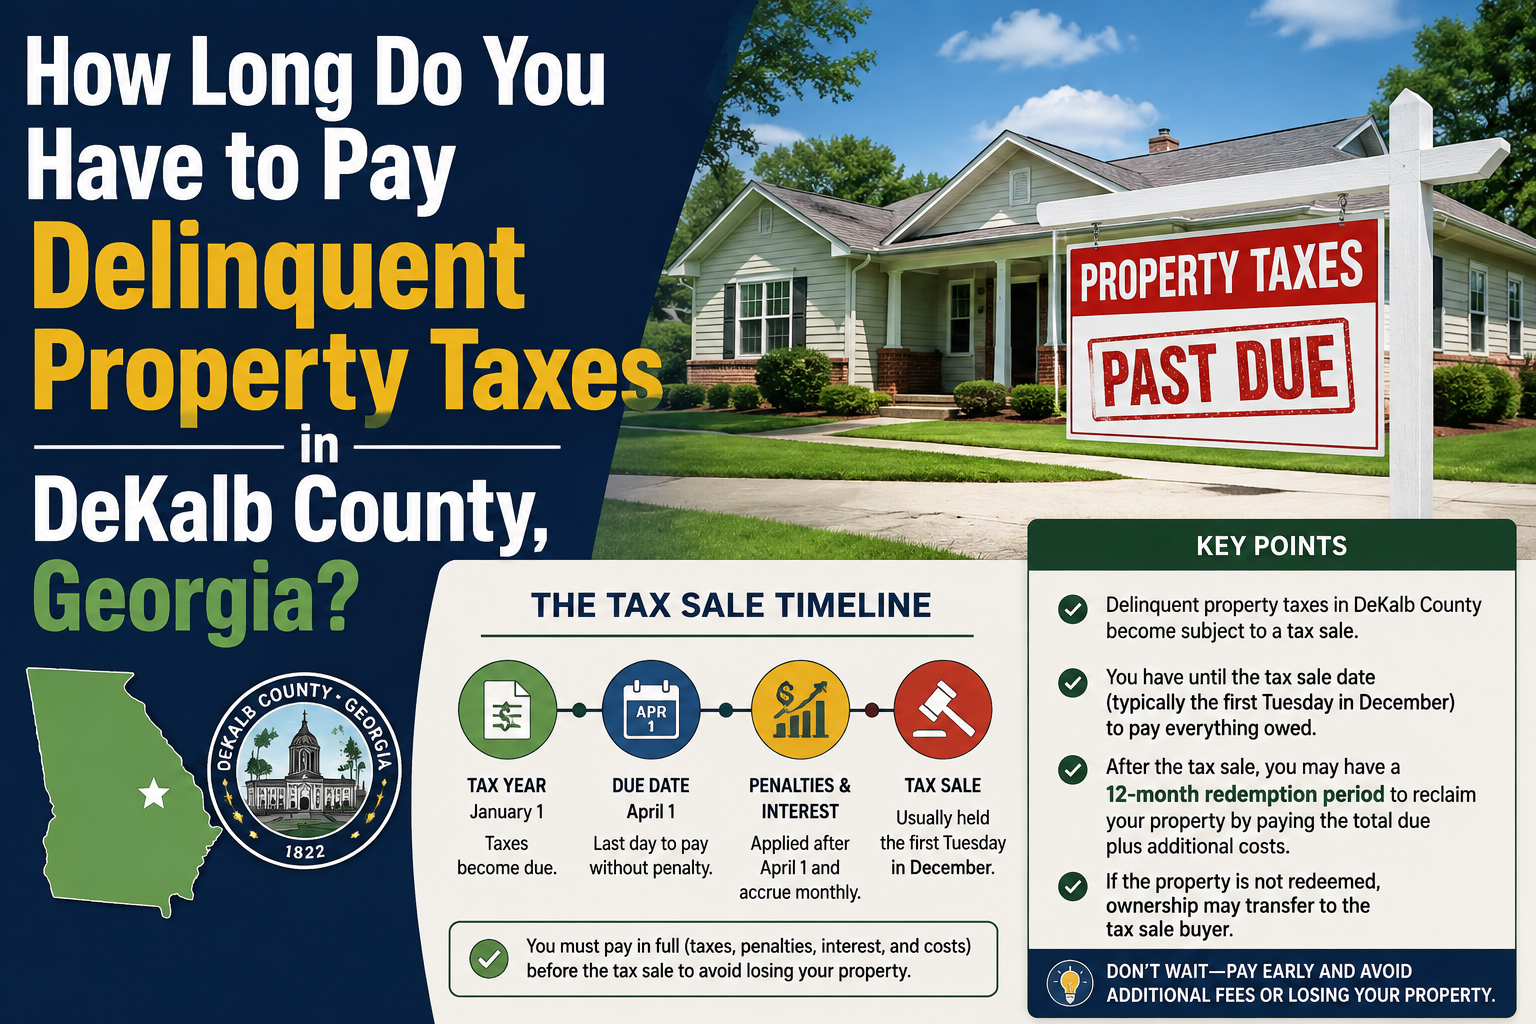
    The short answer There is no set number of years DeKalb County “allows” you to be behind. Georgia law does not give delinquent taxpayers a grace period measured in years. What governs your timeline is a sequence of statutory events, and once each one is triggered, the next can follow quickly. A bill becomes delinquent the day after its due date. By December 31 each year, the Tax Commissioner is legally required to issue a tax execution — a FiFa — against every delinquent account. From that point the parcel can be levied on, advertised for four consecutive weeks, and sold at a monthly public auction on the courthouse steps. In practice, most DeKalb parcels reach a tax sale somewhere between one and three years after the first missed payment. Some go much sooner. Some sit for five or six years. You cannot count on being one of the slow ones. And after the sale, you get exactly twelve months to redeem — that part is not discretionary at all.

    If you own land in DeKalb County and you have fallen behind on the taxes, the question you are almost certainly asking is some version of: how much time do I actually have? It is a fair question, and the answers you find online are usually either uselessly vague (“contact your county”) or flatly wrong (“Georgia gives you five years”).

    The honest answer is that the timeline is driven by a chain of legal steps rather than by a countdown clock. Some of those steps are discretionary — the Tax Commissioner’s office decides when to schedule a levy and which parcels go into which monthly sale. Others are mandatory and rigid. Understanding which is which is the difference between having options and losing the property.

    This article walks the DeKalb County tax sale timeline in order, with the statutes, the dollar consequences at each stage, and the local offices you can actually call. It is written with vacant land owners in mind, because unimproved property follows a different path than an owner-occupied house.

    Stage 1: The lien attaches on January 1 — before you owe anything

    Most people assume the county’s claim on their property begins when a bill goes unpaid. It does not. Under Georgia law, a tax lien attaches to real property at its valuation date, which is January 1 of each tax year. That is months before a bill is ever mailed.

    This matters because the lien is superior to all other liens — it outranks mortgages, judgments, everything — and because if you sell mid-year, that year’s tax obligation is already riding on the land and must be resolved at closing.

    Nothing dramatic happens on January 1 — no notice arrives, no filing appears. But legally the clock has started, and the lien is released only by paying the tax charged against it.

    Stage 2: DeKalb’s two-installment billing schedule

    DeKalb County splits the annual tax bill into two installments — a detail that trips up owners who have moved from a county that bills once a year.

    Bills go out in late summer. For the 2026 tax year, the first installment was due September 30 and the second installment was due November 16. These dates shift slightly year to year, so confirm them each season rather than assuming they are fixed.

    Two installments means two separate opportunities to become delinquent, on two separate clocks. Owners frequently pay the November bill they remember receiving, never realize a September balance is sitting unpaid, and find out a year later when penalties have compounded on it.

    You can check the exact balance on any DeKalb parcel — including prior years — through the county’s public property search at publicaccess.dekalbtaxga.gov. You do not need to own the property or create an account to look it up.

    Stage 3: Delinquency, and what it costs per month

    Taxes become delinquent the first day following the due date. There is no grace period, no ten-day window. Two separate charges begin stacking.

    Interest

    Under O.C.G.A. § 48-2-40, delinquent taxes accrue interest at an annual rate equal to the bank prime loan rate plus three percent, accruing monthly. The Georgia Department of Revenue sets and publishes this rate each January. For calendar year 2026 the rate is 9.75%, down from 10.50% in 2025. Any period shorter than a month counts as a full month. See the department’s annual interest rate notice for the current figure.

    Penalties

    Separately, under O.C.G.A. § 48-2-44, a 5% penalty is added once taxes are 120 days late. Another 5% is added every additional 120 days, up to a maximum cumulative penalty of 20% of the principal amount due.

    One carve-out exists, and it will not help land owners: the penalty does not apply to homestead property with a balance under $500. Vacant land does not qualify for a homestead exemption, so an unimproved lot is exposed to the full schedule from the first 120-day mark.

    What that actually adds up to

    Consider a DeKalb parcel with a $2,800 annual tax bill that goes entirely unpaid:

    Days past dueCumulative penaltyPenalty amountApprox. balance
    Day 10%$0$2,800
    Day 1215%$140~$3,032
    Day 24110%$280~$3,262
    Day 36115%$420~$3,493
    Day 48120% (capped)$560~$3,724

    Figures are illustrative and rounded, and assume interest at the 2026 rate on the original principal. Your actual payoff will differ — always request an exact figure from the Tax Commissioner’s office.

    Sixteen months of non-payment turns $2,800 into roughly $3,724 — a 33% increase — before any levy, advertising, recording, or commission costs are added once the parcel moves toward sale. Those costs are folded into your opening bid.

    DeKalb does accept partial payments, and you are welcome to make as many as you need. But penalties and interest keep accruing on whatever remains outstanding, and a partial payment does not stop the parcel from moving toward a tax sale. Details are on the county’s Delinquent Taxes page.

    Stage 4: December 31 — the FiFa is issued

    This is the first hard deadline in the process, and it is not discretionary.

    Under O.C.G.A. § 48-3-3, on December 31 of each year the Tax Commissioner must issue an execution against all delinquent taxpayers. The execution is called a FiFa, short for the Latin fieri facias, and it is also referred to as a tax execution or tax lien.

    A FiFa authorizes the Tax Commissioner or the Sheriff to take whatever action is necessary and allowed by law to collect the overdue taxes. It directs the levying officer to levy on the property, and that officer has a duty to enforce it by collection or by levy and sale.

    Two consequences matter. A FiFa is a public record, and although the Tax Commissioner’s office does not report to credit agencies, the lien may still surface on your credit reports. More importantly, it is the first formal step toward tax sale — once it exists, the county has the instrument it needs.

    A FiFa is canceled and marked satisfied by paying the outstanding taxes along with applicable fees, penalties, and interest.

    Key point for land owners A FiFa does not mean a sale is imminent — many DeKalb parcels carry executions for years. But the county no longer needs any further preparatory step before scheduling a levy. From here, timing is up to county discretion, not to any statutory waiting period protecting you.

    Stage 5: Levy, advertisement, and the four-week window

    When the county moves a parcel toward sale, the levying officer levies on it under the execution, and the parcel is advertised.

    Notice of the sale is published once a week for four weeks immediately preceding the sale in the county’s legal organ — the officially designated newspaper — which is currently The Champion Newspaper. This four-week advertising run is your last clear, public warning before the auction.

    This is where things get urgent, and where many land owners never find out. The county does not maintain a mailing list for tax sales. If the mailing address on file is outdated — common with inherited parcels — you may never receive anything.

    One other change at this stage catches people badly. Once a property is scheduled for tax sale, the office accepts only cash, a bank-issued cashier’s check, or a wire transfer. Personal checks, business checks, money orders, and debit and credit cards will not be accepted.

    You can see which parcels are currently scheduled on the county’s tax sale property listings. The county also publishes a delinquent property listing covering taxes due within the last seven years. Some properties owe more than that; for anything older, you have to contact the Delinquent Division directly.

    Stage 6: The tax sale itself

    DeKalb County holds tax sales monthly, generally April through December, and reserves the right to add or cancel sales, so the schedule is not perfectly predictable.

    Sales are held on the first Tuesday of a given month, on the DeKalb County Courthouse steps in Decatur, at 12:00 p.m. or sooner. Legal tax sale hours run from 9:00 a.m. to 4:00 p.m. Bidders must register in advance, either online or in person the morning of the sale.

    Bidding opens at the total of taxes and costs on the parcel — levy, recording, advertising, and commissions. The property goes to the highest bidder. Importantly, opening bids include all prior year taxes due, not just the most recent year. If there are no bidders at all, the County itself may enter a bid equal to the starting bid, which means a parcel nobody wants still changes hands.

    The winning bidder receives a tax deed. A tax deed is not full ownership and does not give the purchaser control of the property — but the clock has now flipped from a slow, discretionary process to a fixed twelve-month countdown.

    Stage 7: The twelve-month redemption period — the one deadline you cannot miss

    After a tax sale, the taxpayer — or anyone else with a right, title, interest in, or lien upon the property — may redeem it within twelve months by paying the redemption price. Twelve months from the sale date. No grace period, no extensions.

    During this window the purchaser holds what Georgia law calls defeasible title. They are not entitled to rents or profits, and cannot develop, clear, or sell the property free and clear. Your right to get it back is real and enforceable — provided you can produce the money.

    How the redemption price is calculated

    The redemption price is the amount paid for the tax deed at the sale, plus any taxes the purchaser subsequently paid, plus 20% of that total for the first year or fraction of a year, and 10% for each additional year or fraction until redemption.

    Two features deserve emphasis. The 20% premium applies to a fraction of a year exactly as to a full year, so redeeming on day 30 costs the same as day 360. And the premium is calculated on the full bid amount, not on your original tax debt.

    That second point is where the numbers get away from people. Say your delinquent balance was $3,700 and, after costs and bidding, the parcel sold for $9,000. Your redemption price is not $3,700 plus something — it is $9,000 plus 20%, plus any taxes the purchaser has paid since. Roughly $10,800. A $2,800 tax bill has become a five-figure problem.

    Why owners of vacant land run out of road here A homeowner can often refinance or borrow against the house to redeem. An owner of a wooded three-acre parcel in south DeKalb usually cannot — conventional lenders rarely lend against raw land, and almost never against raw land encumbered by a tax deed. That is why vacant land goes unredeemed at a far higher rate than improved property.

    Stage 8: Barment — the purchaser closes the door

    After twelve months from the sale date, the purchaser may begin to bar or foreclose your right of redemption. Practitioners call this barment; it is governed by O.C.G.A. §§ 48-4-45 and 48-4-46.

    Barment is not automatic, and the purchaser must follow the statute precisely. Notice must be served on:

    • The defendant in the execution — the owner at the time of the sale
    • The occupant of the property, if any
    • All persons having a recorded right, title, interest in, or lien upon the property

    Parties in the county are served personally. Those outside it are sent notice by registered or certified mail or statutory overnight delivery, if their address is ascertainable. The notice must also run in the sheriff’s advertising newspaper once a week for four consecutive weeks during the six months before the redemption deadline stated in the notice.

    If the owner at the time of sale has died, the purchaser must serve the heirs. Georgia courts are strict here: a purchaser who misses a required party has not validly barred redemption, and the defect can be raised years later. But notice is not required to anyone whose interest does not appear of record — a real hazard for informal heirs who never recorded anything.

    Once barment is properly completed, your right to redeem is terminated, foreclosed, divested, and forever barred. That is the statutory language, and it means what it says.

    Stage 9: Ripening by prescription — the four-year backstop

    There is a second, slower path to full title that requires no barment notice at all.

    Under O.C.G.A. § 48-4-48, a title under a tax deed properly executed on or after July 1, 1996, at a valid and legal sale, ripens by prescription after a period of four years from the recordation of that deed in the county land records. Notice of foreclosure of the right to redeem is not required for title to ripen this way.

    For an owner trying to understand the outer limit, this is the number that matters: four years from the recording of the tax deed. Most purchasers still prefer barment, since ripening requires proving four years of open possession in a quiet title action — awkward evidence for a vacant wooded lot. But a patient purchaser can rely on it.

    The full DeKalb County tax sale timeline at a glance

    StageTimingWhat happens
    Lien attachesJanuary 1Tax lien attaches at valuation; superior to all other liens
    Bills mailedLate summerTwo installments issued for the tax year
    1st installment due~Sept 30Delinquent the following day if unpaid
    2nd installment due~Nov 15-16Delinquent the following day if unpaid
    Interest beginsDay 1 latePrime + 3%, accruing monthly (9.75% for 2026)
    First penaltyDay 1205% of principal; repeats every 120 days to a 20% cap
    FiFa issuedDecember 31Mandatory tax execution against all delinquent accounts
    LevyCounty discretionLevying officer levies on the property under the FiFa
    Advertisement4 weeks pre-salePublished weekly in The Champion Newspaper
    Tax sale1st Tuesday, Apr-DecCourthouse steps, Decatur, 12:00 p.m. or sooner
    Redemption window12 monthsFixed. Redemption price = bid + 20% for year one
    Barment may beginAfter 12 monthsPurchaser serves notice on all recorded parties and heirs
    Ripening4 years from deed recordingTitle ripens by prescription without barment

    Why vacant land in DeKalb follows a different path than a house

    Nearly every article on delinquent property taxes is written for homeowners. If you own unimproved land, several assumptions baked into that advice do not hold.

    No mortgage servicer is watching

    On a financed house, the lender escrows taxes and pays them, stepping in to protect its collateral if something goes wrong. On land owned free and clear — which describes most inherited parcels — nobody is in that seat. There is no institutional safety net.

    No occupant to receive notice

    The barment statute requires service on the property’s occupant. A vacant lot has none — and more practically, nobody is there to notice a posted sign or call you. An owner-occupant in Decatur will almost certainly learn about a pending sale. An owner of forty acres near Lithonia who last visited in 2019 may not.

    Notices go to a stale address

    Heir property compounds this. When a parcel passes to several children with nothing probated or recorded, county records keep showing the deceased parent as owner and mail to that parent’s last address. Every notice in the chain goes to a house that may have been sold a decade ago — and because the heirs hold no recorded interest, the purchaser is not required to notify them at all.

    Small bills, split responsibility

    An unimproved lot might carry a tax bill of a few hundred dollars, and that smallness is exactly what makes it dangerous. It is easy to shrug off a $340 bill and assume the county will not bother. The statutory machinery does not scale with the size of the debt, and a parcel worth $80,000 can be lost over an amount that would not cover a car repair. The most common story behind a DeKalb land tax sale is not hardship — it is four siblings who each assumed one of the other three was handling it.

    If the sale already happened: excess funds

    When a tax sale brings in more than is owed in taxes, costs, and fees, the surplus is called excess funds, and the Tax Commissioner’s office holds it until an entitled party claims it.

    If your parcel sold for $9,000 against a $3,700 debt, that $5,300 difference does not belong to the county or the purchaser. It belongs to the parties with an interest in the property — typically the former owner, after lienholders are satisfied.

    A few rules worth knowing before you engage with anyone offering to recover this for you:

    • Claims must be filed by the party entitled to the funds or by a Georgia-licensed attorney
    • Powers of attorney are not accepted — this rule exists specifically to keep unlicensed recovery operations out of the process
    • Claims are evaluated case by case, and the office cannot estimate how long payment will take
    • If competing claims arise, the funds may be interpled into Superior Court, after which the Tax Commissioner cannot provide updates

    The county publishes both an excess funds list and a claim form. If someone contacts you offering to recover funds for a percentage, check the list yourself first — the information is free and public.

    What you can actually do, by stage

    If you are behind but no FiFa has issued

    1. Pull your balance from the county’s public search, checking every year — and confirm the mailing address on file is one you actually check
    2. Ask the Tax Commissioner’s office for a precise payoff figure including accrued interest
    3. Make a partial payment if that is what you can do — it reduces the principal penalties are calculated against

    If a FiFa exists but no sale is scheduled

    • This is your widest window and the cheapest point at which to resolve things
    • Pay in full if possible; the FiFa is marked satisfied once taxes, fees, penalties, and interest are paid
    • If you cannot pay and do not want the land, this is the best moment to sell — you still control the timeline and the price
    • If title is unclear from an unprobated estate, start resolving it now; it takes months and you cannot sell without it

    If the parcel is scheduled for sale

    • Get certified funds ready — cash, bank cashier’s check, or wire only
    • Confirm the sale date and the exact amount required to stop it
    • If you cannot cover it, a sale before the auction date will net you far more than the auction will

    If the sale already happened

    1. Calendar the redemption deadline immediately — twelve months from the sale date
    2. Get the redemption figure from the purchaser or the Tax Commissioner’s office
    3. Talk to a real estate attorney; the interest you are trying to protect is worth more than the consultation
    4. Check whether excess funds are being held for you

    DeKalb County and Georgia resources

    DeKalb County Tax Commissioner

    Legal notices and sale listings

    Georgia statutes and state resources

    Free and low-cost legal help

    • Atlanta Legal Aid Society — DeKalb office: 404-377-0701 | atlantalegalaid.org
    • Georgia Senior Legal Aid (statewide, age 60+): 404-389-9992
    • Self-help guides on property tax issues: GeorgiaLegalAid.org

    Atlanta Legal Aid serves Clayton, Cobb, DeKalb, Fulton, and Gwinnett counties and has income eligibility requirements, with some exceptions for seniors.

    Frequently asked questions

    How many years can you be behind on property taxes in DeKalb County before losing the property?

    There is no fixed number. A parcel can be sold as soon as a FiFa exists and the county schedules a levy and four weeks of advertising — realistically within a year or so of the first missed installment. Many parcels sit delinquent for several years before a sale. The only truly fixed period is the twelve-month redemption window after a sale has occurred.

    Will DeKalb County set up a payment plan?

    The Tax Commissioner’s office accepts partial payments and you may make as many as you need. That is not the same as a formal payment plan that pauses enforcement. Penalties and interest continue to accrue, and accounts with a balance after December 31 are subject to a lien regardless.

    Can I sell land that has delinquent taxes on it?

    Yes. Delinquent taxes do not prevent a sale; they are simply paid out of the proceeds at closing, exactly like a mortgage payoff. The obstacle is more often unclear title from an unprobated estate than the tax debt itself.

    What happens if nobody bids on my land at the tax sale?

    If there are no bidders, the County may enter a bid equal to the starting bid. The parcel still changes hands, and your twelve-month redemption clock still starts.

    Does a tax sale wipe out my mortgage?

    No. This is a common and costly misconception. A tax sale does not extinguish your personal obligation on a promissory note, and a mortgage holder is itself a party with a recorded interest that can redeem the property to protect its position.

    I just found out my deceased parent’s land was sold at a tax sale. Do I have any rights?

    Possibly. Heirs of a deceased owner are entitled to be served in a barment proceeding, and courts have invalidated barments that missed required parties. You may also be entitled to excess funds. This is a situation to take to a real estate attorney promptly rather than working out alone.

    Considering selling instead of paying it off? For a lot of DeKalb land owners, the math stops working long before the tax sale does. If the parcel is inherited, landlocked, or simply not part of your plans, continuing to carry it means paying penalties on an asset you do not want. Atlanta Land Buyers purchases vacant land throughout DeKalb County, including parcels with delinquent taxes and liens. We handle the payoff at closing. Get a no-obligation cash offer or learn how our process works. The single most important thing: the earlier in the timeline you act, the more the land is worth to you. Once it reaches the courthouse steps, you are no longer setting the price.

    Related reading

    DeKalb County, GA, USA
  • DeKalb County Delinquent Property Tax List: What It Means If Your Property Is Listed

    DeKalb County Delinquent Property Tax List What It Means If Your Property Is Listed

    Short answer: being on a DeKalb County delinquent tax list is not the same as losing your property, and it is not the same as being on the tax sale list. There are actually three separate documents, they mean three very different things, and knowing which one your parcel is on tells you almost exactly how much time you have left.

    Most people find this page the same way. Either a letter arrived from somebody offering to buy the house, or a neighbor mentioned seeing the address in the newspaper, or an adult child typed the parcel number into Google at midnight and found it sitting on a county spreadsheet with a dollar figure next to it.

    It is a genuinely alarming thing to see in print. It is also widely misread. Owners who see their parcel on the seven-year delinquent report panic as though an auction were scheduled next Tuesday, and owners whose parcels are on the actual tax sale listing sometimes assume they have years left. Both mistakes are expensive, and they run in opposite directions.

    This article explains which lists DeKalb County publishes, how to check whether your parcel is on any of them, how to read the columns line by line, and what each stage actually does to your title, your options, and your mailbox.

    Quick answer: DeKalb County publishes a delinquent property tax report covering parcels with taxes due within the last seven years, and a separate tax sale listing of parcels actually levied and scheduled for auction. Appearing on the first means a balance exists and a lien is likely recorded. Appearing on the second means your parcel has been levied, advertised in The Champion Newspaper, and will be sold on the courthouse steps on the first Tuesday of the month unless it is paid in certified funds first.

    There Is No Single “DeKalb Delinquent Tax List”

    This is the source of most of the confusion. People search for the DeKalb delinquent tax list as though it were one document. The Tax Commissioner’s Office maintains several, and they sit at different points on the timeline.

    1. The delinquent property tax report. The Tax Commissioner publishes a report of all properties with taxes due within the last seven years. It is broad. A parcel that missed a single installment last November can appear on it alongside a parcel that has not been paid since 2019. The county notes that some properties may have additional taxes due beyond what the report shows, and that anything older than seven years requires contacting the Delinquent Division directly. This is the list most homeowners stumble onto, and it is the least urgent of the three.

    2. The tax sale listing. This is the real one. It shows parcels that have been levied under a recorded execution and scheduled for a specific auction date. It carries the sale date, the parcel ID, the owner of record, the levy date, the tax years involved, and the total due. If your parcel is here, a clock is running in weeks, not years.

    3. The legal advertisement. Georgia requires notice of a tax sale to be published once a week for four weeks immediately preceding the sale in the county’s legal organ, which in DeKalb is The Champion Newspaper. This is the version your neighbors see, and it is also the version scraped by mailing-list companies, which is why the letters and calls tend to start about a month before the sale.

    There is a fourth list, published after the fact: the excess funds list, naming parcels that sold for more than the taxes and costs owed, with money still sitting unclaimed. More on that below.

    Is My Property on the DeKalb Tax Sale List? How to Check

    You can answer this in about five minutes without calling anyone.

    1. Get your parcel ID. It is on your tax bill, and it can be looked up by address through the county’s property information search. DeKalb parcel IDs look like 15 126 06 011 — a district, land lot, block, and parcel sequence. Searching by owner name is unreliable when a deed is still in a deceased relative’s name or held by an LLC. Search by address or parcel.
    2. Check the tax sale listing. The Tax Commissioner publishes the current tax sale property listing online. Find your parcel ID in the left column. If it is there, note the sale date.
    3. Check the delinquent report. The seven-year delinquent property listing tells you whether any balance exists at all, including years you may have forgotten about.
    4. Pull the account balance. Search and pay through the county’s property tax portal. The balance shown here is the live figure, which the published lists are not.
    5. Call to confirm. The Tax Commissioner’s Office is at 404-298-4000. Ask two specific questions: whether an execution has been recorded against the parcel, and whether the parcel is currently scheduled for a sale date. Those are different answers.

    One caution. If nothing shows up under your name, that does not mean nothing is wrong. Owners of inherited property routinely search their own name when the deed still carries a parent’s. Search the parcel, not the person.

    How to Read the Tax Sale Listing, Column by Column

    The listing is a raw database export, and the column headings are not written for homeowners. Here is what they actually mean.

    Tax Sale Date. The scheduled auction date. In DeKalb this is the first Tuesday of a month. Sales are generally held monthly from April through December, and the county reserves the right to add or cancel sales.

    Parcel ID / Map Ref. Your parcel’s identifier in the county system. Match this against your bill exactly; addresses on vacant land are frequently wrong or missing.

    Tax Sale ID. The county’s internal reference for this specific levy, typically formatted with the tax year, an R number, and the sale month. Quote this number when you call — it gets you to the right file immediately.

    Owner / Tenant / Defendant. The “defendant in fi.fa.” is the party the execution was issued against, which is the owner of record when the execution issued. If your deceased mother’s name appears here, that is a signal that title was never moved and the county’s notices have been going to her, not to you.

    Levy Type. Which taxing authority levied. A parcel inside a city may carry both county and municipal obligations. This matters enormously in Decatur, which bills separately on a different schedule and a different assessment ratio — see our breakdown of City of Decatur property taxes versus DeKalb County.

    Lien Book / Page. Where the execution is recorded in the county records. This is what a title examiner finds, and it is why a listed parcel cannot be cleanly sold or refinanced until the balance is satisfied.

    Levy Date. When the levying officer formally levied on the property. This is the step that converts a recorded lien into a scheduled sale.

    Min Year / Max Year. The earliest and latest tax years included in this levy. A parcel showing 2019 through 2025 has been delinquent for six cycles. A parcel showing 2025 to 2025 missed one.

    Total Tax Due. The figure the listing was generated with. This is not your payoff. Opening bids at a DeKalb tax sale include all prior year taxes due, and interest, penalties, title research, advertising, levy, recording, and sheriff’s costs continue to accrue. Always get a written payoff figure rather than working off the published number.

    What Being on the List Actually Means

    It means an execution has probably been recorded. In Georgia, a tax lien attaches to property at its valuation date of January 1 (O.C.G.A. § 48-2-56), and on December 31 of each year the Tax Commissioner is required to issue an execution — a Fi.Fa., short for fieri facias — against all delinquent taxpayers (O.C.G.A. § 48-3-3). DeKalb states plainly that accounts with an outstanding balance after December 31 are subject to a lien. That execution is a recorded encumbrance, and a tax lien against real property is superior to other liens.

    It means the balance is growing on its own. Interest accrues on the unpaid balance, a penalty attaches at intervals after the due date, and once collection activity begins, administrative and advertising costs are added. Our guide to what happens if you don’t pay property taxes walks through how quickly that compounds.

    It means your title is clouded. You can still own and occupy the property. You cannot cleanly sell or refinance it without satisfying the balance, though in a normal closing the payoff is handled out of proceeds rather than out of pocket. See can I sell property with a lien on it in Georgia.

    It does not mean you have lost the property. Nothing transfers until an auction happens and a tax deed is issued. Until the gavel falls, you hold title.

    It does not guarantee the sale will happen on the printed date. Parcels come off the list when paid, and the county can add or cancel sales. Do not plan around a cancellation.

    It does not mean the county is trying to take your house. The office’s own materials encourage payment and accept partial payments in any amount. Staff have far more room to work with an owner who calls in March than one who appears at the counter on the Monday before a Tuesday sale.

    The Detail That Catches People at the Last Minute

    Once a property has been scheduled for tax sale, DeKalb accepts only cash, a bank-issued cashier’s check, or a bank wire transfer, payable to the DeKalb County Tax Commissioner. Personal checks, business checks, third-party checks, money orders, and debit or credit cards are refused at that stage.

    Every year, people arrive with a card and a plan and leave without a property. If you intend to pay at the deadline, you need certified funds physically in hand, and you need the bank open. A Tuesday sale means Monday is your last banking day.

    Why Your Mailbox Suddenly Filled Up

    The lists are public records, and they are harvested the moment they publish. If your parcel appeared on the tax sale listing or in The Champion, expect letters, postcards, texts, and calls — sometimes dozens.

    Some of those senders are legitimate local buyers. Some are lead brokers who will never buy anything and are selling your information onward. A few are predatory. The distinctions are worth knowing:

    • Legitimate buyers never ask you for money. Not an upfront fee, not a “processing” charge, not a deposit to hold an offer.
    • Be extremely careful with anything asking you to sign a deed in exchange for a promise. Deeding your property in exchange for someone assuming the taxes, with a verbal understanding you can stay or buy it back, is how families lose equity permanently.
    • Watch for blank spaces in documents. Never sign an instrument with unfilled terms.
    • A real offer is written and itemized, showing back taxes, liens, and payoffs line by line. A number shouted over the phone is not an offer.
    • You are allowed to have an attorney read it. Anyone who resists that is telling you something.

    If somebody is pressuring you toward a decision this week on a sale that is two months out, that urgency is theirs, not yours.

    What to Do, Depending on Where You Are on the Timeline

    You are on the seven-year delinquent report, but no sale is scheduled

    This is the good position, and it is where the cheapest options live.

    • Start partial payments now. Every dollar reduces the base that penalties and interest compound against.
    • Verify your exemptions. Missing homestead, senior, or disability exemptions inflate every future bill. Check the DeKalb exemptions page, and if you are 62 or older, the county’s seniors resources.
    • Appeal the value if it is wrong. Assessment notices go out in late spring with a 45-day appeal window, handled by the DeKalb County Board of Assessors. An exemption cannot fix an inflated valuation.
    • Fix the deed if an owner has died. You cannot claim homestead on a parcel titled to a deceased parent, and the notices are going to them. Start with probate real estate in Georgia and how to sell inherited land.
    • Go in person. The Central Office at 4380 Memorial Drive handles property tax in person Monday through Friday.

    For the full stage-by-stage picture, see how long you have to pay delinquent property taxes in DeKalb County.

    Your parcel is on the tax sale listing

    The window is now measured in weeks.

    • Get a written payoff good through the sale date, not the number printed on the list.
    • Arrange certified funds early, not the day before.
    • If the payoff is out of reach, decide fast. A sale that clears for little more than the taxes owed destroys equity that a normal sale would have preserved. Selling before the auction, even at a discount, almost always leaves the family with more than the courthouse steps will.
    • Do not assume a second lien or mortgage protects you. Property taxes run on a separate track from any mortgage. Our guides on the 120-day foreclosure rule and whether you can sell a house in foreclosure cover how the two timelines interact.

    The sale already happened

    You still have rights, and they are time-limited.

    Georgia gives the taxpayer, and anyone with a right, title, interest in, or lien on the property, twelve months from the sale to redeem. The redemption price is the amount paid for the tax deed plus any taxes the purchaser has since paid, plus 20% of that amount for the first year or fraction of a year, and 10% for each additional year until redemption (O.C.G.A. § 48-4-42). The purchaser is not entitled to rents or profits during that period.

    After twelve months, the purchaser may begin to bar the right of redemption by proper notice served on all parties with recorded interests (O.C.G.A. § 48-4-45). Our article on tax foreclosure in Georgia and what happens to unpaid property taxes after foreclosure explain what follows.

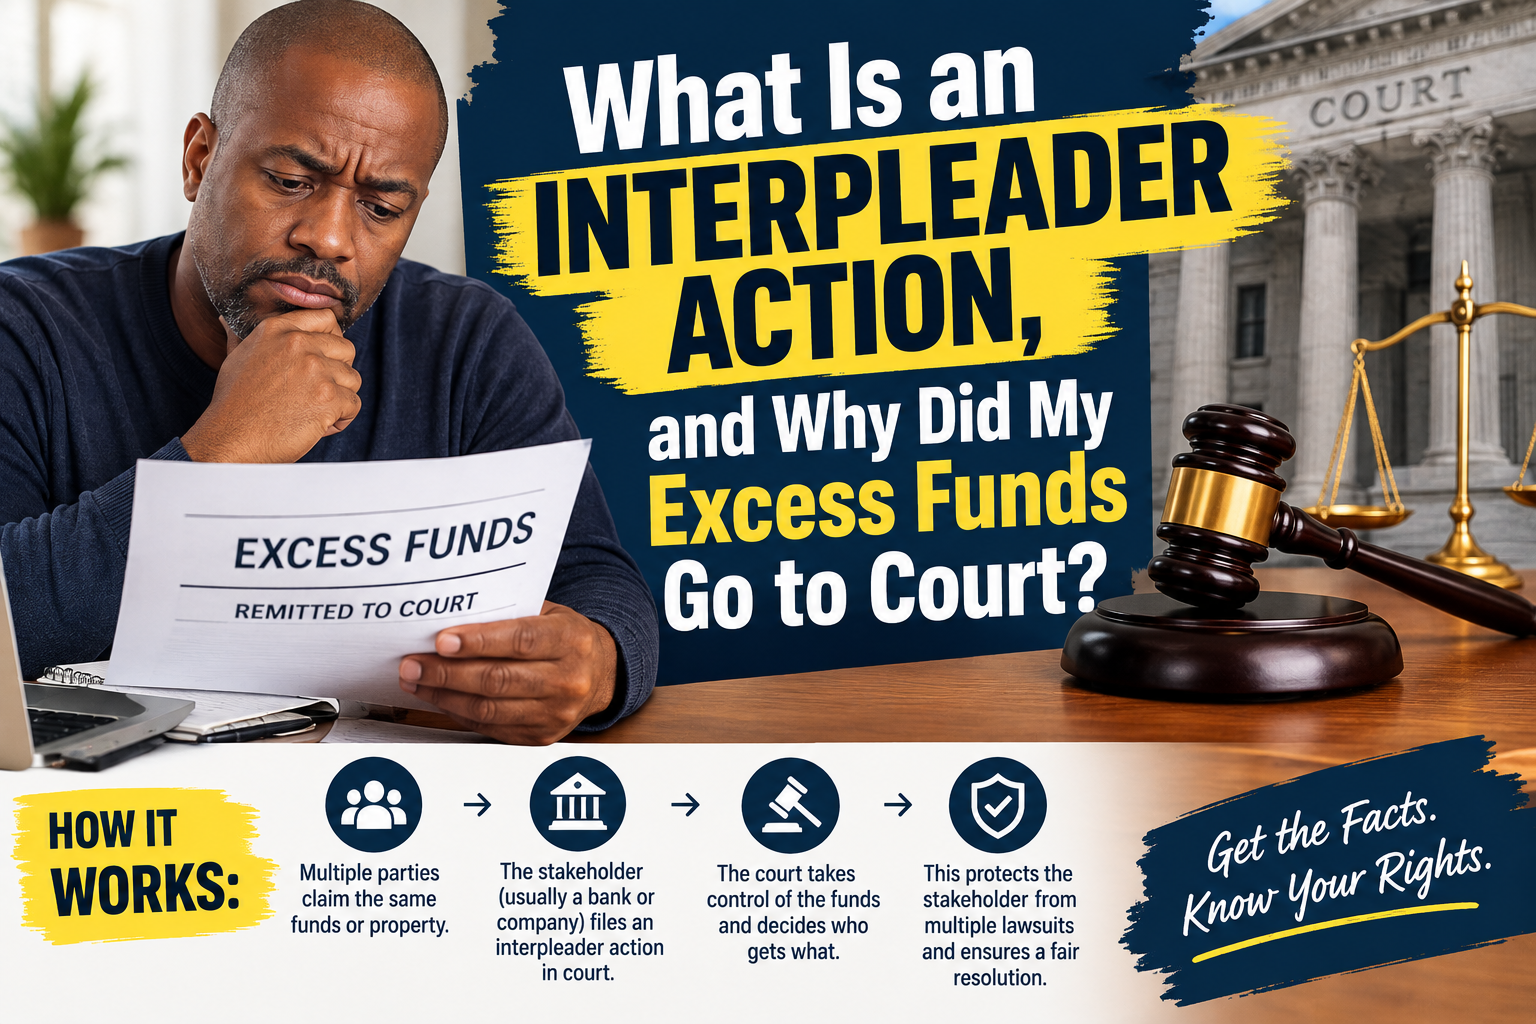
    And check the excess funds list. When a sale produces more than the taxes, costs, and fees owed, the surplus belongs to the former owner and other entitled parties, not to the county or the buyer. DeKalb holds it until claimed, claims go to Delinquent Collections Claims, and they must be filed by the entitled party or their Georgia-licensed attorney — powers of attorney are not accepted. If competing claims arise, the office may interplead the funds into Superior Court, which is a slower and more expensive path; see what an interpleader action is and our overview of excess funds.

    Five Things DeKalb Owners Get Wrong About the List

    1. Treating the published figure as the payoff. It is a snapshot. Costs accrue after it publishes.
    2. Assuming disappearing from the list clears the lien. Payment is what gets an execution marked satisfied. Confirm that it has been.
    3. Assuming the county has their current address. Notices go to the address of record. If you moved, inherited, or never updated it after a refinance, the letters went somewhere else.
    4. Forgetting the second bill. Parcels inside Decatur, Atlanta, and other DeKalb municipalities can be current with one authority and delinquent with another. See our Fulton versus DeKalb property tax comparison for how these structures differ.
    5. Ignoring vacant land. No mortgage means no escrow, and no escrow means nobody is quietly paying the taxes. Unused lots in Lithonia, Stonecrest, and unincorporated south DeKalb are heavily represented on these lists precisely because nobody drives past them.

    Q&A: DeKalb County Delinquent Tax List

    Is my property on the DeKalb tax sale list? Search your parcel ID on the Tax Commissioner’s tax sale property listing. If it appears there with a sale date, it has been levied and scheduled. If it appears only on the seven-year delinquent report, a balance exists but no auction is set. Call 404-298-4000 to confirm both points against your account.

    What is the difference between the delinquent tax list and the tax sale list? The delinquent list covers parcels with taxes due within the last seven years — a wide net that includes recent misses. The tax sale list covers parcels actually levied and scheduled for a specific auction date. One is a balance. The other is a deadline.

    Where is the DeKalb County tax sale held, and when? On the steps of the DeKalb County Courthouse in Decatur, on the first Tuesday of the month. Sales are generally held monthly from April through December, and the county can add or cancel them. The county’s tax sale page lists a scheduled start of noon or sooner with legal sale hours from 9 a.m. to 4 p.m., and individual sale notices have posted earlier start times with check-in beforehand — read the specific notice for your sale date.

    How will I know if my property is advertised? Notice is published once a week for four weeks immediately preceding the sale in the county legal organ, currently The Champion Newspaper. The county does not maintain a mailing list for tax sales, so the listing and the newspaper are the two public sources.

    Can I pay with a credit card to stop the sale? No. Once scheduled, only cash, a bank-issued cashier’s check, or a bank wire transfer is accepted, payable to the DeKalb County Tax Commissioner.

    Does being on the list hurt my credit? The Tax Commissioner’s Office does not report to credit agencies, but a recorded tax lien can still surface on credit reports and affect your rating, and it clouds title regardless.

    Can I sell a property that is on the DeKalb delinquent tax list? Usually yes, right up until the sale occurs. You remain the owner, and the back taxes are typically paid out of the proceeds at closing rather than in advance. Timing is the constraint: the closer to the auction date, the fewer buyers can actually perform. Our tax-delinquent property page explains how that works in practice.

    The owner on the list is deceased. What do we do? The estate generally needs legal authority before anyone can sell or, in many cases, claim excess funds. That runs through probate. Start with probate real estate in Georgia and our inherited land guide, and expect it to take longer than the tax calendar allows if you wait.

    I live out of state and just found out. Is it too late? Not necessarily, and this is more common than people think — out-of-state owners are the ones most likely to miss mailed notices. Most of a sale can be handled remotely through a Georgia closing attorney. See how we work with out-of-state owners.

    How many years can a property stay delinquent in DeKalb? There is no fixed countdown from lien to auction, which is exactly why the lists include parcels stretching back years alongside recent ones. See how many years you can be behind on property taxes in Georgia.

    Local DeKalb County Resources

    DeKalb County Tax Commissioner — 404-298-4000. dekalbtaxga.gov. Note the office moved to this domain; older dekalbtax.org bookmarks redirect.

    DeKalb County Board of Assessors — values are set here, not by the Tax Commissioner. Appeals and valuation questions: dekalbcountyga.gov/property-appraisal.

    The Champion Newspaper — DeKalb’s legal organ, where tax sales are advertised: thechampionnewspaper.com.

    Deeds, liens, and plats — searchable statewide through the Georgia Superior Court Clerks’ Cooperative Authority at search.gsccca.org.

    DeKalb County Probate Court — 556 North McDonough Street, Room 1100, Decatur, GA 30030. General number 404-371-2601. Where letters testamentary and letters of administration are issued.

    Atlanta Legal Aid Society, DeKalb office — free civil legal help for income-qualifying residents, including housing and heirs’ property matters. 246 Sycamore Street, Suite 120, Decatur, GA 30030. 404-377-0701. atlantalegalaid.org.

    Georgia Senior Legal Aid — advice and referrals for Georgians over 60, including property tax and housing problems. 404-389-9992.

    The Bottom Line

    A DeKalb County delinquent tax list is a status report, not a verdict. The seven-year report says a balance exists. The tax sale listing says a date has been set. The advertisement in The Champion says that date is inside of a month. Each one narrows what you can do and raises what it costs, and the gap between the first and the last is where every good option lives.

    So find out which list you are actually on before you do anything else. Pull the parcel, get a written payoff, and call 404-298-4000. If the number is payable, pay it and get the execution marked satisfied. If it is not, make the decision while a sale is still something you control rather than something you attend.

    If the balance is beyond reach — a house with years of back taxes, an inherited parcel nobody agrees on, or a vacant lot in DeKalb that has never earned a dollar — we buy property across the county as-is, with no fees or commissions, and most closings run 7 to 14 days. Call or text Gerald at (404) 913-7086, request a no-obligation cash offer, or contact us with your parcel number. We will tell you where you stand either way — including when the answer is to go pay the county and keep it.

    DeKalb County, GA, USA

  • How Can I Stop My Homeowners Association From Foreclosing on My Atlanta, Georgia Home?

    How Can I Stop My Homeowners Association From Foreclosing on My Atlanta, Georgia Home

    An HOA foreclosure letter does something a tax notice does not. It makes people angry before it makes them afraid, and anger is a bad strategy. Homeowners spend months arguing about a fence stain while attorney’s fees compound on a balance that started at a few hundred dollars, and by the time they take the legal side seriously the lien is four times the original debt.

    The good news is that Georgia gives HOA homeowners far more procedural protection than most people realize — and in 2026 the state added considerably more. This guide covers what actually stops an HOA foreclosure in Atlanta, what your association is legally required to do first, what changed under SB 406, and how HOA debt interacts with the delinquent property tax clock running in the background. It also takes an honest look at what HOAs do well and badly in this particular housing market, because the decision to fight, pay, or sell depends on understanding what you are actually buying with those dues.

    Short answer: In Georgia an HOA cannot foreclose the way a mortgage lender can. It must sue you in court, win a judgment, and obtain a court order — there is no power-of-sale shortcut. Before it can even file, the association has to send you a specific notice by certified mail and wait 30 days, and under current law the unpaid amount must be at least $2,000. Most Atlanta HOA foreclosures are stopped by a payment arrangement, a payoff at a closing, or a procedural defect in the association’s own paperwork.

    First: Georgia HOAs Cannot Foreclose Like a Mortgage Lender

    This is the single most important thing to understand, and it is the opposite of what most homeowners assume.

    Georgia is a nonjudicial foreclosure state for mortgages. A lender with a power-of-sale clause can advertise your house and sell it on the courthouse steps without ever seeing a judge. That process is fast, and it is why Georgia foreclosures have a reputation for moving quickly.

    HOA assessment liens do not work that way. Under both the Georgia Property Owners’ Association Act (O.C.G.A. § 44-3-220 through § 44-3-235) and the Georgia Condominium Act (§ 44-3-70 and following), an association must foreclose its lien judicially — by an action, a judgment, and a court order for foreclosure. Your association has to file a lawsuit, serve you, give you the chance to answer, and convince a judge. That takes months, costs the association real money, and creates several points where a homeowner can intervene.

    Two more limits matter enormously:

    • The $2,000 floor. Under current law, no foreclosure action on an assessment lien is permitted unless the lien is at least $2,000. An association threatening foreclosure over a $600 balance is describing something it cannot legally do yet.
    • Superior liens survive. An HOA judicial foreclosure is subject to superior liens and encumbrances, and a court order for judicial foreclosure does not affect the rights of a first mortgage holder. In practice this means an HOA foreclosure sale in Atlanta does not wipe out your mortgage — which sharply limits what a buyer will pay and, frankly, limits how often associations bother.

    Are you even in a POAA association?

    The Property Owners’ Association Act does not apply automatically. An association is covered only if it expressly submitted to the Act, usually through language in its recorded declaration; associations that never opted in are governed by their covenants alone. The practical difference is large. A POAA association gets an automatic statutory lien the moment an assessment comes due, without recording anything, while a covenant-only association usually has to sue for a money judgment first. Pull your declaration through the Georgia Superior Court Clerks’ Cooperative Authority index and look for a reference to O.C.G.A. § 44-3-220. If you cannot find it, ask the association in writing to identify its lien authority.

    How an Atlanta HOA Debt Turns Into a Foreclosure Filing

    The path from a missed $135 monthly payment to a lawsuit is short, and most of the growth in the balance happens in the middle of it.

    StageWhat happensWhat it adds
    Assessment goes unpaidA lien attaches automatically under the POAA — no filing, no recording required. The recorded declaration is the public notice.The assessment itself
    Late charges applyThe association may add a late charge of the greater of $10 or 10% of each assessment or installment.10% per installment, repeating
    Interest and finesInterest runs from the due date at up to 10% per year, and covenant violation fines join the lien as they come due if the declaration allows them.Fines are often the largest piece
    File goes to counselCourt costs and reasonable attorney’s fees actually incurred become collectible.Often more than the original debt
    30-day noticeCertified mail or statutory overnight delivery, return receipt requested, to the lot address and any other address you designated in writing, stating the amount due, late charges, and interest rate.The mandatory pause
    Lawsuit filedJudicial foreclosure action in Superior Court. The association may also claim the property’s fair rental value from filing until sale or satisfaction.Fair rental value
    Judgment and court-ordered saleIf the association wins, the court orders a foreclosure sale, subject to superior liens. The association may bid.The house

    Look closely at where the money comes from. A homeowner who skipped four quarterly assessments of $300 owes $1,200 in dues. Add late charges, a year of interest, two covenant fines, and a few hours of attorney time, and the demand letter says $6,800. That is not an error or a scam — it is the statute working as written. It is also why the window to resolve this cheaply closes fast.

    One more thing associations rarely spell out: foreclosure is not their only weapon, and often not their real one. An association can sue you personally for a money judgment on the debt without touching the house at all, then pursue garnishment and levy like any other judgment creditor. Many Atlanta associations prefer that route because it avoids the first mortgage problem entirely.

    Seven Things That Actually Stop an HOA Foreclosure in Georgia

    Ranked roughly by how quickly each one can work. Several are procedural, and procedural defenses are unusually strong in this area of Georgia law because the statute imposes hard requirements on the association.

    1. Demand a written statement of the amount due — and time it

    This is the most underused tool a Georgia HOA homeowner has. Both the POAA and the Condominium Act require an association to furnish, on written request, a statement of the amounts due on the lot or unit. If the association fails to mail or otherwise furnish that statement within five business days of receiving a proper request, Georgia law provides that the lien is extinguished.

    Read that again. A slow or disorganized management company can lose the lien entirely by missing a deadline. Send the request in writing, by certified mail with return receipt, keep the green card, and calendar the fifth business day. This is a technical remedy and the details matter — have a Georgia attorney confirm the request is properly framed before you rely on it — but in a market where many Atlanta communities are managed by overloaded third-party firms, it works more often than boards would like to admit.

    2. Check the $2,000 threshold, and what is inside it

    If the association cannot show at least $2,000 subject to the lien, it cannot bring a foreclosure action. Ask for an itemized ledger and separate the categories yourself: assessments, late charges, interest, fines, and attorney’s fees. Homeowners are often surprised to find that actual unpaid dues are a minority of the balance.

    This distinction is about to get sharper. Reporting on SB 406 indicates the threshold rises to $4,000 on January 1, 2027, with fines and fees expressly excluded from the calculation — meaning only real assessments would count toward it. If that holds, a large share of the marginal Atlanta foreclosure cases become impossible to file. Confirm the current text with counsel before relying on it, but if your balance is mostly fines, the calendar is now on your side.

    3. Check the four-year lapse

    An assessment lien lapses and has no further effect four years after the assessment or installment first became due and payable, along with late charges and interest applicable to it. Associations that let a delinquency drift — common in self-managed Atlanta communities with board turnover — can lose the oldest portion of what they are claiming. Ask for the ledger by date, not just the total.

    4. Attack the attorney’s fees — this changed on July 1, 2026

    Attorney’s fees are frequently the largest and least examined line on an HOA demand. Section 7 of SB 406 took effect July 1, 2026 and applies to actions filed on or after that date. It requires prior written notice and an itemized statement before an association can recover attorney’s fees from a homeowner, and it makes those fees subject to judicial review for reasonableness.

    If your case was filed after July 1, 2026, ask for the itemization in writing. If the association cannot produce it, or the hours look inflated relative to a routine collection file, that is now a live issue a judge can rule on rather than a line item you simply have to accept. This is the newest and least-used defense in Georgia, and most homeowners facing collection right now have never heard of it.

    5. Verify the 30-day notice was done correctly

    The pre-foreclosure notice is not a formality. It must go by certified mail or statutory overnight delivery with return receipt requested, to the lot address and to any other address you designated to the association in writing, and it must specify the amount then due together with authorized late charges and the interest rate accruing.

    Failures here are common, especially for owners who moved, rented the property out, inherited it, or gave the association a mailing address that got lost in a management company transition. If you never designated an alternate address, do it now in writing — it protects you going forward. If notice was defective, that is an argument to raise in the answer, not something to mention casually on the phone.

    6. Negotiate — and understand how your payments get applied

    Most Atlanta HOA collection files settle. Boards would rather have money than a lawsuit that will not clear the first mortgage. Put a written offer in front of them — a lump sum, or a plan with dates — and ask specifically for a waiver or reduction of fines and fees, since those are the most discretionary components.

    Insist that the agreement state how payments are applied. Historically, some Georgia associations applied incoming money to fines and attorney’s fees first, so a homeowner making payments stayed perpetually delinquent on assessments and kept generating new late charges. SB 406 addresses this directly for 2027 by requiring payments be applied to assessments before fines or fees. Until then, negotiate for it in writing.

    7. Sell before judgment

    If the balance is beyond reach or the community is no longer affordable, selling ends the problem cleanly. HOA liens are paid at closing out of the proceeds, just like a tax lien or a mortgage payoff. You do not need to clear the debt first; you need enough equity and enough time.

    One practical note specific to HOA debt: closings require a payoff or estoppel letter from the association or its management company, and those letters can take a week or more and often carry their own fee. Order it the day you decide to sell. Our guide to selling property with a lien on it in Georgia covers how multiple payoffs get coordinated at the table.

    A note on bankruptcy

    A bankruptcy filing triggers an automatic stay that halts collection, including an HOA foreclosure action, and Chapter 13 can restructure the arrears over time. Be aware that assessments coming due after the filing are generally your responsibility going forward. This is a real option with consequences well beyond the HOA balance, and it belongs to a Georgia bankruptcy attorney rather than an article.

    What Changed in 2026: Georgia’s Property Owners’ Bill of Rights Act

    Governor Kemp signed SB 406, the Georgia Property Owners’ Bill of Rights Act, on May 12, 2026. It passed the Senate 51–0 and the House 155–10 — a level of agreement that tells you something about how Georgia legislators were hearing from constituents. It is the most significant change to Georgia HOA law in decades, and most of it lands on January 1, 2027.

    If you are facing collection right now, in the fall of 2026, you are sitting in the gap between the old rules and the new ones. That timing is worth understanding.

    Already in effect (July 1, 2026)

    • Associations cannot recover attorney’s fees without prior written notice and an itemized statement, and those fees are subject to judicial review for reasonableness. Applies to actions filed on or after July 1, 2026.

    Effective January 1, 2027

    • Mandatory registration with the Georgia Secretary of State. No person may operate a homeowners association in Georgia unless registered. An association that fails to register forfeits its ability to collect fines or fees, file or record liens, or initiate foreclosure. Registrations expire December 31 each year.
    • A state complaint process. A resident claiming harm from an association’s action or inaction may file a written complaint with the Secretary of State within 180 days. A hearing officer investigates and may order a hearing.
    • An automatic stay on collection. Filing a complaint automatically stays the association’s collection of any fines or fees that are the subject of the complaint, expiring on the hearing officer’s conclusions and extendable 15 days.
    • Appeals to magistrate court, or otherwise to the superior court where the largest portion of the development sits — for most readers, Fulton County Superior Court or the equivalent in DeKalb or Cobb.
    • Recordkeeping and fine procedure. Ten-year record retention, notices that cite the specific rule with a cure period before a fine, and payment applied to assessments before fines or fees.
    • A higher foreclosure threshold, reported at $4,000 in unpaid assessments with fines and fees excluded from the calculation.
    Why the timing matters to you. If your association is disorganized — no registration, thin records, fines issued without citing a rule, no itemized attorney’s fees — its position gets materially weaker after January 1, 2027. That is not a reason to ignore a lawsuit filed today. It is a reason to slow the file down, insist on documentation in writing, and get advice before conceding anything.

    HOAs in the Atlanta Market: What the Numbers Actually Show

    Atlanta is one of the most HOA-saturated housing markets in the country, and that is a relatively recent development driven by how the region grew.

    Roughly 53% of metro Atlanta homes listed for sale in 2025 carried an HOA fee — well above the national figure of about 44% and the Georgia statewide figure near 46%. The median monthly fee in metro Atlanta reached $135, up from $125 in 2024 and $108 in 2019, while the Georgia statewide median sat around $75. Georgia now has roughly 11,200 community associations, with hundreds added in the past two years.

    Those medians hide enormous spread. Atlanta condominium fees commonly run $300 to $600 a month, and Midtown and Buckhead high-rises with concierge staff and structured parking regularly exceed that. Detached homes in master-planned communities in north Fulton, Gwinnett, and Henry often sit between $100 and $250. Gated and luxury communities can run into four figures.

    Why the fees keep climbing

    • Insurance. Master policy premiums have risen sharply, and condominium associations have absorbed the worst of it. This is the single biggest driver of Atlanta fee increases in the last three years.
    • Deferred maintenance. Communities built in the 2000s boom are hitting the age where roofs, private streets, retention ponds, and amenity structures need replacing at once.
    • Underfunded reserves. An association that kept dues artificially low for a decade eventually issues a special assessment. Special assessments are where Atlanta homeowners most often get financially blindsided — a $6,000 demand with a 60-day deadline is not unusual, and unpaid, it becomes lien-eligible like any other assessment.

    The impacts homeowners underestimate

    • Mortgage qualification. Lenders count HOA dues in your debt-to-income ratio. At the Georgia single-family average, dues can reduce the purchase price a buyer qualifies for by roughly $27,000. When you sell, that shrinks your buyer pool.
    • Resale friction. Buyers scrutinize reserve studies, pending litigation, and special assessment history. A community with a known assessment coming sells slower and cheaper.
    • Financing eligibility. Condominium projects must meet lender and FHA requirements on owner-occupancy ratios, delinquency rates, insurance, and reserves. If enough neighbors fall behind, the whole building can become hard to finance — which drops values for everyone, including the owners who paid on time.
    • Rental restrictions. Many Atlanta associations cap leased units, so owners who planned to rent rather than sell sometimes find the cap is full.
    • The closing chokepoint. No Georgia closing attorney will disburse without an HOA payoff letter. Associations know it, which is precisely why HOA debt gets resolved at closing tables even when it has been ignored for years.

    HOAs in Atlanta: An Honest Look at Pros and Cons

    It is easy to write a one-sided piece about HOAs when someone is being sued by one. The reality is genuinely mixed, and if you are deciding whether to fight, pay, or move, you should weigh both sides.

    ProsCons
    Property value protection. Enforced standards prevent the one derelict house that drags down a street — a real concern in older intown neighborhoods with mixed ownership.Costs rise faster than income. Metro Atlanta median dues climbed 25% in six years, and nothing requires them to track what residents can afford.
    Shared amenities. Pools, tennis courts, clubhouses, playgrounds, and gyms cost far less collectively than individually.Special assessments. A lump-sum demand can arrive with little warning and become lien-eligible if unpaid.
    Maintenance of shared infrastructure. Private streets, retention ponds, entrance landscaping, and street lighting have to be paid for by somebody, and the county will not do it.Enforcement can be arbitrary. Selective fining and personality-driven boards are the most common complaint from Georgia homeowners, and were the impetus for SB 406.
    New oversight. As of 2027, registration, records, and a state complaint process give Georgia homeowners real recourse for the first time.Volunteer governance. Most boards are unpaid neighbors, and the quality of financial management varies wildly from community to community.

    The fair summary: HOAs deliver genuine value in communities with shared physical infrastructure, and considerably less in a subdivision of detached houses on public streets where the association exists mainly to police paint colors. If you are in the second kind and the fees have become a burden, that is worth weighing honestly when you decide whether this house still fits.

    Fulton County: Where This Plays Out Locally

    If your property is in Fulton County, the HOA’s foreclosure action is filed in Superior Court, and a smaller money-judgment claim may be filed in Magistrate Court. Knowing where the paper goes helps you track your own case rather than relying on what the association’s attorney tells you.

    For property-specific background on the county, see our Fulton County page and the city pages for East Point, College Park, South Fulton, Roswell, Alpharetta, and Johns Creek.

    The Other Lien: Delinquent Property Taxes in DeKalb County

    Homeowners fighting an HOA rarely fight only an HOA. Financial pressure does not arrive one bill at a time, and the tax lien is the one that can actually take the house quickly. If you own in DeKalb, the second clock deserves as much attention as the first — arguably more, because a county tax lien outranks nearly everything, including your mortgage and your association.

    The DeKalb delinquent tax calendar

    DeKalb mails bills in mid-August and splits the year into two installments, the first due September 30 and the second in mid-November. Miss them and interest accrues monthly at the bank prime rate plus 3% (O.C.G.A. § 48-2-40), with a 5% penalty attaching at 120 days past due and again every 120 days after, up to 20% of the original bill (§ 48-2-44).

    Then comes the date that separates DeKalb from a vague sense of “someday.” State law directs the Tax Commissioner to issue a Fi.Fa. — a recorded tax execution — against all delinquent taxpayers on December 31 each year (O.C.G.A. § 48-3-3). From there the parcel can be levied, advertised for four consecutive weeks in The Champion Newspaper, and sold. DeKalb holds tax sales generally April through December, on the first Tuesday of the month at 12:00 p.m. on the courthouse steps in Decatur, with bidding opening at taxes plus levy, recording, advertising, and commission costs.

    The detail that costs DeKalb homeowners their houses: once a property is scheduled for tax sale, DeKalb will not accept personal checks, business checks, third-party checks, money orders, or debit and credit cards. Payment must be cash, a cashier’s check, or a wire. Homeowners who plan to put the taxes on a card the week of the sale find out on the wrong Monday.

    If the sale happens, you keep a 12-month right of redemption, but the price is the winning bid plus any taxes the purchaser paid, plus 20% for the first year and 10% for each year after (O.C.G.A. § 48-4-42) — not your original tax bill. And if the property sold for more than was owed, the surplus is excess funds that belong to you. DeKalb requires those claims be filed by the entitled party or their Georgia-licensed attorney, and does not accept powers of attorney, which disqualifies most recovery firms that will call you.

    Start with the DeKalb Tax Commissioner’s delinquent taxes page and tax sales page, search and pay through the DeKalb payment portal, check the tax sale property listing to see whether your address is on it, and review exemptions you may be missing. Our deeper guides: how long you have to pay delinquent property taxes in DeKalb, Decatur property taxes, tax foreclosure in Georgia, and how many years you can be behind.

    How the two liens interact

    • Priority order. The county tax lien generally comes first, then the first mortgage, then the HOA. An HOA foreclosure does not clear the taxes, and a tax sale can wipe out the association’s position entirely.
    • Different speeds. The HOA has to sue you and win. The county does not. If both are moving, the tax clock is usually the urgent one.
    • They compound. Dues accrue while you fight the taxes, and taxes accrue while you fight the association. Neither pauses for the other.
    • One closing solves both. In a sale, the taxes, the mortgage, and the HOA payoff are all handled at the table in priority order out of the same proceeds.

    For a broader view of the tax side, see our pages on tax-delinquent property, DeKalb County, Fulton County tax sales, and Fulton County excess funds, plus what an interpleader action is if a surplus claim is contested.

    When Selling Is the Right Answer

    Sometimes the honest math says the house no longer works. If you have equity, selling captures it: the HOA lien, the mortgage, and any tax balance are paid from the proceeds in priority order, the liens are released, and you keep the remainder. Compare that with a judgment, garnishment, and a balance that keeps growing on a house you cannot afford to keep anyway.

    Timing is the constraint. A traditional listing takes 30 to 60 days to contract and another 30 to close, plus commission, plus repairs a buyer’s inspector will find, plus the HOA payoff letter delay. A cash purchase typically closes in 7 to 14 days, as-is, with the payoffs coordinated by a Georgia closing attorney. If the house needs work, that is not a barrier — see how to sell a house that needs lots of work and I want to sell my ugly house. If you inherited the property and the deed is still in a relative’s name, start with probate real estate in Atlanta and selling inherited property. If you live elsewhere, see how we work with out-of-state owners.

    Frequently Asked Questions

    Can an HOA really take my house in Georgia if my mortgage is current?

    Yes — the association’s right to enforce its lien has nothing to do with whether you are current on your mortgage. But it has to do it the hard way: sue you, obtain a judgment, and get a court order. There is no nonjudicial shortcut for HOA liens in Georgia, and the sale is subject to superior liens, meaning your mortgage survives it.

    How much do I have to owe before my HOA can foreclose?

    Under current law, at least $2,000 subject to the lien. Reporting on SB 406 indicates that rises to $4,000 in unpaid assessments on January 1, 2027, with fines and fees excluded from the count. Ask for an itemized ledger and check what your balance actually consists of before you assume the threshold is met.

    Can they add attorney’s fees on top of what I owe?

    Yes, but not freely anymore. As of July 1, 2026, for actions filed on or after that date, an association must give prior written notice and an itemized statement before recovering attorney’s fees, and a court can review them for reasonableness. Request the itemization in writing.

    My HOA has not sent me anything in months. Can they just file?

    Not without the statutory notice. At least 30 days before starting a foreclosure the association must send notice by certified mail or statutory overnight delivery with return receipt requested, to the property address and to any other address you designated in writing, stating the amount due, authorized late charges, and the interest rate. Defective notice is a defense worth raising.

    Can I stop the fines by paying just the dues?

    Not automatically, and how your payments are applied matters enormously. Some associations historically applied payments to fines and fees first, leaving you perpetually behind on assessments and generating fresh late charges. SB 406 requires assessments-first application starting in 2027; until then, get the application order in your written agreement.

    Can I sell my house with an HOA lien on it?

    Yes. HOA liens are routinely paid at closing from the sale proceeds, the same as a mortgage payoff or a tax lien. What you need is enough equity and enough time, plus a payoff letter from the association or its management company — order that early, because it is often the slowest piece of the closing.

    I owe both my HOA and back property taxes. Which do I deal with first?

    Usually the taxes, because the county does not need a lawsuit and its lien has priority. That said, both keep growing and neither waits for the other. Get the exact tax payoff and the itemized HOA ledger in writing on the same day, then decide with real numbers rather than estimates. See what happens if you don’t pay property taxes.

    I am behind on the mortgage too. Does that change anything?

    It adds a third clock running independently of the other two, and the mortgage foreclosure is nonjudicial, so it can move faster than the HOA case. See the 120-day foreclosure rule and can I sell my house if it’s in foreclosure.

    The Bottom Line

    An HOA foreclosure in Atlanta is slower and more fragile than the demand letter suggests. Your association has to sue you, clear a dollar threshold, prove it sent the right notice to the right addresses, justify its fees to a judge, and win a case that will not even clear the first mortgage. That is a lot of friction, and friction is leverage.

    Use it deliberately. Get the ledger itemized. Send the written request for a statement of amounts due and calendar five business days. Separate assessments from fines. Ask for the fee itemization. And run honest numbers on whether this house, with these dues, still works for you — because the homeowners who come out of this whole are the ones who decided on their own timeline instead of a court’s.

    If selling is the path that fits, we buy houses, condos, land, and mobile homes across metro Atlanta as-is — HOA liens, back taxes, code liens, and contents included. No fees, no commissions, no repairs, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us. We will tell you honestly if fighting it or paying it makes more sense than selling.

    Related reading: HOA foreclosure basics · selling property with a lien in Georgia · tax-delinquent property · Fulton vs. DeKalb property taxes · senior property tax relief in Atlanta · about our team · more on the blog

  • How Do I Stop a Tax Sale on My DeKalb County Home?

    How Do I Stop a Tax Sale on My DeKalb County Home

    A stop-the-sale playbook for DeKalb County homeowners — Decatur, Stone Mountain, Lithonia, Stonecrest, Tucker, Clarkston, Brookhaven, Chamblee, Doraville, Dunwoody, Avondale Estates, and unincorporated south DeKalb.

    If your DeKalb County home is headed for a tax sale, you are not looking for a general explanation of Georgia tax law. You are looking for the answer to one question: what actually stops this, and how many days do I have to do it?

    This guide answers that directly. It is organized around the DeKalb County calendar rather than the statute book, because the deadline that matters to you is a specific Tuesday at noon on the courthouse steps in Decatur — not an abstraction. Everything below is written for a homeowner trying to keep a house, or trying to walk away from one with equity instead of nothing.

    Short answer: A DeKalb tax sale stops when the debt is satisfied before the auction — by you paying it, by another party paying it, or by a sale that pays it at closing. It does not stop because you appealed, because you never got the bill, or because you called and explained. Once your parcel is scheduled, DeKalb will only take cash, a cashier’s check, or a wire. The sale is held the first Tuesday of the month at 12:00 p.m. in front of the DeKalb County Courthouse.

    Step One: Find Out Whether You Are Actually on the List

    Homeowners routinely panic over a letter that is months from mattering, and other homeowners sleep through an advertisement that ran four weeks in a row. Before anything else, establish two facts.

    • Is there a Fi.Fa. recorded against the parcel? In DeKalb, this is close to a calendar event. State law directs the Tax Commissioner to issue an execution against all delinquent taxpayers on December 31 of each year (O.C.G.A. § 48-3-3). If your balance rolled past year-end, assume a lien exists and verify it.
    • Has the parcel been levied and scheduled? DeKalb publishes its tax sale property listing online, and notice runs once a week for four weeks before the sale in the county legal organ, The Champion Newspaper. If your address is on that list, your timeline is measured in weeks.

    You can confirm both by calling the Tax Commissioner at 404-298-4000, or 404-298-3053 for tax sale questions specifically, and by pulling your account on the DeKalb property tax portal. Ask for one number in writing: the total payoff good through a specific date. Interest accrues monthly, so a figure quoted verbally in March is wrong by May.

    The DeKalb Delinquent Property Tax Clock

    DeKalb mails tax bills in mid-August and splits the year into two installments, the first due September 30 and the second in mid-November. Miss them and three things start running at once.

    StageWhat happensWhat it costs
    Day after the due dateThe balance is delinquent. Interest begins accruing monthly at the bank prime rate plus 3% annually (O.C.G.A. § 48-2-40).Small at first, compounding
    120 days past dueA 5% penalty attaches to the unpaid principal, and again every 120 days after that (O.C.G.A. § 48-2-44).Up to 20% of the original bill
    December 31The Tax Commissioner issues a Fi.Fa. — a recorded tax execution against the property and owner of record.Recording and administrative costs
    Levy and advertisementThe parcel is levied, added to the sale list, and advertised for four consecutive weeks.Levy, advertising, and commission costs
    First Tuesday, 12:00 p.m.The auction is held on the courthouse steps in Decatur. Bidding opens at taxes plus all costs.The house

    Two DeKalb-specific details are worth circling. First, DeKalb generally holds sales monthly from April through December, and reserves the right to add or cancel dates. That means there is rarely a long dormant season to hide in, but it also means a parcel can sit levied for a while before it appears on a list. Second, a tax lien in Georgia attaches at the January 1 valuation date and is superior to almost every other lien on the property — including your mortgage. That priority is exactly why a tax debt of a few thousand dollars can move a house that carries a much larger loan.

    Our companion piece on how long you have to pay delinquent property taxes in DeKalb County walks the same calendar in more depth, and what happens if you don’t pay property taxes covers the statewide version.

    Six Ways to Stop a DeKalb County Tax Sale

    Ranked roughly by how much time each one needs. If your sale date is inside three weeks, skip to numbers one, five, and six.

    1. Pay the balance in full before the sale date

    The cleanest answer, and the only one that is guaranteed to work. Get the written payoff, pay it, and confirm the levy has been released rather than assuming.

    The trap almost nobody sees coming: once a property has been scheduled for tax sale, DeKalb will not accept personal checks, business checks, third-party checks, money orders, or debit and credit cards. Payment must be cash, a bank-issued cashier’s check, or a wire. Homeowners who plan to put the taxes on a card the week of the sale discover this on the wrong Monday. If you are close to the date, get certified funds in hand first and ask exactly where and by what time they must be delivered — the sale runs at noon, and money that clears at 2:00 p.m. clears too late.

    2. Start partial payments early, and ask what DeKalb will work with

    DeKalb accepts partial payments, and you can make as many as you want. Every dollar paid shrinks the principal that penalties and interest compound against. This is not a formal payment plan and it does not by itself stop a levy, but a shrinking balance and a visible payment history give you a far better conversation with the Delinquent Collections staff than silence does.

    Go in person if you can — there are three DeKalb tax offices, central in Decatur, north, and south — and go early. Staff have room to work with a homeowner who calls in February. They have almost none the week a sale is advertised.

    3. Fix the bill itself: exemptions and assessment appeals

    This will not rescue you from a sale next month, but it is the difference between solving the problem once and repeating it every year. Two levers:

    4. Fix the title problem underneath the tax problem

    In south DeKalb especially, a large share of tax-sale parcels are heirs’ property: a house still deeded to a parent or grandparent who died years ago, occupied by family, with the tax bills going to a name nobody answers to anymore.

    This is not a side issue. If you are not the owner of record, you cannot claim homestead, you may never receive the notices, and you cannot sell or refinance to raise the money. Somebody has to obtain authority through DeKalb County Probate Court at 556 North McDonough Street in Decatur. Start with probate real estate in Georgia and selling inherited property. If a sale date is already set, do both tracks at once — open the estate and pursue a payoff — rather than waiting for the court.

    5. Sell before the first Tuesday

    If the payoff is out of reach, this is usually the best outcome still available, and it is the one homeowners consider last. In a normal closing the delinquent taxes are paid directly out of the proceeds before you receive anything, so the debt clears at the closing table rather than out of your pocket, and whatever equity remains is yours.

    Compare that with the alternative. A DeKalb tax sale opens at taxes plus costs. A house with $180,000 of equity behind a $9,000 tax debt can transfer for a small fraction of its value, and while the surplus is legally yours, collecting it is a separate fight described below. Selling ahead of the date — even at a discount — almost always leaves a family with more.

    Speed is the whole point here. A traditional listing takes 30 to 60 days to reach a contract and another 30 to close, which does not fit inside an advertised sale. A cash purchase typically closes in 7 to 14 days, with the payoff verified in writing and the taxes disbursed at closing by a Georgia closing attorney. If the house needs work, that does not disqualify it — see how to sell a house that needs lots of work and I want to sell my ugly house. If there are other liens attached, that is normal too — see can I sell property with a lien on it in Georgia.

    6. Let someone else with an interest pay it

    You are not the only party who loses if the house sells. Anyone with a recorded interest can redeem or pay, and some of them will.

    • Your mortgage servicer. A tax lien outranks the security deed, so servicers frequently advance delinquent taxes to protect their collateral and add the amount to your loan. That is not free — it becomes an escrow shortage — but it beats an auction. Call and tell them there is a scheduled tax sale.
    • A family member or co-heir, who can pay the taxes directly on the parcel without any transfer of title. Paying the bill does not require owning the house.
    • A bankruptcy filing, which triggers an automatic stay. This is a real tool and a serious one, with consequences well beyond the tax bill. It belongs to a Georgia bankruptcy attorney, not to an article.

    One thing not on this list: deeding the house to a relative for a nominal amount. The taxes travel with the property, the transfer can trip a due-on-sale clause, and it can create gift-tax and basis problems that cost more than the tax bill. We covered why in can you sell a piece of land for $1 in Georgia.

    What Does Not Stop a Tax Sale

    Every one of these has cost a DeKalb homeowner a house.

    The beliefThe reality
    “I never got a bill, so they can’t sell it.”Non-receipt does not extend a deadline. Notice to the address of record is sufficient, and if the deed is in a deceased relative’s name, the mail is going somewhere you never see.
    “My mortgage escrow handles the taxes.”Until it doesn’t. When a loan is sold, refinanced, or paid off, escrow quietly stops — one of the most common ways a paid-up homeowner becomes delinquent.
    “I filed an appeal, so the sale is paused.”An appeal addresses value, not collection, and it does not erase a balance already under a Fi.Fa.
    “Someone at the office told me it would be fine.”Get any arrangement in writing, with a name and a date. Verbal reassurance is not a release of levy.
    “I’ll list it with an agent.”A listing is not a closing. Nothing stops the sale until the debt is actually satisfied.
    “Someone offered to pay my taxes if I sign the deed.”Sometimes legitimate, often not. No deed should transfer outside a real closing with a Georgia attorney and funds disbursed at the table.

    The Last 30 Days: A Practical Sequence

    1. Confirm the sale date and the payoff in writing. Call 404-298-4000. Ask for the total good through the sale date, and ask whether the parcel is confirmed on the list.
    2. Ask what form of payment is required and where to deliver it. Assume certified funds. Confirm the cutoff hour, not just the day.
    3. Pull every recorded lien against the property through the GSCCCA lien index so nothing surfaces mid-closing — code enforcement, HOA assessments, judgments, an old security deed never released. HOA liens in particular catch people off guard; an HOA can foreclose even on a paid-off house.
    4. Call the mortgage servicer if there is a loan, and say the words “scheduled tax sale.”
    5. Run the equity math. Realistic value, minus the tax payoff, minus any mortgage payoff, minus other liens. If the number is meaningfully positive, do not let this reach the courthouse steps.
    6. Line up the fallback in parallel. Get a written cash offer while you are still pursuing the payoff. Having two paths open on the same day costs nothing; discovering on day 26 that you only had one is what costs people the house.
    7. Get free legal help if cost is the barrier. Atlanta Legal Aid Society serves income-qualifying DeKalb residents on housing, foreclosure, and heirs’ property matters.

    If the Sale Already Happened

    It is not over, but the terms get harsh. You keep a 12-month right of redemption from the sale date, and during that year the purchaser holds a defeasible title — they cannot take possession, collect rent, or improve the property.

    The redemption price is not your old tax bill. Under O.C.G.A. § 48-4-42 it is the amount paid for the tax deed at the sale, plus any taxes the purchaser has paid since, plus 20% of that amount for the first year or fraction of a year, and 10% for each additional year. Certified funds, in a lump sum. A homeowner who could not raise $6,000 is now being asked for the bid plus a premium, which is why the right rescues fewer DeKalb homes than people expect.

    After twelve months the purchaser may serve a barment notice on everyone with a recorded interest and permanently foreclose your right to redeem. If one arrives, that is the moment for a real estate attorney, not more research.

    Excess funds: money DeKalb may be holding for you

    If the sale brought more than the taxes, costs, and fees owed, the surplus belongs to the former owner and other parties with a recorded interest — not the county and not the buyer. On a DeKalb house sold over a modest debt, that can be tens of thousands of dollars.

    DeKalb’s rules are specific and worth knowing before you hire anyone. Claims go to Delinquent Collections Claims through the delinquent taxes page, must be filed by the entitled party or their Georgia-licensed attorney, and powers of attorney are not accepted — which means most recovery firms cannot file for you regardless of what they promise. If competing claims arise, the Tax Commissioner may interplead the funds into Superior Court, after which the office cannot give you updates. Our explainer on what an interpleader action is covers what to do if you are named, and our excess funds guide walks through the claim itself.

    Where This Hits Hardest in DeKalb

    The pressure is not evenly distributed across the county, and the reason a homeowner falls behind tends to track geography.

    • South DeKalb — Lithonia, Stonecrest, Redan, Ellenwood, the Candler Road and Flat Shoals corridors. The highest concentration of heirs’ property and long-vacant parcels. Title problems, not affordability, are frequently the real obstacle.
    • Stone Mountain, Clarkston, Scottdale, Pine Lake. Older housing stock, many owners on fixed incomes, and a lot of paid-off homes where escrow disappeared years ago and the bill started arriving directly.
    • Decatur. A category of its own: two separate taxing authorities, four deadlines, and a city that assesses at 50% of fair market value rather than the county’s 40%. A Decatur parcel can be perfectly current with one office and delinquent with the other — see Decatur property taxes vs. DeKalb County.
    • North DeKalb — Brookhaven, Chamblee, Doraville, Dunwoody, Tucker. Rapid appreciation, rising assessments, and long-time owners whose bills have outgrown their incomes. Exemptions and appeals matter most here.

    If you are comparing counties, our breakdown of Fulton County vs. DeKalb County property taxes explains why identical houses across the line carry different bills.

    DeKalb County Resources

    Frequently Asked Questions

    How late can I pay to stop a DeKalb tax sale?

    Up until the debt is satisfied on the day of the sale, but treat that as theory rather than plan. The auction runs at 12:00 p.m. on the first Tuesday, payment must be in certified funds once a parcel is scheduled, and it has to be received and posted before the property is called. Confirm the cutoff with the Tax Commissioner rather than assuming you have until noon.

    Can I set up a payment plan to stop the sale?

    DeKalb accepts partial payments, and paying down the balance early gives you a much better conversation with the Delinquent Collections staff. But partial payments do not by themselves halt a levy, and arrangements are far more available before a sale is scheduled than after. Ask directly, get any agreement in writing, and do not rely on a verbal assurance.

    Will filing an appeal stop the tax sale?

    No. An appeal addresses what the property is worth, not whether the current balance is collectible, and it does not remove a Fi.Fa. that has already been recorded. Appeal anyway if the value is wrong — it lowers what accrues next year — but do not treat it as a shield.

    Can I sell my DeKalb house if there is already a tax sale date?

    Usually yes, if there is enough runway to close. The taxes are paid from the proceeds at closing and the levy is satisfied before the auction. The constraint is time, not permission: a cash closing typically runs 7 to 14 days, which fits inside an advertised sale window, while a traditional listing generally does not.

    The house is still in my late mother’s name. Can I stop the sale?

    You can pay the taxes — anyone can. What you cannot do without authority is sell or refinance. That requires letters from DeKalb County Probate Court, or resolving an heirs’ property situation among relatives. Open that process now and pursue the payoff at the same time; see how to sell inherited property.

    I am behind on the mortgage too. Which one moves first?

    They run on separate tracks and neither slows the other. Federal rules generally bar a servicer’s first foreclosure filing until a residential loan is more than 120 days delinquent — see the 120-day foreclosure rule — but DeKalb can proceed to a tax sale on its own schedule regardless. Address both, and start with whichever has an actual date attached.

    What if I own vacant land in DeKalb rather than a house?

    The same process applies, and land is more exposed because nobody lives there to notice the mail. See tax-delinquent land, property taxes on vacant land, and our DeKalb County page. We buy vacant land and mobile homes on land as well as houses.

    The Bottom Line

    A DeKalb County tax sale is stopped by money reaching the Tax Commissioner before noon on a specific Tuesday — your money, a servicer’s money, a relative’s money, or a buyer’s money at a closing table. Nothing else in this process cares how reasonable your explanation is.

    The homeowners who keep their equity are rarely the ones with savings. They are the ones who called for the payoff figure early, found out what form of payment the county would take, and kept a second option open while they worked the first.

    If selling is the option that fits your timeline, we buy houses, land, and mobile homes across DeKalb County as-is — back taxes, liens, and contents included — with no fees or commissions, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us about your situation. We will give you a straight answer either way, including when the answer is to go pay the county instead.

    Related reading: tax-delinquent property · tax foreclosure in Georgia · how many years you can be behind on property taxes · can I sell my house if it’s in foreclosure · DeKalb County · about our team · more on the blog

    Decatur, GA, USA
  • Can You Sell a Piece of Land for $1 in Georgia?

    east point land in Fulton County

    Short answer: yes. A $1 land sale is legal in Georgia and the deed will record. But the dollar figure on the deed is a legal formality, not a valuation — and the IRS, the county tax assessor, Medicaid, and your creditors all ignore it entirely.

    People ask this question for good reasons. You want to move a parcel to your daughter. You are tired of paying taxes on land you will never build on. You want to get a lot out of your name before something happens. A neighbor offered to take it off your hands. Somewhere along the way, someone told you that you can just sell it for a dollar.

    They were not lying. They were just leaving out the part that costs money.

    Why a $1 Sale Is Legal in the First Place

    Contract law requires consideration — something of value exchanged — for a binding agreement. What it does not generally require is that the consideration be adequate. Courts have long declined to sit as appraisers of private bargains. If you agree to convey land for one dollar, a dollar is consideration, and the transfer is valid.

    This is why you see deeds reciting “$10.00 and other good and valuable consideration.” It is boilerplate. It satisfies the technical requirement without disclosing the actual price. A $1 recital does the same job.

    So the deed is enforceable, the clerk will record it, and title will pass. That is the entire good news section of this article.

    Nobody Who Matters Believes the Dollar

    Here is the misunderstanding at the center of almost every regretted $1 transfer. People assume that if the deed says one dollar, the transaction is treated as a one-dollar transaction. It is not. Four different authorities will look straight past that number to the property’s fair market value.

    • The IRS treats the gap between what you received and what the land was worth as a gift.
    • The county board of assessors values property for tax purposes on its own schedule. A $1 sale is not a comparable sale and will not lower anyone’s assessment.
    • Medicaid reviews transfers made for less than fair market value during a look-back period when someone applies for long-term care coverage.
    • Creditors can challenge transfers made without reasonably equivalent value under Georgia’s Uniform Voidable Transactions Act.

    A dollar buys you a valid deed. It does not buy you a different tax result, a lower assessment, or protection from anyone.

    The Gift Tax Side

    If you convey land worth $60,000 for $1, the IRS generally treats roughly $59,999 of that as a gift from you to the buyer. That is not automatically a disaster, but it does have mechanics worth knowing.

    For 2026, the annual gift tax exclusion is $19,000 per recipient, per donor. A married couple electing to split gifts can reach $38,000 to the same person. Anything above that must be reported on IRS Form 709, generally due April 15 of the following year.

    Reporting is not the same as paying. Amounts above the annual exclusion reduce your lifetime exemption, which for 2026 sits at $15 million per individual. Most people will never approach that, so the practical consequence of a modest land gift is usually a form, not a tax bill. The gift tax is also owed by the giver, never the recipient.

    Two traps, though. Filing Form 709 is mandatory once you cross the exclusion, whether or not tax is due, and people routinely skip it because no money changes hands. And the land must be valued honestly — which usually means an appraisal, not a guess.

    The Basis Trap — The Part That Actually Costs Money

    This is the single most expensive thing most people do not know, and on land it can be brutal.

    When you gift property, the recipient generally takes your cost basis. If you bought that lot in 1994 for $8,000 and it is worth $80,000 today, your daughter’s basis is $8,000. When she eventually sells for $80,000, she has roughly $72,000 of taxable gain.

    Now compare inheritance. Property passing at death generally receives a stepped-up basis equal to its fair market value on the date of death. Had she inherited the same lot at $80,000 and sold it for $80,000, her taxable gain would be close to zero.

    So a well-meant $1 deed to a family member can hand them a tax bill that simply would not have existed if the land had passed through an estate. On appreciated land held for decades — exactly the kind of parcel people are most eager to hand off — this frequently outweighs every other consideration in this article combined.

    If the land came to you through a death in the family, this is worth working through carefully before you deed it anywhere. See selling inherited property in Atlanta and our overview of probate real estate in Georgia.

    Georgia Transfer Tax and the PT-61

    Georgia charges a real estate transfer tax under O.C.G.A. § 48-6-1 of $1.00 for the first $1,000 of consideration plus 10 cents for each additional $100 — roughly a tenth of a percent. On a $1 sale, the tax is negligible.

    There is also an exemption worth knowing: under § 48-6-2(a)(2), a deed of gift is exempt from the transfer tax entirely. Transfers from individual owners to an entity in which they hold a majority interest are also exempt, which is why moving a parcel into your own LLC rarely triggers transfer tax.

    But exemption from the tax is not exemption from the paperwork. Every deed conveying Georgia real property requires a PT-61 Real Estate Transfer Tax Declaration, filed electronically through the Georgia Superior Court Clerks’ Cooperative Authority — taxed or exempt. The clerk will not record the deed without it, and the form is transmitted to the state auditor, the county tax commissioner, and the county board of assessors. The grantor is legally responsible for filing it.

    Read that last part again. The county assessors receive a copy of every one of these. Your $1 transfer is not private, and it is not invisible.

    Liens and Problems Travel With the Land

    A $1 price does not clean anything. Whatever is attached to the parcel goes with it.

    • Delinquent property taxes stay with the land and continue accruing.
    • Code enforcement liens, HOA assessments, and judgment liens remain.
    • Easements, restrictive covenants, and access problems are unaffected.
    • A quitclaim deed — the usual instrument for these transfers — conveys whatever interest you have and warrants nothing. If your title is defective, you have handed someone a defective title.

    This matters enormously with land, because the reason people want to give a parcel away is often the reason nobody wants it: unpaid taxes. Handing a tax-burdened lot to a relative for $1 transfers the problem, not the solution. Our guides on what happens if you don’t pay property taxes, how many years you can be behind in Georgia, and tax foreclosure explain where that road ends. If taxes are already delinquent, start with our tax-delinquent property page.

    Four Situations Where a $1 Deed Causes Real Damage

    1. There is a mortgage on the property. Nearly every security deed contains a due-on-sale clause. Transferring the property without lender consent can let the lender accelerate the loan. It can also forfeit federal pre-foreclosure protections if you are already behind, since the 120-day rule has an express exception for due-on-sale violations.
    2. Long-term care is anywhere on the horizon. Medicaid applies a five-year look-back to transfers made for less than fair market value. A $1 deed inside that window can create a penalty period of ineligibility measured against the property’s actual value — often the worst possible outcome for a family that was trying to protect an asset.
    3. You have creditors or a judgment against you. Under Georgia’s Uniform Voidable Transactions Act, a transfer made without reasonably equivalent value while you are insolvent, or made to hinder or delay creditors, can be unwound by a court. The deed does not protect the land; it just adds a lawsuit.
    4. The “buyer” does not fully understand what they are taking. A relative who accepts a $1 parcel inherits the tax bill, the maintenance, the liability, and the carryover basis. Generosity that arrives without a conversation frequently ends in resentment.

    When a Nominal Transfer Genuinely Makes Sense

    None of this means $1 deeds are always wrong. They have legitimate, routine uses:

    • Moving a parcel into an LLC or trust you control, for liability or estate planning, with your attorney’s guidance.
    • Correcting title or adding a spouse to a deed.
    • Transfers between spouses, which carry an unlimited marital deduction for gift tax purposes.
    • Genuine gifts made deliberately, with the basis and reporting consequences understood and accepted.
    • Deeding a strip of land to a neighbor to resolve a boundary or access dispute.

    The distinction is not the dollar. It is whether the transfer was planned or improvised.

    Better Options for Land You Simply Do Not Want

    If the real goal is to stop owning a parcel, a $1 sale is rarely the best route. Consider:

    • Sell it, even cheaply. An actual sale gives you a clean break, a real closing, and a recorded price that reflects reality. Vacant land in metro Atlanta is often worth more than owners assume — see vacant land.
    • Donate it to a qualified charity or land trust. Done properly, this can produce a charitable deduction rather than a gift tax filing. Appraisal requirements are strict.
    • Hold it and let it pass through your estate. For appreciated land, the stepped-up basis at death is often worth more than any convenience gained by transferring now.
    • Deal with the taxes first. A parcel with clear title and current taxes is far easier to sell, gift, or donate than one under a Fi.Fa.

    Frequently Asked Questions

    Is a $1 land sale legal in Georgia?

    Yes. Consideration must exist but generally need not be adequate. The deed is valid and will record, provided it is properly executed, witnessed, notarized, and accompanied by a PT-61.

    Will I owe gift tax on a $1 sale?

    Probably not out of pocket, but you may have to file. The difference between the price and fair market value is treated as a gift. Above $19,000 per recipient in 2026, Form 709 is required, and the excess reduces your $15 million lifetime exemption rather than generating an immediate tax bill.

    Does a $1 sale lower my property taxes?

    No. County boards of assessors value property independently of what a deed recites. A nominal-consideration deed is not a valid comparable sale and will not reduce anyone’s assessment.

    Can I sell land for $1 if I still owe money on it?

    Not safely. The lien survives the transfer, and the due-on-sale clause in most security deeds lets the lender accelerate the balance. If you are behind on payments, transferring the property can also cost you federal pre-foreclosure protections — see can I sell my house if it’s in foreclosure.

    What if I live out of state and just want the parcel gone?

    That is one of the most common situations we see, and it usually has a cleaner solution than a $1 deed. See how we work with out-of-state owners.

    The Bottom Line

    You can sell a piece of land for $1. The deed will record and title will pass. But the dollar is a formality that convinces nobody with authority over the outcome — not the IRS, not the assessors, not Medicaid, not your creditors.

    The real cost of a $1 land transfer is usually not a tax bill you pay this year. It is the carryover basis you hand to somebody you were trying to help, or the lien you passed along with the deed, or the look-back period you triggered without knowing it existed. Talk to a Georgia real estate attorney and a CPA before you sign. It is a short conversation that regularly saves five figures.

    And if the goal is simply to stop owning land you no longer want — a vacant lot, an inherited parcel with back taxes, or acreage you will never build on — selling is usually cleaner than gifting. We buy land and houses across metro Atlanta as-is, with no fees or commissions, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us with a question about your parcel. We will give you a straight answer either way — including when the answer is to keep it.

    Atlanta, Georgia, 30307
  • How to Sell a House That Needs Lots of Work: 4 Options, Costs, and When Selling As-Is Makes Sense

    how to sell a house

    If you are trying to figure out how to sell a house that needs lots of work, the honest starting point is this: you have four real options, and the right one depends almost entirely on two numbers — what the house is worth fixed up, and how much cash and time you actually have to get it there. Everything else is detail.

    Most sellers in this position are not weighing a renovation the way a flipper would. They inherited the place. Or a tenant left it destroyed. Or the roof went, then the HVAC went, then the taxes came due. The house has been quietly getting worse for years, and now it needs more work than the family has money or appetite for.

    This guide walks through what “needs work” means to a buyer, what repairs realistically cost in metro Atlanta, the four ways to sell, and the specific situations where selling as-is nets you more money than fixing anything. It is written for Fulton County owners in particular, with local resources at the end.

    First, Define “Needs Lots of Work” the Way a Buyer Does

    Sellers and buyers use that phrase to mean completely different things. Sellers usually mean “it is dated and tired.” Buyers, lenders, and appraisers mean something narrower and more expensive: the house cannot be financed as it sits.

    That distinction drives your entire strategy. A conventional or FHA loan generally requires a property to be safe, sound, and sanitary. When a house fails that test, roughly 80 to 90 percent of the retail buyer pool disappears overnight, because those buyers need a mortgage and the mortgage will not fund. What is left is cash buyers, renovation-loan buyers, and investors.

    Deal-killers that push a house into the cash-only category:

    • An active roof leak, missing shingles, or visible structural sag
    • No working heat, or an HVAC system that is red-tagged
    • Knob-and-tube or aluminum wiring, an unpermitted panel, or exposed romex
    • Galvanized or failing plumbing, or water shut off long enough that the system is untested
    • Foundation movement, significant termite or moisture damage, or mold
    • Missing kitchen cabinets, missing appliances, no functioning bathroom
    • Open code violations or a condemnation placard from the city

    If your house has three or more of those, you are not selling a fixer-upper. You are selling a project, and you should price and market it that way from day one rather than discovering it after sixty days on the market and two failed appraisals.

    What Repairs Actually Cost in Metro Atlanta

    Before choosing an option, get a rough number. These are typical 2026 ranges for a 1,200 to 2,000 square foot Atlanta-area home. They are estimates for planning purposes, not quotes — get three written bids before committing to anything.

    RepairTypical Atlanta costDeal-killer for a mortgage?
    Full roof replacement$9,000 – $20,000Yes
    HVAC system replacement$7,000 – $14,000Yes
    Whole-house rewire$10,000 – $25,000Yes
    Repipe (galvanized or polybutylene)$6,000 – $15,000Often
    Foundation / structural repair$5,000 – $40,000+Yes
    Mold or water remediation$2,000 – $10,000Yes
    Termite damage repair$3,000 – $15,000Often
    Kitchen remodel$25,000 – $60,000No
    Bathroom remodel (each)$12,000 – $25,000No
    Cosmetic refresh (paint, floors, fixtures)$15,000 – $40,000No
    Full property cleanout / junk removal$500 – $3,000No
    Roll-off dumpster, 10–20 yard$400 – $750No

    Two things sellers consistently underestimate. First, repairs cascade: you cannot replace the roof without discovering the decking, and you cannot open a wall without meeting the wiring. Budget a 20 to 30 percent contingency and mean it. Second, you keep paying to own the house the entire time — taxes, insurance (which is expensive and hard to get on a vacant property), utilities, and lawn care run $600 to $1,500 a month on a typical Fulton County home.

    Option 1: Renovate First, Then List at Full Retail

    This is the highest-ceiling option and the highest-risk one. You fix everything, list with an agent, and compete with move-in-ready inventory.

    Best when: you have the cash on hand (renovation loans on a house you already own are slow and paperwork-heavy), the house is in a neighborhood where finished comps clearly support the spend, the problems are known rather than mysterious, and you have six to nine months of patience.

    The math that matters: take the after-repair value, subtract the full renovation cost, subtract 5 to 6 percent in agent commission, subtract 1 to 3 percent in seller closing costs, subtract the carrying costs for the whole project, subtract your contingency. If the remainder does not beat a straightforward as-is sale by a meaningful margin, the renovation is buying you stress rather than profit.

    Where it goes wrong: over-improving for the block, unpermitted work that surfaces at closing, and a contractor who disappears at 60 percent complete. Permits matter — in the City of Atlanta, work done without them can force expensive retroactive inspections when you sell.

    Option 2: List As-Is on the MLS

    You list with an agent, disclose the condition, and let the market price the work. No repairs, but you still get exposure to buyers who want a project.

    Best when: the house needs work but is still financeable, the location is strong enough to attract renovation-loan buyers and small investors, and you can tolerate 60 to 120 days on market plus showings of a house in rough condition.

    Understand what “as-is” does and does not mean in Georgia. It means you are not agreeing to make repairs. It does not eliminate your obligation to disclose known material defects, and it does not stop a buyer from inspecting, renegotiating, or walking during due diligence. Georgia contracts give buyers a due diligence period specifically so they can back out — and on distressed properties, many do.

    Where it goes wrong: the appraisal. A financed buyer offers a good price, the appraiser flags the roof and the missing heat, the lender requires repairs before funding, and now you are being asked to pay for a new roof on a house you are selling. That loop can repeat with two or three buyers before you accept what the house really is.

    Option 3: Sell Direct to a Cash Buyer, As-Is

    You sell the house in its current condition to a buyer who is not borrowing. No repairs, no cleanout, no showings, no appraisal, no financing contingency. This is what we do at Atlanta Land Buyers — see I want to sell my ugly house for how the process works on a distressed house specifically.

    Best when: the house is not financeable, you do not have repair money, there is a deadline (a foreclosure date, a tax sale, an estate that needs to close), the house is full of belongings, you live out of state, or heirs simply want the thing resolved.

    The honest trade-off: a cash offer on a distressed house comes in below what a perfectly renovated version would eventually fetch, because the buyer is absorbing the repair cost, the carrying cost, and the risk of what is behind the walls. What you get in exchange is real: no commission, no closing costs charged to you, no repairs, no cleanout, no appraisal, no financing falling through, and a closing in roughly 7 to 14 days. Compare net proceeds and net timelines, not headline prices.

    One thing to insist on: a written offer with the deductions shown line by line — back taxes, liens, and payoffs itemized. A verbal number over the phone is not an offer. And if you already have an offer from another buyer, say so and let a second buyer try to beat it.

    Option 4: Auction or Seller Financing

    The least common route, but occasionally the right one. At a real estate auction you set a date, market the property hard for three to four weeks, and let bidders set the price. Seller financing means you carry the note for a buyer — often a contractor — who renovates while paying you.

    Best when: the property is genuinely unusual and hard to comp, there is real competing interest, or you want income rather than a lump sum and can afford the risk of default and the cost of foreclosing.

    Where it goes wrong: auction sellers pay marketing costs and a buyer premium arrangement regardless of outcome, and a thin bidder pool produces a disappointing number with no do-over. Seller financing puts you back in the position of owning a distressed house if the buyer stops paying. Neither should be attempted without a Georgia real estate attorney.

    When Selling As-Is Actually Makes Sense

    Selling as-is is the right answer more often than sellers expect. Specifically, when any of the following is true:

    1. The repair bill exceeds what you can pay in cash. Financing a renovation on a distressed property you already own is difficult, slow, and often lands at a rate that erases the upside.
    2. There is a deadline. A scheduled Fulton County tax sale, a foreclosure sale date, or an estate that has to be settled. Once a sale is advertised, your options narrow fast — see can I sell my house if it is in foreclosure and the 120-day foreclosure rule.
    3. The house is inherited and heirs disagree. Renovation requires consensus and ongoing spending from multiple people. A single sale requires one decision. Start with probate real estate in Georgia and our guide to selling inherited property.
    4. There are liens or back taxes attached. These are usually settled from proceeds at closing rather than out of your pocket — see can I sell property with a lien on it in Georgia and selling tax-delinquent property.
    5. You live somewhere else. Managing a renovation from another state is how good money follows bad. Here is how we work with out-of-state owners.
    6. The house is full. Decades of belongings, a hoarding situation, or a tenant who left everything behind. Cleanout alone can take weeks and thousands of dollars before a single repair starts.
    7. The carrying cost is the real problem. If taxes, insurance, and utilities are bleeding you monthly on a house nobody lives in, speed is worth more than the last few percent of price.
    Quick test: Estimate the after-repair value. Subtract repairs plus 25 percent contingency, 6 percent commission, 2 percent seller closing costs, and six months of carrying costs. If that number is not clearly and comfortably above a written cash offer, selling as-is is the better trade — and it removes every risk in the renovation column.

    Georgia Disclosure: What You Still Have to Tell Buyers

    Selling as-is does not mean selling silently. Georgia sellers must disclose known material defects — problems that affect value or safety that a buyer could not reasonably discover on their own. Concealing a known foundation problem or a history of flooding creates liability that outlives the closing.

    Practical approach: write down everything you know, including things you only suspect, and hand it over. On a genuinely distressed sale to a cash buyer this costs you nothing, because the buyer is pricing for problems already. What it buys you is a closing that stays closed.

    Fulton County Specifics Worth Knowing

    Fulton is Georgia’s most populous county and one of its most aggressive on tax collection. If the house has been sitting, check the tax status before you do anything else. Look the parcel up on the Fulton County Board of Assessors site or through qPublic parcel search, then confirm the balance with the Fulton County Tax Commissioner at 404-613-6100.

    If the owner of record is deceased, the estate generally needs legal authority to sell before a closing can fund. That runs through the Fulton County Probate Court at 136 Pryor Street SW. If a property already sold at a tax sale for more than the debt owed, the surplus belongs to the former owner — see Fulton County excess funds.

    Condition standards and code enforcement vary by jurisdiction across the county, and a house in East Point or College Park is handled differently than one in Roswell, Alpharetta, Johns Creek, South Fulton, or Chattahoochee Hills.

    Local Fulton County Resources

    If you decide to clean up or repair before selling, these metro Atlanta businesses and offices handle the work that comes up most often on a distressed property.

    Cleanouts and debris

    • JUSTJUNK Atlanta — full-property cleanouts, volume-based pricing, same or next-day service. 404-445-4025.
    • Bin There Dump That Atlanta — driveway-friendly roll-off dumpsters with walk-in doors, serving Fulton and surrounding counties. 404-882-1509.
    • Peachtree Waste — roll-off containers for residential and construction debris across metro Atlanta.
    • EZ Atlanta Junk Removal (89 Woodward Ave SE, Atlanta) — 678-841-8655, and SS Pro Junk Removal in southeast Atlanta — 770-203-8119.

    Estate contents

    • Peachtree Battle Estate Sales & Liquidations, 700 Miami Circle NE, Atlanta — 770-653-5247.
    • Professional Estate Sales, LLC, 1900 Century Place NE, Atlanta — 770-648-1919. Signature Estate Sales in Roswell — 404-737-6067.

    Inspections and closings

    • Property Inspectors of Atlanta — 770-912-0012. Paris Pressley Real Estate Inspector, 260 Peachtree Street NW — 404-755-9556. A pre-listing inspection is worth the few hundred dollars: it converts unknown risk into a number.
    • Campbell & Brannon — long-established metro Atlanta real estate closing attorneys, with offices in Buckhead and on Seminole Avenue. The Hudson Law Firm on Piedmont Road — 678-999-6030.

    Free and low-cost help

    • Atlanta Legal Aid Society — free civil legal help for income-qualifying residents of Fulton and four surrounding counties, including housing, foreclosure, and heirs’ property matters. Fulton office: 404-524-5811.

    Frequently Asked Questions

    How do I sell a house that needs lots of work without fixing anything?

    Sell it as-is, either on the MLS to a renovation buyer or directly to a cash buyer. A direct sale skips repairs, showings, appraisals, and financing contingencies entirely; you disclose the condition, the buyer prices for it, and closing typically runs 7 to 14 days. Request a no-obligation offer here.

    Will a bank finance a house that needs major repairs?

    Usually not on a standard loan. Lenders require the property to be safe, sound, and sanitary, so a missing roof, no heat, or unsafe wiring will stop the appraisal. Renovation loans exist, but they are slower, require contractor bids and draw schedules, and shrink the buyer pool considerably.

    How much less will I get selling as-is?

    It depends on the repair gap, but compare net proceeds rather than headline prices. Against a retail sale you save 5 to 6 percent commission, 1 to 3 percent seller closing costs, the entire repair budget plus contingency, and several months of taxes, insurance, and utilities. On a house needing significant work, those savings often close most of the gap.

    Do I have to disclose problems if I sell as-is?

    Yes. Georgia sellers must disclose known material defects. Selling as-is means you are not agreeing to make repairs; it does not relieve you of disclosure, and it does not prevent a buyer from inspecting during due diligence.

    Can I sell if I owe back taxes or there is a lien?

    Usually yes. Liens and back taxes are typically paid from the sale proceeds at closing rather than out of pocket, with releases recorded afterward. See can I sell property with a lien on it in Georgia and tax foreclosure in Georgia.

    What if I inherited the house and other heirs are involved?

    The estate needs legal authority to sell — Letters Testamentary or Letters of Administration from probate court — and every heir with an ownership interest generally has to sign. It is solvable, but identify it early. See how to sell inherited property.

    Should I clean the house out before selling?

    If you are listing on the MLS, yes — a full house shows badly and scares off financed buyers. If you are selling to a cash buyer, usually no. Most direct buyers will take the property with the contents in it, which saves you the cleanout cost and several weekends of work.

    How fast can a cash sale close?

    Most run 7 to 14 days once an offer is accepted, assuming clear title. Probate, unresolved liens, or missing heir signatures add time. Closings go through a licensed Georgia closing attorney or title company.

    What about a mobile home or a house on acreage?

    Both are common in south and west Fulton. We also buy trailer and mobile homes on land and vacant land in almost any condition.

    The Bottom Line

    A house that needs lots of work is not one decision, it is a comparison. Renovating and listing has the highest ceiling and the highest risk. Listing as-is splits the difference but depends on the house still being financeable. A direct cash sale trades price for certainty and speed. Auction and seller financing are situational.

    Run the arithmetic honestly, including the carrying costs and the contingency most sellers leave out, and the answer usually becomes obvious. What is rarely the answer is waiting. Distressed houses do not stabilize — the roof gets worse, the taxes compound, and the deadline gets closer.

    Get a straight answer on your property. Atlanta Land Buyers purchases houses and land across Fulton County as-is — repairs, contents, liens, and back taxes included — with no fees, no commissions, and closings that typically run 7 to 14 days. Call or text Gerald directly at (404) 913-7086.

    You can also request a no-obligation cash offer or contact us with a question about your situation. If selling is not the right move for you, we will tell you that too. Read more about our team.

    Atlanta, Georgia, 30307
  • What Is an Interpleader Action, and Why Did My Excess Funds Go to Court?

    What Is an Interpleader Action, and Why Did My Excess Funds Go to Court

    Short answer: an interpleader is what a county files when it is holding money it knows is not its own but cannot safely decide who should get it. Your excess funds went to court because someone else claimed them too — or because the county could not confirm you were the right person to pay.

    Getting a court summons about your own money is jarring. You lost a property at a tax sale, later learned there was money left over, and may have even filed a claim. Then, instead of a check, an envelope arrives from the Superior Court naming you as a defendant in a lawsuit you did not start.

    You are not in trouble. Nothing has been taken from you yet. But the clock is now running on a court deadline, and ignoring the envelope is the single most expensive mistake you can make.

    What an Interpleader Action Actually Is

    Interpleader is an old and sensible device. It solves one problem: someone holds money belonging to somebody else, and two or more people claim it — or the holder cannot tell who the rightful claimant is.

    The holder, called the stakeholder, has no interest in keeping the money. What it does have is exposure. If it pays the wrong person, it can be sued by the right one. So instead of guessing, the stakeholder deposits the funds with the court, names every possible claimant as a defendant, and asks the judge to sort it out. Once the money is in the court’s registry, the stakeholder is generally released from further liability.

    In Georgia this happens through the Civil Practice Act (O.C.G.A. § 9-11-22) and through longstanding equitable interpleader principles. For tax sale overages specifically, there is a statute directly on point: O.C.G.A. § 48-4-5(b) says the tax commissioner, tax collector, sheriff, or other officer holding excess funds may file an interpleader action in superior court when deemed necessary, and that the court shall distribute those funds to the intended parties, including the owner, as their interests appear and in the order of priority in which their interests exist.

    So the county is not being hostile. It is protecting itself. The practical effect on you, though, is real.

    Where Excess Funds Come From in the First Place

    Two different situations produce leftover money, and they are governed by different rules. People conflate them constantly.

    • Tax sale excess funds. A county sells a property to collect delinquent taxes. The winning bid exceeds the taxes, penalties, interest, and costs. That surplus does not belong to the county. It belongs to the former owner and to anyone holding a recorded interest, in order of priority.
    • Foreclosure surplus. A lender forecloses under a power of sale, the property brings more than the debt, and the foreclosing party is left holding the difference. That surplus belongs to junior lienholders and then to the former owner, and it can be interpleaded the same way.

    This article focuses mainly on the tax sale side, which is where Georgia’s statute is most specific. Our overview of Fulton County excess funds covers the claim process itself, and the Fulton County tax sale process explains how the auction produces the surplus in the first place.

    What the County Must Do Before It Ever Reaches Court

    Under O.C.G.A. § 48-4-5(a), the officer who sold the property must send written notice of the excess funds within 30 days of the tax sale, by first-class mail, to three groups: the record owner at the time of the sale, the record owner of each security deed affecting the property, and all other parties holding any recorded equity interest or claim at the time of the sale.

    That notice must describe the land, state the sale date, identify the tax sale purchaser, and give both the total sale price and the amount of excess funds being held.

    Two things follow. If you moved after the tax sale, that letter went to an address you no longer occupy — which is how many Georgians never learn the money exists. And the phrase “at the time of the tax sale” does enormous work: interests created after the sale generally do not count. A lien recorded the following year does not get in line.

    Why Your Funds Went to Court

    Counties do not interplead every file. It costs money and takes time. They do it when paying anyone directly would be risky. The usual triggers:

    1. Competing claims. The most common reason. A former owner, a mortgage holder, an HOA, a judgment creditor, and sometimes an heir all claim the same pot. Someone has to decide priority, and a tax commissioner is not a judge.
    2. Unclear ownership. The record owner died and the estate was never probated. The property was held by an LLC that has since been administratively dissolved. A deed in the chain is defective. The county cannot verify who is legally entitled.
    3. Third-party involvement. Many Georgia counties will not accept a claim from anyone but the claimant or a Georgia-licensed attorney. When an asset recovery firm or a power of attorney shows up, the county often routes the whole thing to court instead.
    4. Doubt about a claimant’s documentation. Missing identification, an unnotarized affidavit, a lien payoff that cannot be verified, or anything the office reads as suspect.
    5. Simple caution. The statute lets the officer file “when deemed necessary” — broad language. Some offices interplead more readily than others.

    What Happens to the Money Once It Is in Court

    The funds are deposited into the registry of the superior court, safe but frozen, until a judge orders distribution. Every potential claimant is served and has a deadline to answer and prove their interest. If nobody contests, distribution can be quick. If claims conflict, it becomes litigation.

    Here is the part that stings: under § 48-4-5(b), the cost of litigating the interpleader — including reasonable attorney’s fees — is paid out of the excess funds by order of the court. Not by the county. Not by the party who caused the dispute. Out of the pot. Court costs and fees typically come off the top before anything is distributed.

    So an interpleader is not a neutral event for you financially. It shrinks the fund. That is precisely why responding quickly and cleanly matters: the faster the dispute resolves, the less of your money is consumed proving who it belongs to.

    Who Actually Gets Paid, and in What Order

    Georgia courts distribute according to the interests that existed at the time of the tax sale, in their order of priority. In broad strokes:

    • Recorded liens and security deeds are paid according to their priority, generally oldest first, though tax and certain statutory liens can leapfrog.
    • A lienholder cannot claim more than what it is actually owed. Counties routinely require a written payoff good through the date of the claim, and the amount claimed cannot exceed the current lien value.
    • Whatever remains after valid liens goes to the former record owner — or, if that person has died, to the estate.

    Georgia case law has refined this repeatedly. Courts have held that a creditor whose security deed was fully satisfied no longer retains a priority lien and cannot claim the surplus ahead of the original owner’s estate, and earlier decisions granting automatic first priority to a creditor who redeemed the property have been overruled. These details are technical, which is why an interpleader is sometimes the honest answer rather than a bureaucratic dodge.

    What to Do If You Have Been Named

    1. Read the deadline and calendar it. You have a limited window to file an answer. Missing it can mean losing your claim entirely — not because your claim was weak, but because you did not respond.
    2. Do not assume being a defendant means you did something wrong. In an interpleader, every possible claimant is a defendant. It is the structure of the case, not an accusation.
    3. Gather proof of your interest as it existed at the tax sale date. Deed, security deed, lien, judgment, or letters of administration if you are acting for an estate.
    4. Get a Georgia attorney. This is one of the places where it genuinely pays. Fees may be recoverable from the fund, and an unrepresented claimant facing a represented lienholder rarely does well.
    5. Respond even if you think the money is small. Surpluses are often larger than people assume, particularly on land that sold well above the tax debt.

    The Five-Year Cliff

    If nobody claims the funds, they do not sit in the county forever. Under § 48-4-5(c), after five years from the tax sale date the officer must turn unclaimed excess funds over to the Georgia Department of Revenue, provided no claim or proceeding is pending. Once the state holds the money, the statute is strict: only a court order from an interpleader action filed in the county where the tax sale occurred will release it.

    In other words, waiting too long converts a paperwork problem into a lawsuit you have to file yourself. If you think a property you once owned in Fulton, DeKalb, or anywhere else in metro Atlanta went to tax sale, check now rather than later. Our guides on tax-delinquent property, tax foreclosure in Georgia, and how many years you can be behind on property taxes explain how properties reach that point.

    A Word About Asset Recovery Firms

    If you have excess funds sitting in a county, you have probably been contacted by someone offering to recover them for a percentage. Some are legitimate. Georgia law still puts real limits on them.

    • Fees are capped. Under O.C.G.A. § 44-12-224(a), a third party assisting with recovery of excess funds generally may not charge more than 10 percent of the amount recovered.
    • Early agreements are unenforceable. Private agreements between claimants and third parties who locate claimants or request payment on their behalf are generally unenforceable for 24 months following the date the funds were first placed in escrow.
    • Counties often will not deal with them at all. Multiple Georgia tax commissioners state plainly that they accept claims only from the claimant or from an attorney licensed in Georgia, and do not recognize applications from asset recovery firms or non-attorneys, even with a power of attorney.
    • Payment goes to you. Counties generally pay the owner directly rather than routing funds through a third party charging a fee.

    None of this means you should not get help. It means you can often file yourself, or hire a Georgia attorney directly, and keep considerably more of the money.

    Frequently Asked Questions

    Does an interpleader mean I lost my claim?

    No. It means the county declined to decide and handed the question to a judge. Your claim is intact. It now has to be proven on a court schedule.

    Who pays for the interpleader?

    The fund does. Georgia law directs that litigation costs and reasonable attorney’s fees be paid from the excess funds on the court’s order. That is the strongest practical argument for resolving it quickly.

    Can a lienholder take all of it?

    Only up to what is actually owed. A lienholder must document its payoff, and cannot claim more than the current value of the lien. Anything left after valid priority claims goes to the former owner or the estate.

    The owner died. Can the family claim the funds?

    Usually, but the estate generally needs legal authority first — letters testamentary or letters of administration. This is one of the most common reasons counties interplead. See our overview of probate real estate in Georgia and selling inherited property.

    I live out of state. Do I have to appear in Georgia?

    Much of it can be handled through counsel and by mail, though the case is filed in the Georgia county where the sale occurred. See how we work with out-of-state owners.

    The Bottom Line

    An interpleader is not a penalty. It is a county saying it is holding money it cannot safely distribute. But it converts a claim form into a lawsuit, runs on court deadlines instead of yours, and pays its own costs out of the very fund you are trying to recover.

    If you still own the property and taxes are the underlying problem, the better outcome is almost always to resolve it before a tax sale ever produces a surplus to fight over.

    If you own land or a house in metro Atlanta with back taxes attached, an inherited parcel nobody wants to deal with, or a property you would rather sell than defend, we buy as-is, with no fees or commissions, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us with a question about your situation. We will give you a straight answer either way — including when the answer is to go see a Georgia attorney instead.

    Related: what happens if you don’t pay property taxes · can I sell my house if it’s in foreclosure · Fulton County · DeKalb County · vacant land · about our team

  • What Is the 120-Day Foreclosure Rule in Georgia?

    120 Day foreclosure rule

    Short answer: for most home loans, your mortgage servicer cannot take the first legal step toward foreclosing until you are more than 120 days behind. It is a federal rule, not a Georgia one, and it is a starting line rather than a safety net.

    If you are behind on a mortgage in Atlanta and someone has told you about “the 120 day foreclosure rule,” you have been given a real piece of information — and, most likely, an incomplete one. It is widely misunderstood in ways that cost Georgia homeowners their houses. This article explains what it says, what it does not do, and how it interacts with Georgia’s unusually fast foreclosure process.

    Where the Rule Actually Comes From

    The 120-day rule is not in the Georgia Code. It is federal: 12 C.F.R. § 1024.41(f)(1), part of Regulation X, which implements the Real Estate Settlement Procedures Act and is enforced by the Consumer Financial Protection Bureau.

    The text is short. A servicer may not make the first notice or filing required by applicable law for any judicial or non-judicial foreclosure process unless the borrower’s mortgage loan obligation is more than 120 days delinquent. Regulators call this the pre-foreclosure review period. It exists so that homeowners have a real window to be evaluated for loss mitigation before the machinery starts.

    Two consequences follow. The rule applies in Georgia exactly as it does anywhere else, because it is national. And Georgia’s own statutes still control everything after day 120 — a process that moves fast.

    What “120 Days Delinquent” Really Means

    This is where homeowners most often miscount.

    • The clock starts at the oldest unpaid due date. You are delinquent from the day a payment covering principal, interest, and escrow was due and not received. Contractual grace periods do not restart it.
    • It is calendar days, not missed payments. In practice, more than 120 days usually lands after the fourth missed payment, but count days rather than payments.
    • Partial payments generally do not reset the clock. Sending something is better than sending nothing, but a partial payment does not move you back to current, and the delinquency date stays anchored to that oldest unpaid installment.
    • It is “more than” 120 days. Day 121, not day 120.

    The protection covers loans secured by a principal residence. It does not extend to reverse mortgages, and investment or vacation properties generally fall outside it. If the property is a rental, a second home, or vacant land, do not assume you have this window.

    What Counts as the “First Notice or Filing” in Georgia

    In judicial-foreclosure states the first filing is obvious: a complaint in court. Georgia is a non-judicial state. Most Georgia security deeds contain a power-of-sale clause letting the lender sell without a lawsuit or a judge.

    For non-judicial states, the regulation defines the first notice or filing as the earliest document that establishes, sets, or schedules a date for the foreclosure sale. In Georgia, that is effectively the notice and advertisement of the sale — the documents governed by O.C.G.A. § 44-14-162.2 and § 44-14-162. A demand letter, a breach letter, or a collection call is not the first notice or filing, even though those arrive earlier and feel far more alarming.

    This distinction matters practically. Homeowners receive a scary letter at 60 or 90 days, conclude foreclosure has started, and give up. It has not started. You are still in pre-foreclosure, you still hold clear title, and you can still sell. Our guide on whether you can sell your house if it’s in foreclosure walks through what changes at each stage.

    The Three Exceptions

    The rule is not absolute. Under § 1024.41(f)(1), a servicer may make the first notice or filing before day 121 if:

    1. The foreclosure is based on violation of a due-on-sale clause. Typically triggered when the property is transferred without lender consent — which is why quitclaiming a house into an LLC or to a relative while behind on payments can be a serious mistake.
    2. The servicer is joining the foreclosure action of a superior or subordinate lienholder. If a second mortgage holder, HOA, or tax lien holder moves first, your first-position lender can join.
    3. Regulation X does not apply to the loan at all. Reverse mortgages and non-principal-residence loans are the main gaps.

    Note also that the rules in this area have been amended over time and additional procedural safeguards can apply. Verify the current version with a Georgia attorney or a HUD-approved housing counselor rather than relying on any article, including this one.

    What the 120 Day Foreclosure Rule Does Not Do

    This section matters more than the rest. The rule is narrower than most people assume.

    • It does not stop interest, late fees, or escrow advances. Your reinstatement figure grows every day of those 120 days.
    • It does not protect your credit. The 30-, 60-, 90- and 120-day delinquencies are all reportable and can sit on your credit report for up to seven years.
    • It does not obligate the lender to modify your loan. It buys evaluation time, not an outcome.
    • It does not extend past day 120. On day 121 the protection is spent. There is no second window.
    • It does not touch property taxes, an HOA, or a second lienholder. Those run on separate tracks with their own remedies.
    • It does not require anyone to tell you the clock is running. You have to count.

    The rule is a floor under how fast a servicer may move. It is not a shield, and it is not a pause button.

    After Day 120: How Fast Georgia Actually Moves

    This is the part that catches people. Homeowners in judicial states get months of court process after the first filing. Georgia homeowners do not.

    Once the pre-foreclosure review period has passed, the lender must send notice of the initiation of proceedings to exercise the power of sale at least 30 days before the proposed sale date, by registered mail, certified mail, or statutory overnight delivery, return receipt requested (O.C.G.A. § 44-14-162.2). The sale must also be advertised in the county’s legal organ for four consecutive weeks. Foreclosure sales are conducted on the courthouse steps on the first Tuesday of the month, in the usual manner of sheriff’s sales.

    The practical arithmetic: roughly four months of federal protection, then about one month to auction. Homeowners who spend the first 120 days waiting for a court summons that never arrives find they have around 30 days left, not 30 weeks. Two Georgia specifics compound this:

    • No post-sale redemption. Georgia gives no statutory right to redeem a home after a non-judicial foreclosure sale. Once the gavel falls, it is over.
    • Deficiency judgments require confirmation. If the sale brings less than you owe, the lender may pursue the shortfall — but generally only if it reports the sale to the superior court within 30 days and the court confirms it (O.C.G.A. § 44-14-161). That confirmation requirement is a genuine protection, and worth having an attorney check.

    What Your Servicer Must Do Inside the 120 Days

    Regulation X does more than set a floor. It imposes affirmative duties during the same window, and most homeowners never learn about them because they stopped opening the mail.

    1. Live contact by day 36. The servicer must make good-faith efforts to reach you by phone or in person within 36 days of the missed payment (12 C.F.R. § 1024.39).
    2. Written loss mitigation notice by day 45. Within 45 days the servicer must describe available options in writing and assign personnel to your file. That letter is in your mail somewhere. Find it.
    3. Evaluate a complete application before referring to foreclosure. If you submit a complete loss mitigation application before the first notice or filing, the servicer generally cannot proceed until it has evaluated you — the prohibition commonly called the ban on dual tracking (§ 1024.41(f)(2) and (g)).
    4. Honor the 37-day rule after referral. Even after foreclosure has been initiated, a complete application received more than 37 days before a scheduled sale generally blocks the sale while it is evaluated.
    5. Allow an appeal. If your complete application arrived at least 90 days before a scheduled sale or before the first notice or filing, you generally have 14 days to appeal a denied loan modification.

    Notice the pattern. Nearly every one of these protections is triggered by you submitting something. The 120-day rule gives you time; the application is what converts time into leverage.

    How to Actually Use the Window

    Days 1–45

    • Call the loss mitigation department directly, not general customer service.
    • Request the reinstatement amount and a written payoff statement. The payoff includes interest, fees, and escrow advances, and is usually higher than people expect.
    • Ask which programs your specific loan type qualifies for — FHA, VA, USDA, Fannie Mae and Freddie Mac each have their own.
    • Contact a HUD-approved housing counselor. It costs nothing.

    Days 45–90

    • Submit a complete loss mitigation application and get written confirmation that it is complete. Incomplete applications do not carry the same protection.
    • Run your equity math: market value, minus payoff, minus 7% to 9% for closing costs if listing traditionally, minus any second mortgage, HELOC, or lien.
    • Decide honestly whether the payment becomes affordable again within 90 days. If not, start the sale conversation now rather than at day 110.

    Days 90–120

    • If a modification is in progress, log every call with date, time, and representative name.
    • If selling is the answer, list it or get a cash offer while title is still clean. A house that needs work can be sold as-is — see I want to sell my ugly house or request an offer here.
    • Do not let day 121 arrive with no plan and no application on file.

    Property Taxes Run on Their Own Clock

    Nothing in the 120-day rule slows a county tax collector. Georgia counties issue a Fi.Fa. and can proceed to a tax sale regardless of what your mortgage servicer is doing, and tax sales also happen on the first Tuesday of the month. If you own vacant land, an inherited lot, or a second parcel alongside the house, check the tax status on each. Our guides on tax foreclosure in Georgia, what happens if you don’t pay property taxes, how many years you can be behind, and the Fulton County tax sale process cover that separate timeline. If a property already sold for more than the debt owed, the surplus belongs to the former owner — see Fulton County excess funds.

    Frequently Asked Questions

    Is the 120 day foreclosure rule a Georgia law?

    No. It is federal — 12 C.F.R. § 1024.41(f)(1) under Regulation X and RESPA — and it applies to Georgia homeowners along with everyone else. Georgia law governs what happens after the 120 days, and Georgia’s non-judicial process is faster than most states’.

    Can my lender foreclose at 90 days late in Georgia?

    Generally no. For most principal-residence mortgages the servicer cannot make the first notice or filing until you are more than 120 days delinquent, with narrow exceptions for due-on-sale violations and joining another lienholder’s action. A demand or breach letter at 90 days is not a foreclosure filing.

    Does the clock reset if I make a partial payment?

    Generally not. Delinquency is measured from the oldest unpaid due date, and a partial payment does not bring the loan current. Ask your servicer in writing how your delinquency date is being calculated before you assume you have bought more time.

    Can I sell my house during the 120 days?

    Yes, and it is usually the best available outcome if you have equity. You remain the legal owner until a foreclosure sale is completed, and the mortgage payoff is handled at closing from the sale proceeds. See selling a house in foreclosure for how title companies handle liens and payoffs.

    What if the property was inherited and I am behind on the note?

    More common than people assume, especially when an estate was never properly probated. The estate generally needs legal authority to sell before closing. See selling inherited property, our overview of probate real estate in Georgia, and how we work with out-of-state owners.

    The Bottom Line

    The 120 day foreclosure rule gives Georgia homeowners about four months before a servicer can take the first legal step. That is real and worth knowing. But it is a floor on the lender’s speed, not a shield for you, and it runs whether or not you use it.

    The homeowners who come through this with credit and equity intact are rarely the ones with the most savings. They are the ones who counted the days and submitted something while the window was still open.

    If selling is on the table — a house that needs work, a rental you are tired of carrying, an inherited parcel with taxes attached, or land you no longer want — we buy property across metro Atlanta as-is, with no fees or commissions, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us about your situation. We will give you a straight answer either way — including when the answer is that you should go submit a loss mitigation application instead of selling.

    Related: about our team · tax-delinquent property · Fulton County · DeKalb County · vacant land

    Ready To Sell Your Land? Start Here…

    We are direct land buyers. There are no commissions or fees and no obligation whatsoever. Start below by sharing where your property is and where we can send your offer…

    "*" indicates required fields

    Name*
    This field is for validation purposes and should be left unchanged.

  • How Long Do You Have to Pay Delinquent Property Taxes in DeKalb County, Georgia?

    How Long Do You Have to Pay Delinquent Property Taxes

    If you have fallen behind on your DeKalb County property taxes, the question that keeps you up at night is a simple one: how much time do I actually have before I lose the house?

    There is no single deadline. There are three separate clocks, they run one after another, and each is more expensive than the last. Miss the first and you get a lien. Miss the second and your property goes to auction on the courthouse steps in Decatur. Miss the third and it is gone permanently. Here is how the DeKalb timeline works, what each stage costs, and what you can still do at each point.

    The Short Answer: Three Deadlines, Not One

    • December 31. DeKalb subjects any account with an outstanding balance after December 31 to a tax lien. This is your cleanest, cheapest window.
    • Roughly 4 to 12 months after the lien. Once a FiFa is recorded, the county can levy and advertise the property for a tax sale held the first Tuesday of the month in front of the DeKalb County Courthouse.
    • 12 months after the sale. If the property sells, you have one year to redeem it — by paying the buyer’s bid plus a 20% premium.
    Quick answer: In DeKalb County, taxes are delinquent the day after the installment due date, and any balance still unpaid after December 31 is subject to a tax lien. From there the county can move to a tax sale within months. If the property is sold, you have 12 more months to redeem it by paying the purchaser’s bid plus a 20% premium and costs.

    The DeKalb County Property Tax Calendar

    DeKalb mails tax bills in mid-August and splits the year into two installments: the first due September 30, the second in mid-November (November 16 for the current cycle). Paying the whole bill at once must be done by September 30 to avoid a late charge. Bills for City of Atlanta properties inside DeKalb are mailed separately, on a later schedule.

    Two things trip people up every year.

    • Not receiving a bill does not extend the deadline. If it never arrived, you are still responsible. Look your account up and pay through the county portal.
    • Mortgage servicing changes. When a loan is sold or paid off, the escrow account that quietly handled your taxes can stop doing so — one of the most common ways an owner ends up delinquent without knowing it. After any change, confirm your account shows a zero balance.

    You can look up and pay a DeKalb bill any time at the county’s online property tax portal.

    What It Costs You to Wait

    DeKalb accepts partial payments, and you can make as many as you need. But penalties and interest keep accruing on whatever remains, and they compound the delay:

    • Interest accrues on the unpaid balance at the bank prime rate plus 3% annually, charged monthly (O.C.G.A. § 48-2-40).
    • A 5% penalty attaches 120 days after the due date, and again every 120 days thereafter, up to a maximum of 20% of the original principal (O.C.G.A. § 48-2-44).
    • Once collection actions begin, title research, advertising, levy, and sheriff’s costs are added to the balance.

    A $2,400 bill does not stay $2,400. Between penalties, interest, and administrative costs, a balance can grow by a third or more before the property ever reaches auction.

    Clock One: December 31, Before a Lien Attaches

    This is the deadline most DeKalb homeowners never hear about, and it is the one that matters most. The Tax Commissioner’s office states plainly that accounts with an outstanding balance after December 31 are subject to a lien.

    That lien is a FiFa — short for fieri facias, also called a tax execution. It is a recorded encumbrance authorizing the Tax Commissioner or the Sheriff to take whatever action state law allows to collect. It is also, in the county’s own words, the first step toward taking your property to tax sale.

    Although the Tax Commissioner’s office does not report to credit bureaus, a recorded tax lien can still surface on your credit reports. It also clouds your title, so you cannot cleanly sell or refinance until it is satisfied.

    Paying the taxes plus fees, penalties, and interest gets the lien marked satisfied. If you can clear the balance before December 31, do it — everything after costs more and gives you fewer options. Details are on the DeKalb County Tax Commissioner’s delinquent tax page.

    Clock Two: From FiFa to the Courthouse Steps

    Once a lien is recorded there is no fixed countdown to auction. DeKalb schedules sales periodically rather than monthly, and recent lists have included delinquencies stretching back many years. That cuts both ways: you may have longer than you fear, or far less. When a sale is scheduled, the process runs like this:

    • The property is levied under the FiFa and added to the sale list.
    • The sale is advertised for four consecutive weeks in the county legal organ, and notice is sent to the owner of record.
    • The auction is held on the first Tuesday of the month in front of the DeKalb County Courthouse in Decatur. Legal sale hours run 9 a.m. to 4 p.m.
    • Opening bids include all prior year taxes due, plus accrued costs.

    One detail catches people badly. Once your property has been scheduled for tax sale, DeKalb will only accept cash, a bank-issued cashier’s check, or a bank wire transfer. Personal checks, business checks, money orders, and debit or credit cards are all refused at that stage. If you plan to pay at the last minute you need certified funds in hand, not a card.

    You can check whether a parcel appears on the county’s tax sale listing, and the office publishes a report of all properties with taxes due within the last seven years.

    Clock Three: The 12-Month Right of Redemption

    If the property sells, you are not finished — but the terms get harsh. Georgia gives the former owner, creditors, and anyone else with an interest in the property 12 months from the sale date to redeem it.

    Redemption is not repaying your back taxes. Under O.C.G.A. § 48-4-42 you must pay the purchaser the full bid amount, any taxes and special assessments they have paid since the sale, plus a 20% premium for the first year and 10% for each year or fraction of a year after that.

    Do the arithmetic before counting on this. A homeowner who could not pay a $5,000 bill is now asked for the purchase price plus 20% at once. The right is real, but it rescues far fewer homes than owners expect.

    After 12 months the purchaser can serve a barment notice under O.C.G.A. § 48-4-45 to foreclose your right of redemption permanently, and title ripens automatically four years after the tax deed is recorded. During the redemption year the purchaser cannot take possession, collect rent, or make improvements.

    Excess Funds: Money You May Be Owed After a Sale

    This is the part almost nobody knows about, and it costs DeKalb families real money every year. When a tax sale brings in more than the taxes, costs, and fees owed, the surplus is called excess funds, and the Tax Commissioner holds it until an entitled party claims it.

    A home worth $250,000 sold over a $9,000 tax debt can generate tens of thousands in excess funds. That money belongs to the former owner and other interested parties, not the county or the buyer — but it does not arrive automatically. You have to claim it.

    Claims go to the Delinquent Collections Claims division, are evaluated case by case on your documentation, and must be filed by the entitled party or their Georgia-licensed attorney. Powers of attorney are not accepted. If competing claims arise the office may interplead the funds into Superior Court, after which it cannot give updates.

    If a property you owned went to tax sale in DeKalb, check the county’s published excess funds list and download the excess funds claim form. Be wary of anyone who contacts you offering to recover the money for a large cut — you can file yourself.

    What to Do If You Are Behind on DeKalb County Property Taxes

    • Start making partial payments now. DeKalb accepts them, and every dollar paid reduces the base that penalties and interest compound on.
    • Confirm your exemptions. Missing homestead, senior, or disability exemptions inflate every future bill. Check the DeKalb exemptions page and, if you are 62 or older, the county’s dedicated seniors resources.
    • Appeal the assessment if the value is wrong. Assessment notices go out in late May and you have 45 days to appeal through the DeKalb Property Appraisal Department. An exemption cannot fix an inflated valuation.
    • Go in person before a sale is scheduled. Staff have more room to work with you early than late. See DeKalb tax office locations or call 404-298-4000.
    • Fix title problems immediately. If the home is still deeded to a deceased parent, you cannot claim homestead and may not even receive the notices. See our guide to heirs’ property and probate in Georgia.
    • Know what you qualify for at 65. Senior exemptions can cut a DeKalb bill substantially. Read do I have to pay property taxes after age 65 in Georgia.

    If the balance is beyond reach, consider selling before the auction. A tax sale clears for little more than the back taxes, wiping out equity a normal sale would preserve. Selling ahead of the date, even at a discount, almost always leaves the family with more than the courthouse steps will. We buy DeKalb County houses in this situation, including homes that need repairs and homes with liens attached. Request a no-obligation cash offer or get in touch to talk through the timeline.

    Frequently Asked Questions

    How long do you have to pay delinquent property taxes in DeKalb County?

    There is no single deadline. Taxes are delinquent the day after the installment due date, and any balance still outstanding after December 31 is subject to a tax lien. From there DeKalb can schedule a tax sale within months. If the property sells, you have 12 more months to redeem it.

    When are DeKalb County property taxes due?

    Bills are mailed in mid-August and payable in two installments, the first due September 30 and the second in mid-November. Paying the full amount at once must be done by September 30 to avoid a late charge. City of Atlanta properties in DeKalb are billed separately on a later schedule.

    What is a FiFa, and what does it do to me?

    A FiFa (fieri facias) is a recorded tax lien, also called a tax execution. It authorizes the Tax Commissioner or Sheriff to collect the debt and is the first step toward a tax sale. It clouds your title and can appear on your credit reports, even though the Tax Commissioner’s office does not report to credit bureaus.

    Where and when are DeKalb County tax sales held?

    Tax sales are conducted in front of the DeKalb County Courthouse in Decatur on the first Tuesday of the month, with legal sale hours from 9 a.m. to 4 p.m. Sales are held periodically rather than every month, and upcoming listings are posted on the county website.

    How much does it cost to redeem my property after a DeKalb tax sale?

    You must pay the purchaser’s full bid, any taxes and special assessments they have paid since the sale, plus a 20% premium for the first year and 10% for each year after. That is on top of everything already owed, and it must generally be paid at once.

    What are excess funds and how do I claim them?

    When a tax sale raises more than the taxes, costs, and fees owed, the surplus is held by the Tax Commissioner until claimed. Claims go to Delinquent Collections Claims and must be filed by the entitled party or their Georgia-licensed attorney; powers of attorney are not accepted.

    The Bottom Line

    The time you have to pay delinquent property taxes in DeKalb County is longer than panicked homeowners assume and shorter than complacent ones do. December 31 is the deadline that protects your title. Everything after is damage control, and each stage costs more than the last.

    Act while you still hold the cheapest options. Call the Tax Commissioner, verify your exemptions, appeal the value if it is wrong, and if the number is out of reach, sell before the auction rather than after. We can help you understand where you stand.

    Atlanta, Georgia, 30307
  • Do I Have to Pay Property Taxes After Age 65 in Georgia?

    Do I Have to Pay Property Taxes After Age 65

    It is one of the most common questions older homeowners across metro Atlanta ask, and the rumor never quite dies: “Once you turn 65 in Georgia, you stop paying property taxes.” If you have heard it at church or from a neighbor who swears it is true, you are not alone. It is not right — and believing it has cost Georgia families their homes.

    Here is the accurate version: which exemptions you can claim at 62, 65, and 70, what they are worth, how to apply, and what happens if a senior on a fixed income falls behind and the taxes go delinquent.

    The Short Answer: Yes, You Still Owe Property Taxes After 65

    Turning 65 in Georgia does not eliminate your property tax bill. What 65 does is unlock a stack of homestead exemptions that can cut your bill substantially — and in a handful of counties, wipe out its largest piece, the school tax portion, entirely.

    Three things matter more than your age alone:

    • Your county. State exemptions are modest; county exemptions can be enormous. Identical homes on opposite sides of a county line can have very different bills.
    • Your income, as Georgia calculates it. The income tests look impossibly strict until you learn what Georgia leaves out.
    • Whether you actually applied. Nothing is automatic. No county adds an exemption because it noticed your birthday.
    Quick answer: No, you do not stop paying property taxes at 65 in Georgia. You become eligible for additional homestead exemptions — $4,000 off county taxes at 65, $10,000 off school taxes at 62, and county programs that in places like Cobb and Gwinnett can eliminate school taxes entirely. You must apply, usually by April 1.

    How Georgia Property Taxes Are Calculated

    Georgia taxes property at 40% of fair market value. A home appraised at $300,000 has an assessed value of $120,000, and your millage rate applies to that minus any exemptions. This is why a “$2,000 exemption” underwhelms — it comes off assessed value, not market value.

    It also explains why county school exemptions matter. Your bill is several taxes stacked: county operations, school district taxes (usually the largest share), city taxes, and bond, fire, and special assessments. An exemption touching only county operations shaves a little off. One that removes school taxes can halve the bill.

    The Statewide Exemptions Every Georgia County Must Offer

    These come from state law, so they exist in all 159 counties. They are the floor, not the ceiling.

    Standard Homestead Exemption — $2,000, any age

    Every homeowner who owns and occupies the property as their legal residence on January 1 gets $2,000 off assessed value for county and school taxes (O.C.G.A. § 48-5-44). Everything else stacks on this.

    Age 65 — $4,000 County Exemption

    At 65 you may claim an additional $4,000 exemption from all county ad valorem taxes if your and your spouse’s income did not exceed $10,000 the prior year (O.C.G.A. § 48-5-47). Read the income section below before dismissing that figure.

    Age 62 — $10,000 School Exemption

    At 62 you may claim up to $10,000 of assessed value off school taxes, including school bond debt, under the same income test (O.C.G.A. § 48-5-52). This one starts three years before the county exemption — a detail plenty of 63-year-olds miss.

    Age 62 — Floating Inflation-Proof Exemption

    Homeowners 62 and older can claim a floating county exemption shielding them from increases in appraised value (O.C.G.A. § 48-5-47.1). It applies once appraised value has risen more than $10,000, the income limit is $30,000 including everyone in the household, and it replaces rather than stacks with other county homestead exemptions.

    The $10,000 Income Test Is Not What It Looks Like

    This is the most misunderstood rule in Georgia senior property tax law. Georgia excludes Social Security entirely, and excludes retirement, pension, and disability income up to the maximum Social Security benefit — $96,432 for 2025, per the Georgia Department of Revenue. A couple drawing Social Security plus a pension may pass comfortably. Do not disqualify yourself — let the county run the numbers.

    Where the Real Savings Live: County School Tax Exemptions

    If you take one thing from this article, take this: state exemptions are small, and county exemptions are where seniors save thousands. There is no statewide rule, and neighboring counties differ dramatically.

    CountySenior school tax reliefIncome limit
    Cobb100% exemption from county school taxes at age 62None
    GwinnettL5A — 100% exemption from school district taxes at 65$124,648 GA taxable income (2026)
    FultonNew for 2026: 25% off school assessment at 65, 50% at 70; separate income-based exemption up to $54,000None for the percentage tiers (5-of-6-year residency required)
    CherokeeSchool tax exemption at 62 up to $446,700 fair market valueNone
    ForsythFull school tax exemption at 65Varies — confirm with county
    DeKalbTiered exemptions from 62, scaled by age and incomeVaries by tier
    Most rural countiesState-mandated minimums only$10,000 (with exclusions)

    Amounts change with local legislation nearly every session. Confirm current figures with your county tax commissioner.

    One statewide wrinkle: House Bill 581 created a floating homestead exemption capping taxable value growth at inflation from 2025, but local governments could opt out and most large metro counties did. If you are weighing whether a property’s tax burden still makes sense, start with what your Atlanta-area home is actually worth today.

    What This Is Worth in Real Dollars

    Take a retired couple in a $325,000 home. Assessed at 40%, that is $130,000; at 30 mills the bill runs about $3,900, of which perhaps $1,900 is school tax. The three state exemptions together save roughly $250 a year. A county exemption that removes school taxes saves closer to $2,150 a year — more than half the bill, every year they own the home. That gap is why this article keeps pointing you to your county rather than the state.

    What Turning 65 Does Not Do

    • It does not erase the whole bill. County, city, bond, fire and sanitation charges survive nearly every senior exemption.
    • It is not automatic. You must file. No county applies an exemption when you hit the age threshold.
    • It does not follow you. Move and you reapply. Some county exemptions require years of prior residency.
    • It does not cover rentals, second homes, or vacant land. Homestead exemptions apply only to your primary residence.
    • It does not erase what you already owe. An exemption granted now does nothing about a balance already under lien.

    How to Apply

    • Confirm January 1 ownership and occupancy. You must have owned and occupied the home as your legal residence, and met the age threshold, by January 1.
    • File with the county. Applications go to your county tax commissioner or tax assessor, not the state.
    • Watch April 1. The standard cutoff for the current tax year. Georgia also allows filing through the end of your 45-day assessment appeal window.
    • Bring documentation. Georgia driver’s license showing the property address, proof of age, and prior-year income records.
    • Ask about every layer. County, city, and school exemptions can each require separate filings. Ask what you qualify for rather than assuming the clerk volunteers it.

    Delinquent Property Taxes in Georgia: What Happens If You Fall Behind

    Exemptions reduce the bill; they do not eliminate it, and here the myth turns dangerous. Homeowners who believe 65 ended their obligation sometimes stop opening the envelopes. In Georgia that is a fast road to losing the house.

    Seniors are unusually exposed. Once a mortgage is paid off, the escrow account that handled taxes for thirty years disappears and the bill arrives directly for the first time. Add a fixed income, a health event, or a home still deeded to a deceased parent, and arrears build fast.

    The penalties start quickly

    • Interest accrues on the unpaid balance at the prime rate plus 3% annually, charged monthly.
    • A 5% penalty is added 120 days after the due date, and again every 120 days, up to 20% of the original principal.
    • The tax commissioner issues a FiFa (writ of fieri facias), a recorded lien against the property and the owner of record.

    From lien to auction is measured in months

    Once a FiFa issues, the property can be levied and sold. The county advertises for four consecutive weeks and sends notice before the auction, held the first Tuesday of the month at the courthouse. A property can move from delinquency to sheriff’s sale in roughly 120 to 180 days, and sales usually clear for little more than the back taxes — so a home with real equity can transfer for a fraction of its value. Understanding how the Georgia tax sale process works is urgent.

    The 12-month right of redemption, and its price

    Georgia gives the owner, creditors, and anyone with an interest 12 months from the sale to redeem — but redemption is not simply repaying back taxes. Under O.C.G.A. § 48-4-42 you must pay the purchaser’s full bid, any taxes they have paid since, plus a 20% premium for the first year and 10% for each year after. After 12 months the purchaser can serve a barment notice under O.C.G.A. § 48-4-45 to foreclose the right permanently. The right is real, but the arithmetic defeats most homeowners — particularly a retiree who could not pay a $4,000 bill and now faces that plus 20% at once.

    If you are behind, act before the sale

    • File every exemption you qualify for now. It will not fix past years, but it lowers what accrues next year.
    • Appeal the assessment. Exemptions cannot fix an inflated valuation, and seniors in appreciating neighborhoods are often assessed above what the home would sell for.
    • Call the tax commissioner about a payment arrangement. Many counties work with a homeowner who calls before a FiFa issues. Almost none will after the auction.
    • Ask about deferrals and free legal help. Georgia’s Elderly Legal Assistance Program serves seniors facing property tax and housing problems statewide.
    • Resolve title problems. If the home is still in a deceased parent’s name you cannot claim homestead. See our guide to heirs’ property and probate in Georgia.
    • Consider selling before the auction. A tax sale wipes out equity a normal sale would preserve. Selling ahead of the date, even at a discount, usually leaves the family with far more. We buy houses in this situation, including homes that need repairs and homes with liens against them.

    If a sale date is set, time matters more than price. Reach out and we can walk through your options, including a no-obligation cash offer on your Atlanta-area property.

    Frequently Asked Questions

    Do I have to pay property taxes after age 65 in Georgia?

    Yes. Turning 65 does not exempt you from Georgia property taxes. It qualifies you for additional homestead exemptions, including $4,000 off county taxes. In several counties senior exemptions eliminate the school tax portion, but county, city, bond, and fire district taxes generally remain.

    What is the income limit for Georgia’s senior property tax exemption?

    The state exemptions use a $10,000 limit, but Social Security is excluded outright and retirement, pension, and disability income is excluded up to $96,432 for 2025. Many retirees who assume they earn too much actually qualify. Counties set their own limits; Gwinnett’s is $124,648 for 2026.

    Which Georgia counties eliminate school taxes for seniors?

    Cobb exempts homeowners 62 and older from all county school taxes with no income limit. Gwinnett’s L5A removes school district taxes at 65 under the income cap. Forsyth and Cherokee offer substantial exemptions too. Rules change often, so verify with your county.

    What happens if a senior doesn’t pay property taxes in Georgia?

    Interest accrues, a 5% penalty is added at 120 days and repeats every 120 days up to 20% of principal, and the tax commissioner issues a FiFa lien. The property can then be levied, advertised for four weeks, and sold at sheriff’s sale, often within 120 to 180 days.

    How long do I have to get my property back after a Georgia tax sale?

    Twelve months from the sale date. You must pay the purchaser’s bid, any taxes they have paid since, plus a 20% premium for the first year and 10% each year after. Then the purchaser can foreclose your right of redemption with a barment notice.

    Can I claim a senior exemption on a house I inherited but never retitled?

    Generally no. Homestead exemptions require ownership of record as of January 1. If the deed is still in a deceased relative’s name you must resolve title through probate or an heirs’ property proceeding first. This is one of the most common reasons Georgia families lose inherited homes to tax sales.

    The Bottom Line

    You do not stop paying property taxes at 65 in Georgia, but you may be paying far more than the law requires. The exemptions are real, they stack, the income tests are more forgiving than they look, and in some counties they erase the largest line on your bill. What they will not do is apply themselves. Call your county tax commissioner and file before April 1.

    And if the taxes have already gotten away from you, do not wait for the auction notice. Georgia’s timeline is short and its redemption terms punishing, and there are almost always more options before the sale than after it. Get in touch and we will help you understand where you stand.

    Atlanta, Georgia, 30307
  • What Happens If You Are 2 Months Late on Your Mortgage — The Shame Nobody Addresses

    sell your house in Atlanta

    Two missed mortgage payments is not a headline. It is quieter than that: a phone buzzing with a number you recognize, and the small decision you make not to answer it.

    If you are 60 days past due on your home loan, you already know the financial facts are bad. What almost nobody writes about is the other half — the part that keeps homeowners frozen until their options have narrowed to almost nothing. This article covers both: what actually happens at two months of mortgage delinquency, what your loan servicer is required to do, how the Georgia foreclosure process works, and why the embarrassment you are feeling is the most expensive thing in your situation.

    The Shame Is the Part That Costs You Money

    Missing a mortgage payment carries a weight that missing a credit card payment does not. A house is where your kids sleep. So when the payment slips, most people do the same three things: stop opening the envelopes, stop answering the servicer’s calls, and tell nobody.

    Here is why that matters more than any late fee. Nearly every option available to a homeowner behind on payments — a repayment plan, a forbearance agreement, a loan modification, a short sale, a pre-foreclosure sale with equity intact — requires you to talk to someone. The homeowner who calls at 60 days has a different menu than the one who calls at 150 days. Silence does not pause the clock; it spends your remaining time without buying you anything.

    Loss mitigation departments are not staffed by people who are shocked to hear from you. Job loss, divorce, medical bills, a slow year in business, an inherited property with a note still on it — none of it is unusual, and none of it makes you a bad person. The only unusual homeowner is the one who calls early.

    What “Two Months Late” Means on the Servicer’s Screen

    Mortgage delinquency is tracked in 30-day buckets, and the bucket determines what happens next.

    • Grace period: roughly 15 days after the due date before a late fee applies. Late, but not yet reported.
    • 30 days past due: reportable to the credit bureaus. Late fees assessed, collection calls begin.
    • 60 days past due: two payments outstanding. The file typically moves from routine collections to loss mitigation, and the letters change tone.
    • 90 days past due: a demand or breach letter usually appears, giving you a deadline to cure the default in full.
    • 120 days past due: the federal threshold — for most residential mortgages, the earliest a servicer may take the first step toward foreclosure.

    At two months you are not in foreclosure. You are in pre-foreclosure, where you still hold clear title and still have leverage. That distinction is the whole ballgame, and our guide on whether you can sell your house if it’s in foreclosure walks through what each stage does to your options.

    The Financial Damage at 60 Days

    Each missed payment typically carries a late charge of roughly 3% to 6% of the principal-and-interest portion, and those charges do not go away on their own. More importantly, the amount needed to reinstate the loan is not simply two payments. The reinstatement figure includes both missed payments, accrued interest, late fees, and costs the servicer has already incurred — property inspection fees, for example, which many servicers order between 45 and 60 days. Ask for that number in writing. Homeowners routinely guess it, and routinely guess low.

    If your loan escrows for property taxes and homeowners insurance, missed payments mean the escrow account is not being funded. The servicer will usually advance those payments to protect its collateral, then add the shortage to what you owe. That is how a two-month gap quietly becomes a three-month gap on paper.

    On credit, a 60-day late is materially worse than a 30-day late, because scoring models weight both recency and severity, and a mortgage carries more weight than most accounts. Expect a meaningful drop, and expect it to sit on your report for up to seven years. Keep it in proportion, though: a completed foreclosure, a short sale, and a deed in lieu all fall further down the same scale. Acting now is partly about protecting the credit you have left.

    What Your Servicer Must Do — and What It Cannot Do Yet

    Federal servicing rules give you protections most homeowners never learn about, largely because they stopped opening the mail before the relevant letter arrived.

    1. Live contact by day 36. Your servicer must make good-faith efforts to reach you within 36 days of a missed payment.
    2. Written loss mitigation notice by day 45. The servicer must describe available options in writing and assign staff to your file. At two months behind, that letter has almost certainly been sent. Find it.
    3. No first foreclosure filing before day 120. For most residential mortgages, the servicer cannot make the first notice or filing required for foreclosure until you are more than 120 days delinquent.
    4. A complete application slows things down. Submit a complete loss mitigation package more than 37 days before a scheduled sale and the servicer generally cannot proceed to sale while evaluating it. Confirm in writing that the file is complete.

    Two months is not a long runway, but it is a real one — enough time to negotiate a modification, list and sell, or close a cash sale.

    How Foreclosure Actually Works in Georgia

    Georgia is a non-judicial foreclosure state. Most security deeds contain a power-of-sale clause, so the lender does not need a lawsuit or a judge’s permission to sell your home. Once the federal 120-day period passes, the timeline compresses: the lender must send notice of the initiation of foreclosure proceedings at least 30 days before the proposed sale date, by certified or registered mail or statutory overnight delivery, and must advertise the sale in the county legal organ for four consecutive weeks. Sales are held on the courthouse steps on the first Tuesday of the month.

    Three consequences follow:

    • From first notice to auction can be roughly a month. Homeowners waiting for a court date that never comes get caught.
    • Georgia provides no statutory right of redemption after a non-judicial sale. Once the gavel falls, the house is gone.
    • If the sale brings less than you owe, the lender may pursue a deficiency judgment — but generally only if it files to confirm the sale in superior court within 30 days.

    Notice periods do change, so verify current requirements with a Georgia attorney or a HUD-approved housing counselor rather than any article, including this one. For the parallel process on the tax side, see tax foreclosure in Georgia and the Fulton County tax sale process.

    The Options Still Open to You at 60 Days

    If you intend to keep the home

    • Reinstatement — pay the full past-due amount and the loan returns to current.
    • Repayment plan — arrears spread over several months on top of the regular payment. Best when the hardship has passed.
    • Forbearance — payments reduced or paused temporarily. Understand the exit terms; some end in a lump sum.
    • Loan modification — a permanent change to rate, term, or structure. The workhorse fix for long-term affordability problems.
    • Partial claim or deferral — FHA, VA, USDA, Fannie Mae and Freddie Mac loans each have programs that move arrears to the back of the loan. Ask which applies to yours.

    If keeping the home is not realistic

    • Sell with equity — if the home is worth more than the payoff, selling before foreclosure protects both your equity and your credit. For most homeowners two months behind, this is the best available outcome.
    • Short sale — the lender approves a sale for less than the balance. Slower, but far better than an auction.
    • Deed in lieu of foreclosure — voluntary transfer of title to the lender. Usually a last resort.
    • Cash sale to a direct buyer — fastest and most certain, at a price below full retail. Reasonable when a sale date is close or the property needs work.

    If repairs are part of the problem, see I want to sell my ugly house for how as-is purchases work in metro Atlanta, or request an offer here.

    Don’t Let Property Taxes Become the Second Problem

    Homeowners behind on a mortgage are often behind on property taxes too, and the two run on separate tracks. A county Fi.Fa. and tax sale can move against a parcel regardless of what your servicer is doing. If you own vacant land, an inherited lot, or a second parcel, check each one. Our guides on what happens if you don’t pay property taxes and how many years you can be behind cover the timeline. And if a property already sold for more than the debt owed, the surplus belongs to the former owner — see Fulton County excess funds.

    How to Tell Whether You Have Equity

    Everything above hinges on one number. Request a written payoff statement — not your balance, the payoff, which includes interest, late fees, escrow advances, and legal costs already incurred. Then get a realistic value from recent comparable sales rather than an automated online estimate. Subtract the payoff, plus 7% to 9% for closing costs and commissions if you plan to list traditionally, plus any second mortgage, HELOC, tax lien, or contractor lien recorded against the property.

    If the result is positive, do not let this reach an auction; equity does not survive a foreclosure sale in any reliable way. If it is negative, you are looking at a short sale, a modification, or a deed in lieu — all of which take time to arrange, which is the argument for starting now rather than in month four.

    Sorting Real Help From Predatory Offers

    Once the delinquency shows up in public records, the calls multiply. Treat these as red flags: an upfront fee to “stop” your foreclosure, advice to stop communicating with your servicer, a request to sign over the deed with a promise you can rent and buy back later, or pressure to sign documents with blanks in them.

    Legitimate help is free. HUD-approved housing counseling agencies provide foreclosure counseling at no cost, and Atlanta Legal Aid and the State Bar of Georgia can point you toward affordable legal advice. A legitimate cash buyer will never ask you for money, will explain how they reached their number, and will have no problem with your attorney reviewing the contract.

    A Practical Two-Week Plan

    • Open every envelope from your servicer and put them in date order. Look for the loss mitigation notice and any breach or demand letter.
    • Call the loss mitigation department directly — not general customer service — and ask for the reinstatement amount and a written payoff statement.
    • Ask which programs your specific loan type qualifies for, and request the application package.
    • Contact a HUD-approved housing counselor. It costs nothing and they know which arguments work with which servicers.
    • Run your equity math using the payoff figure, and check the tax status on every parcel you own.
    • Decide honestly whether the payment is affordable again within 90 days. If yes, pursue a modification or repayment plan. If no, start the sale conversation now, while you still have runway and clean title.

    Frequently Asked Questions

    Can my lender foreclose at 60 days late in Georgia?

    Generally no. For most residential mortgages, federal rules bar the first foreclosure filing or notice until you are more than 120 days delinquent. At two months you are in pre-foreclosure, still holding title and still controlling the outcome.

    Will two missed payments show up on my credit report?

    Yes. Both the 30-day and 60-day delinquencies are reportable, and a 60-day mortgage late is a serious derogatory mark that can remain for up to seven years. Bringing the loan current stops further damage but does not erase what is already reported.

    Should I call my lender, or wait for them to call me?

    Call them. Homeowners who initiate contact get a wider set of options and are treated as workout candidates rather than collection files. There is no advantage to waiting.

    Can I sell my house while I am behind on the mortgage?

    Yes. You remain the legal owner until a foreclosure sale is completed, and the payoff is handled at closing out of the sale proceeds. Our guide on selling a house in foreclosure covers how title companies handle liens and payoffs.

    What if the property was inherited and I am behind on the note?

    More common than people assume, especially when an estate was never properly probated. The estate generally needs legal authority to sell before closing. See selling inherited property, our overview of probate real estate in Georgia, and how we work with out-of-state owners.

    The Bottom Line

    Two months behind is a bad month, not a verdict. You are in the widest part of the funnel: title is clean, foreclosure has not started, and every workout option still exists. Four months from now, most of them will not.

    The homeowners who come through this with their credit and equity intact are rarely the ones with the biggest savings. They are the ones who opened the mail and did the math while they still had time — before the embarrassment convinced them that not knowing was easier than knowing.

    If selling is on the table — a house that needs work, a rental you are tired of carrying, an inherited parcel with taxes attached, or land you no longer want — we buy property across metro Atlanta as-is, with no fees or commissions, and most closings run 7 to 14 days. Call (404) 913-7086, request a no-obligation cash offer, or contact us about your situation. We will give you a straight answer either way — including when the answer is that you should go talk to your servicer instead.

    Related: about our team · tax-delinquent property · Fulton County · DeKalb County · vacant land

    Atlanta, Georgia, 30307

    Ready To Sell Your Land? Start Here…

    We are direct land buyers. There are no commissions or fees and no obligation whatsoever. Start below by sharing where your property is and where we can send your offer…

    "*" indicates required fields

    Name*
    This field is for validation purposes and should be left unchanged.

  • City of Decatur Property Taxes vs. DeKalb County: Two Bills, Four Deadlines

    A practical guide for Decatur, Georgia property owners on installment billing, assessment ratios, millage rates, and how a single parcel can be current with one taxing authority and delinquent with the other.

    Most Georgia property owners deal with one property tax bill a year, from one office, with one due date. If you own property inside the City of Decatur, you deal with two separate taxing authorities, two separate billing cycles, and four payment deadlines spread across seven months of the calendar.

    This is not a quirk of paperwork. Decatur operates its own tax collection function alongside DeKalb County, bills on a schedule that does not overlap with the county at any point, and calculates your taxable value using a different assessment ratio than the county uses. The result is a structure almost nobody explains to buyers at closing, and one that quietly produces tax liens on properties whose owners genuinely believed they were paid up.

    Here is how the two systems actually interact, and where owners get caught.

    Why a Decatur Property Gets Two Tax Bills

    Decatur sits inside DeKalb County, so the county levies its own ad valorem taxes on the parcel the way it does anywhere else in DeKalb. That is bill number one, issued by the DeKalb County Tax Commissioner.

    Bill number two comes from the City of Decatur, and it carries something most municipal bills do not: a full school system. City Schools of Decatur is an independent school district, separate from the DeKalb County School District. Because Decatur residents sit outside the county school system, the school millage that would normally ride on a county bill instead rides on the city bill. That single fact is why the Decatur bill is so large relative to a typical city tax bill, and why owners who assume the county bill is “the real one” are badly mistaken about the proportions.

    By the city’s own breakdown, schools account for roughly 61 cents of every dollar collected on the Decatur bill. The general fund takes about 27 cents. Everything else, including capital improvements, bonds, solid waste, stormwater, and the Downtown Development Authority, splits the remainder.

    The Four Deadlines, in Calendar Order

    The City of Decatur bills in two unequal installments. DeKalb County also bills in two installments, but from a single mailing in August. Neither schedule aligns with the other, and no deadline is shared.

    BillAuthorityTypically mailedDue date
    1st installmentCity of DecaturBy April 1June 1
    1st installmentDeKalb CountyAugustSeptember 30
    2nd installmentDeKalb CountyAugust (same mailing)November 15
    2nd installmentCity of DecaturOctober 20December 20

    Watch the weekend rule. Both authorities roll a deadline that lands on a weekend or holiday to the next business day, and both do it independently. For the 2026 cycle, DeKalb’s second installment moved to November 16 because November 15 fell on a Sunday, and Decatur’s billing ordinance set the second installment at December 21 for the same reason. If you calendar the statutory dates rather than the dates printed on this year’s bill, you will eventually be a day off on a payment that carries a five percent penalty.

    The Assessment Ratio Difference Almost Nobody Catches

    This is the single most misunderstood point in Decatur property taxation, and it is worth reading twice.

    Both bills start from the same appraised fair market value. The DeKalb County Board of Tax Assessors appraises every parcel in the county, including every parcel inside Decatur. The city does not run its own appraisal operation; it takes the county’s valuation.

    But the two authorities then apply different assessment ratios to that value. DeKalb County uses the standard Georgia ratio of 40 percent of fair market value for its own bills. The City of Decatur uses 50 percent.

    On a home appraised at $400,000, the county calculates against an assessed value of $160,000 while the city calculates against $200,000. Same house, same appraisal, two different taxable bases.

    The practical consequence is that you cannot compare the two millage rates directly. Stacking a city millage against a county millage and concluding one is higher is an apples-to-oranges comparison, because the denominators differ by 25 percent. Anyone budgeting a purchase, underwriting a rental, or arguing a valuation needs to run each bill on its own base. Our broader comparison of Fulton County vs. DeKalb County property taxes covers how the standard 40 percent ratio works across metro Atlanta, which makes Decatur’s 50 percent the exception rather than the rule.

    City of Decatur millage rates for 2026

    Fund (City of Decatur, 2026)Millage rate
    General Fund8.75
    Capital Fund2.10
    Bond Fund0.59
    School Bond1.18
    DDA Fund0.35
    School Fund (City Schools of Decatur)20.30
    Total city millage33.27

    Why the Second Decatur Bill Never Matches the First

    The word “unequal” in Decatur’s installment structure is doing real work.

    The first installment, mailed by April 1 and due June 1, is an estimate. The city calculates it by multiplying the assessed value by the combined city and school millage rate and dividing by two. At that point the current year’s tax digest is not final, so the city is working from the prior year’s value and last year’s millage.

    The second installment, mailed October 20 and due December 20, is a restatement of the entire year. It uses the current year’s DeKalb tax digest as approved by the state, applies the final millage rates, applies any homestead exemption changes, and then credits whatever you paid in June. Because the assessed value, the millage, and the exemptions can all move between April and October, the second bill routinely differs from the first by a wide margin.

    Owners who set up automatic payments for “half the tax bill” twice a year, or who budget the December payment by doubling the June one, are the ones who get surprised. Treat the June figure as a deposit, not as half the year.

    Fees That Only Appear on One Bill

    Sanitation and stormwater are billed annually by the City of Decatur and are normally payable in full on the first installment. They appear again as line items on the second installment bill, but only as a restatement of what you already paid, not as a second charge. Owners reading the December statement in isolation frequently think they are being double-billed for trash pickup.

    DeKalb County has its own separate residential sanitation assessment on the county bill for parcels it services. Which fees land on which bill depends on the service arrangement for your address, so read the line items rather than assuming.

    For vacant lots, this matters in a specific way: stormwater fees are assessed on paved and covered area and are charged to all property owners, including owners of tax-exempt property. An unimproved parcel producing no income can still generate a recurring utility fee alongside an ad valorem bill from each authority. This is a common reason vacant land in metro Atlanta quietly accumulates a balance the owner never budgeted for.

    Current With One Authority, Delinquent With the Other

    This is the failure mode the two-bill structure produces, and it is more common than it should be.

    The two authorities do not share a ledger. Paying DeKalb County does nothing for your City of Decatur account, and paying the city does nothing for the county. Each can assess its own five percent late penalty. Each accrues interest on its own schedule, at the state formula of the bank prime rate plus three percent, which works out to 9.75 percent annually, or 0.8125 percent per month, for 2026. Each can issue its own Fi.Fa., the tax execution recorded against the property that functions as a lien and is the first step toward a tax sale.

    So a parcel can show a clean payment history at DeKalb County Public Access while a separate city execution sits recorded against the same property. Owners who check one portal, see a zero balance, and stop looking are the ones who find out at closing, or when the notice arrives.

    Two habits prevent it. First, check both portals every year, not one. The city maintains its own lookup at decaturgatax.com with seven years of history. Second, search the GSCCCA statewide lien index for recorded executions against the parcel, which will surface a lien from either authority regardless of which portal you normally use.

    If a balance has already gone unpaid long enough to be advertised, read our guides on what happens when you don’t pay property taxes, the Georgia tax foreclosure process, and the 12-month redemption period that follows a tax sale.

    The Escrow Trap

    Both the City of Decatur and DeKalb County state plainly that they do not mail tax bills to mortgage companies. Your servicer has to request the information, or use a third-party tax service to pull it. And critically, both authorities put the obligation back on the owner: failure to receive a bill does not relieve you of the responsibility to pay it.

    A servicer set up to pay a DeKalb County bill on a September and November cycle may have no record of a City of Decatur account on an April and October cycle. This is the classic failure after a refinance or a servicing transfer, where the new servicer inherits the county obligation and never learns the city one exists. The owner sees escrow disbursements, assumes full coverage, and does not discover the gap until a city execution is recorded.

    If you escrow, confirm with your servicer in writing that they are paying both accounts, and confirm it again after any refinance or transfer.

    Appeals: One Board, Two Bills

    Because DeKalb appraises the property, an appeal of your value goes to the DeKalb County Board of Tax Assessors, not to the city. Georgia gives you 45 days from the date on your annual notice of assessment to file.

    The outcome flows to both bills, but not on the same timeline. While an appeal is pending, both authorities bill at a temporary value. DeKalb’s default is the lesser of your last final value or 85 percent of the current year value, with alternative elections available, including a 100 percent election and a separate option for non-homesteaded property valued over $2 million. Decatur bills under appeal at a temporary value that is often 85 percent of the proposed assessed value.

    The point owners miss: you still owe the full amount shown on each bill by each deadline while the appeal is pending. An appeal does not pause a due date on either bill. When the appeal resolves, you receive either a supplemental bill or a refund, from each authority separately. DeKalb applies interest to appeal differences settled after November 15.

    Address Changes Require Two Steps

    This is a small procedural detail with outsized consequences, especially for out-of-state owners and for heirs administering an estate.

    A mailing address change must be submitted in writing to the DeKalb County Board of Tax Assessors. Once DeKalb has updated its record, you then have to separately notify the City of Decatur through its finance office or its tax portal. Completing only the first step means the county bill follows you and the city bill continues going to an address you no longer control.

    For inherited property, this is how a parcel goes delinquent for years without anyone realizing. Bills route to a deceased owner’s address, nothing bounces back to the heirs, and interest compounds on two accounts at once. If you are working through an estate, see our guidance on selling inherited land and what happens when you inherit land in Georgia.

    One Naming Trap Worth Knowing

    Searching for “Decatur property tax deadlines” will surface results for Decatur County, a separate Georgia county seated in Bainbridge, roughly 240 miles southwest, whose taxes are due December 20 in a single annual payment. It has no relationship to the City of Decatur in DeKalb County.

    Confusing the two produces a plausible-looking but wrong calendar: one deadline instead of four. Verify you are on a decaturga.com or dekalbtaxga.gov page before you write a date down.

    If You Are Already Behind on One or Both

    Penalties and interest on two accounts compound faster than most owners expect, and the gap between “manageable” and “advertised for sale” closes quietly. A few practical steps:

    • Get an exact payoff figure from each authority separately. DeKalb: 404-298-4000. City of Decatur Finance: 678-553-6743. A balance from one is not a balance for the parcel.
    • Ask each about partial payments. DeKalb accepts them, though partial payment does not by itself stop a parcel from progressing toward levy.
    • Confirm whether a Fi.Fa. has been recorded, and by which authority. Check the DeKalb delinquent tax page and the GSCCCA index.
    • If the property has already sold at tax sale, the 12-month redemption clock is running and the cost to recover rises with time.
    • If keeping the property is no longer the goal, a direct sale settles both balances at closing out of proceeds rather than out of pocket. See selling tax-delinquent land in Atlanta.

    Frequently Asked Questions

    Does paying DeKalb County cover my City of Decatur taxes?

    No. They are entirely separate accounts with separate ledgers, separate deadlines, and separate enforcement. A zero balance with the county tells you nothing about your city account, and vice versa.

    When exactly are City of Decatur property taxes due?

    In two unequal installments: June 1 and December 20. The first installment is mailed by April 1, the second on October 20. If a due date falls on a weekend, it moves to the next business day, which is why the 2026 second installment was set at December 21.

    When are DeKalb County property taxes due?

    September 30 and November 15, from a single bill mailed in August. Paying in one lump sum means paying the full amount by September 30. In 2026 the second installment moved to November 16 because November 15 fell on a Sunday.

    Why is my City of Decatur bill larger than I expected?

    Two reasons. First, the city applies a 50 percent assessment ratio while the county applies 40 percent, so the city bill is calculated on a larger taxable base. Second, City Schools of Decatur is an independent district, so the school millage sits on the city bill rather than the county one. Schools alone represent about 61 cents of every dollar on the city bill.

    Do I appeal my value to the city or the county?

    To the DeKalb County Board of Tax Assessors. The city does not appraise property; it uses DeKalb’s valuation. You have 45 days from the date on your annual assessment notice to file, and a successful appeal affects both bills.

    Do I still have to pay while my appeal is pending?

    Yes, on both bills, by both sets of deadlines. Each authority bills at a temporary value, commonly around 85 percent, and issues a supplemental bill or a refund once the appeal resolves. An appeal does not extend a due date.

    Why does my second Decatur installment differ so much from the first?

    The first installment is an estimate calculated before the current year’s tax digest is final. The second restates the entire year using the final DeKalb digest, final millage rates, and current exemptions, then credits your June payment. The two are not designed to match.

    My mortgage company escrows my taxes. Am I covered?

    Not necessarily. Neither the city nor the county mails bills to mortgage companies, and both state that failure to receive a bill does not relieve you of the obligation. Servicers sometimes track the county account and miss the city account entirely, particularly after a refinance or a servicing transfer. Confirm in writing that both are being paid.

    Can I lose the property over unpaid city taxes alone?

    Yes. The City of Decatur can record its own tax execution and pursue collection independently of the county. A parcel fully current with DeKalb can still carry a city lien and move toward a sale.

    I changed my mailing address with the county. Is that enough?

    No. Address changes go to the DeKalb County Board of Tax Assessors first, then must be submitted separately to the City of Decatur. Doing only the county step means your city bills keep going to the old address.

    Do vacant lots in Decatur get both bills?

    Yes. Unimproved parcels are assessed and billed by both authorities, and vacant land does not qualify for homestead exemption. Stormwater fees are charged based on paved and covered area to all property owners, including tax-exempt ones.

    Is this the same as Decatur County, Georgia?

    No. Decatur County is a separate county seated in Bainbridge in southwest Georgia, with a single December 20 deadline. The City of Decatur is the DeKalb County seat in metro Atlanta. The two are frequently confused in search results.

    Will you buy a Decatur property that is behind on both bills?

    Often, yes. We regularly purchase parcels carrying balances with more than one taxing authority, including recorded executions, and both balances can be settled from proceeds at closing.

    Official Resources

    Dealing With a Balance on Either Bill?

    A Decatur parcel behind with one authority is usually behind with both, because whatever caused the miss, a bad address, a servicing transfer, an unprobated estate, applies equally to two accounts on two schedules.

    Atlanta Land Buyers purchases property throughout DeKalb County as-is, including parcels carrying tax executions from a city, a county, or both. We research the tax status with each authority before making an offer rather than discovering a second lien midway through closing, and both balances are settled from proceeds at closing. Most closings run 7 to 14 days.

    Call or text (404) 913-7086, or request a no-obligation cash offer.

    Related reading: Sell land in DeKalb County · Tax-delinquent land · Vacant land · Inherited land · Georgia land buyers · Contact us

    Decatur, GA, USA

    Ready To Sell Your Land? Start Here…

    We are direct land buyers. There are no commissions or fees and no obligation whatsoever. Start below by sharing where your property is and where we can send your offer…

    "*" indicates required fields

    Name*
    This field is for validation purposes and should be left unchanged.

  • Can I Sell Property With a Lien on It in Georgia?

    fulton county property

    If a creditor, county, contractor, or homeowners association has attached a claim to your land, the question is a practical one: can I sell property with a lien on it, or are you stuck until the debt is gone? In most situations a sale is still possible. Liens are common, and closings involving them happen every week across Georgia’s 159 counties. What changes is the paperwork, the timeline, and how money is distributed at the closing table.

    This article covers the lien types most common on Georgia parcels, what a title search looks for, how payoffs are handled at closing, and what happens when claims exceed the land’s value. It is general information, not legal advice.

    The Short Answer

    Yes — in most cases you can sell property with a lien on it in Georgia. What you generally cannot do is convey clear, insurable title while a valid lien remains outstanding. The usual solution is not to clear the lien before you list, but to resolve it during closing, out of the sale proceeds.

    That distinction matters. Sellers often assume they must pay off a judgment or years of back taxes out of pocket first. Frequently they do not. A properly structured closing may pay each lienholder directly from the proceeds, with the release recorded afterward.

    Still, may is the operative word. The amount, priority, and payoff requirements have to be confirmed in writing first. A balance that reads $4,000 on a county website can settle at a very different number once interest, penalties, and fees are added. For the process itself, see how our land buying process works

    What a Lien Actually Does to Georgia Land

    A lien is a recorded claim against the property, not only against you personally. It travels with the dirt, which is why a buyer’s lender and title insurer care about it even when the underlying debt has nothing to do with them. Most Georgia liens are recorded with the Clerk of Superior Court in the county where the land sits, and many are searchable through the statewide GSCCCA index.

    Recording puts the world on notice, and it is what makes a claim surface when someone runs title.

    Liens also have priority, generally tied to recording date, though some claims jump the line by statute. Priority decides who is paid first when proceeds are limited, and tax claims typically sit at or near the top. That ordering matters on a parcel worth less than the total owed against it.

    The Lien Types Most Common on Georgia Property

    1. Property Tax Liens

    Georgia property taxes are assessed on ownership as of January 1 each year. When a bill goes unpaid, the county tax commissioner may issue a writ of fieri facias — a “fi. fa.” — and record it on the General Execution Docket. Penalties and interest keep accruing, and once a fi. fa. is issued the parcel can be levied on and sold at a county tax sale.

    If a tax sale has already happened, you are on a different clock. After a non-judicial tax sale, the owner or anyone holding an interest in or lien on the property generally has 12 months to redeem by paying the bid amount, taxes the purchaser paid afterward, special assessments, and a 20 percent premium for the first year, plus 10 percent for each year after (O.C.G.A. §§ 48-4-40, 48-4-42). Past that window, the purchaser may move to foreclose, or “bar,” the right of redemption. Any notice referencing redemption or barment is time-sensitive.

    Where no tax sale has occurred, back taxes are often among the easier items to clear at closing, since the tax commissioner’s office can usually issue a payoff good through a stated date. More here: selling land with back taxes in Georgia

    2. Judgment Liens

    A creditor who wins a money judgment can obtain a writ of fieri facias and record it on the General Execution Docket in any county where you own real property. Once recorded, it attaches to your property there and appears in a title search.

    A Georgia judgment generally becomes dormant seven years after it is rendered unless the creditor takes steps to keep it alive, with a limited window afterward for revival (O.C.G.A. §§ 9-12-60, 9-12-81). A judgment that looks dormant does not leave the record on its own, though — a written cancellation is usually still needed before a title company will insure around it.

    Because these liens attach through the owner, a judgment against a co-owner, a former spouse, or a deceased prior owner can encumber the parcel too. Payoffs are sometimes negotiable, but any reduced-payoff terms should be documented by an attorney before closing is scheduled.

    3. HOA and POA Liens

    For communities under the Georgia Property Owners’ Association Act (O.C.G.A. § 44-3-220 et seq.) or the Condominium Act, the lien for unpaid assessments generally arises automatically once payment is past due. The recorded declaration itself provides record notice, so a separate claim of lien often does not have to be filed.

    That is why these get missed. A docket search may show nothing while a valid, growing claim sits behind it — most often on vacant lots in platted subdivisions, where owners stop thinking about dues on land they never built on. Depending on the governing instrument, the balance can include late charges, interest, collection costs, and attorney’s fees actually incurred.

    Georgia law lets an owner, a purchaser under contract, or a lender request a written statement of amounts due from the association, and that statement carries legal weight. Closing attorneys routinely request one. Not every Georgia association is governed by the POA Act, though — some enforce dues through covenants instead, which changes the analysis.

    4. Mechanic’s and Materialman’s Liens

    Contractors, subcontractors, and suppliers who improved the property and were not paid may file a claim of lien under O.C.G.A. § 44-14-361.1. The deadlines are strict and courts read them closely. In general terms: file within 90 days of last furnishing labor or materials, send the owner a copy within two business days, commence an action to enforce within 365 days of filing, and file notice of that action with the superior court clerk within 30 days of filing suit. An owner or contractor may also record a Notice of Contest of Lien, shortening the window to commence an action to 60 days.

    Because these liens expire when a deadline is missed, some recorded claims are no longer enforceable — yet they cloud title until cancelled of record. Whether a claim is stale, valid, or defective is a legal question, not a clerical one.

    5. Estate-Related Claims

    Inherited land raises a different category of issue. Several of these are not liens in the strict sense, but they affect whether the property can be conveyed and who must sign:

    • Probate status — whether an executor or administrator has been appointed, and whether the will grants a power of sale
    • Multiple heirs holding undivided interests, each of whom may need to sign the deed
    • Year’s support petitions, which can change how title passes
    • Debts and claims against the estate, including medical bills and any Medicaid estate recovery claim
    • Judgments recorded against the deceased owner before death
    • Property taxes and HOA assessments that accrued during a long vacancy, and prior deeds with errors or unclear legal descriptions

    Heir property is one of the more common reasons a Georgia land sale stalls. It is usually solvable, but it needs to be identified early rather than three days before closing. If that is your situation, start here: selling inherited land in Georgia

    Why a Title Company Searches for Liens

    A buyer wants marketable title, and a title insurer will not issue a policy without knowing what is recorded against the parcel. Depending on the transaction, the search covers deeds and security deeds, the General Execution Docket where fi. fa.s and judgments sit, tax records, lis pendens filings, plats, easements and covenants, and probate records when an estate is involved.

    It protects the seller too. Searches regularly surface things the owner never knew about: a judgment against someone with a similar name, a security deed paid off but never cancelled, an easement across the buildable area, or a lien satisfied years ago and never released. Better to find those early than against a contract deadline.

    Georgia closings are conducted under the supervision of a licensed Georgia attorney. That attorney, with the title company, is who confirms lien amounts, evaluates priority, obtains payoff requirements, and disburses funds. Their written figures govern — not a balance printed from a county portal, and not what a lienholder said over the phone.

    How Liens Are Paid at Closing

    In a typical Georgia transaction involving one or more liens, the sequence looks something like this:

    1. The title search identifies recorded claims against the parcel and against owners in the chain of title.
    2. The closing attorney requests written payoffs or association statements from each lienholder, good through a specific date.
    3. Those confirmed amounts appear as seller debits on the settlement statement, so the math is visible before signing.
    4. At closing, the buyer’s funds go into the closing attorney’s escrow account.
    5. The attorney disburses to each lienholder, then releases remaining proceeds to the seller.
    6. Each lienholder executes a release or cancellation, recorded with the clerk. That can take days to several weeks.

    Two practical notes. Payoff figures expire, and per diem interest may apply if closing slips past the good-through date. And some claims cannot be resolved by payment alone — a disputed lien, pending litigation, a defective legal description, or a missing heir signature may require a consent, court order, corrective deed, or quiet title action.

    The accurate framing is this: a sale may resolve a lien at closing, but only after title professionals confirm the amount, the priority, and the payoff requirements for that specific claim.

    What Happens If the Liens Exceed the Land’s Value

    This is the harder scenario, and on rural acreage, landlocked parcels, and long-neglected lots it is not rare. When recorded claims exceed what the property will bring, several paths are commonly explored:

    • Negotiated reductions. Junior lienholders sometimes accept less than face value, since foreclosing on a low-value parcel may return them nothing. Any reduction must be in writing, with release terms agreed before closing.
    • Seller contribution. Bringing funds to cover the shortfall, sometimes cheaper than continuing to carry the property.
    • Priority analysis. Junior claims fare differently than senior ones in a tax sale or foreclosure, which changes the leverage in a negotiation. This needs legal review, not guesswork.
    • Partial releases. Where a claim covers several parcels, a lienholder may release just one. Deed alternatives or walking away are occasionally appropriate, and occasionally a costly mistake.
    • Doing nothing. Rarely neutral — taxes, interest, and assessments keep accruing and tax sale risk grows.

    When Legal Advice Is Necessary

    Much of this is routine for a closing attorney. Some of it is not. Talk to a Georgia real estate attorney before signing anything if:

    • The parcel has already been sold at a tax sale, or you received a notice about redemption or foreclosure of the right of redemption
    • You dispute the validity or the amount of a recorded lien
    • The owner of record is deceased and the estate was never probated, heirs disagree, or a co-owner will not cooperate
    • Recorded claims approach or exceed what the land is worth, or bankruptcy has been filed or is being considered
    • A creditor has offered a settlement and you need the release terms drafted correctly
    • A lien references a name similar to yours, or the legal description appears wrong

    Even a cooperative lienholder has to sign the right document. A verbal agreement to release a lien is not a release, and a cancelled check is not a cancellation of record.

    Common Questions

    Can I list the property before the lien is resolved? Generally yes. Liens are usually addressed during closing rather than beforehand, though disclosure is expected.

    Will the buyer find out? Yes. Recorded claims appear on the title commitment, so raising them up front goes better than letting them surface mid-transaction.

    Do I need to pay the lien out of pocket first? Often no, provided proceeds are sufficient and the lienholder will release upon payment at closing.

    How long does it take? A straightforward tax payoff moves quickly. Probate, disputed liens, or missing heirs can add weeks or months. Selling for cash removes lender and appraisal timing, but liens are still confirmed, paid, and released the same way.

    The Next Step

    Every parcel is different. The only way to answer this question for yours is to look at what is actually recorded against it, and that starts with two things.

    Send the parcel number and any lien notice you received. From there we can review what is on record and tell you plainly what it would likely take to resolve, and whether a sale makes sense. No cost, no obligation. Contact us here

    Atlanta, Georgia, 30307
  • How To Sell Inherited Land for Cash in Atlanta

    Step-by-step guide to sell inherited land for cash in Atlanta in 2026 — probate authority, back taxes, and a 7-14 day cash close explained.

    georgia land for sale

    Selling inherited land in Atlanta means dealing with probate paperwork, unpaid property taxes, and sometimes co-heirs who disagree — and most people don’t want to spend six figures fixing up a vacant lot they never asked for. This guide walks through the exact steps to sell inherited land for cash in Atlanta in 2026, from confirming legal authority to closing.

    • Confirm executor or heir authority before you sign anything — this is the step that kills most deals late.
    • A cash sale to a company like Atlanta Land Buyers closes in 7-14 days versus 6-12 months on the open market.
    • Back taxes and liens get deducted at closing, not out of your pocket upfront.
    • Georgia’s stepped-up basis rule usually limits capital gains tax on inherited land sold near its date-of-death value.

    Why this matters

    Inherited land sits differently than a house you inherit. There’s no agent lined up to list a vacant lot, no MLS traffic, and often no clear picture of what’s owed on it. Fulton County alone carries thousands of tax-delinquent parcels, and a share of those are heirs who never resolved the estate before taxes stacked up.

    The slower you move, the more penalties accrue and the more heirs can complicate a sale. Selling inherited land for cash in Atlanta bypasses the listing-repair-showing cycle entirely — Atlanta Land Buyers and similar direct buyers purchase the parcel as-is, liens and all, and handle the paperwork that would otherwise sit with a real estate attorney for months.

    What you’ll need

    • Certified copy of the death certificate — required by the title company to confirm the estate
    • Letters Testamentary or Letters of Administration from Fulton County Probate Court, proving you have authority to sell
    • The deed (or a copy pulled from the Fulton County Clerk of Superior Court if you don’t have the original)
    • The parcel’s tax ID / PIN from the county tax assessor’s site
    • A list of any known liens, mortgages, or unpaid tax bills on the parcel
    • Contact info for any co-heirs who share ownership
    • 30-60 minutes to gather documents; the sale itself takes 7-14 days once you have an offer

    The steps

    You can’t sell what you don’t legally control yet. If the estate hasn’t cleared probate, you need Letters Testamentary (if there’s a will) or Letters of Administration (if there isn’t) from Fulton County Probate Court before any sale closes.

    Common mistake: heirs assume being named in a will is enough. It isn’t — the court has to formally appoint you, and a buyer’s title company will require that document before funding.

    2. Pull the parcel’s tax and title history

    Search the parcel identification number on the Fulton County Board of Assessors site to confirm the assessed value, and check the Tax Commissioner’s office for any delinquent balance. Inherited land frequently carries 2-3 years of unpaid taxes because nobody knew they were responsible for the bill.

    This step tells you whether the land is heading toward a tax sale — Georgia counties can auction tax-delinquent parcels, and once that clock starts, your negotiating position weakens fast.

    3. Decide between listing and a direct cash sale

    A traditional listing means finding an agent willing to market raw land (many won’t), waiting for a buyer who can get land financing (harder than home financing), and often waiting 6-12 months. A direct cash buyer skips financing contingencies entirely because they’re not borrowing to close.

    For land with back taxes, boundary questions, or multiple heirs, a cash sale usually closes faster because the buyer absorbs the cleanup work instead of asking you to fix it first.

    4. Get a written cash offer

    Request an offer based on the parcel’s tax ID, acreage, and location rather than a drive-by guess. A legitimate offer should account for any liens or back taxes owed — those get deducted from your proceeds at closing rather than billed to you separately.

    Common mistake: accepting a verbal number over the phone. Get the offer in writing with the deduction breakdown shown line by line.

    5. Review the purchase agreement

    Check that the agreement names every heir with an ownership interest — if one heir signs and others don’t, the title company will flag it and the closing stalls. Confirm the closing date, the earnest money terms if any, and who’s paying closing costs.

    6. Clear title through a licensed closing attorney

    Georgia land sales close through an attorney, not just a title company alone. The attorney runs a title search, resolves any judgment liens or old easements, and confirms the deed transfers clean. This is also where back taxes get paid off directly from sale proceeds.

    7. Sign and close

    Most direct cash sales in the Atlanta market close in 7-14 days once title is clear and all heirs have signed. You’ll sign the deed, the attorney disburses funds (often by wire the same day), and the county records the new deed.

    Common mistake: underestimating how long multi-heir signatures take if someone lives out of state — build in extra days for mailed or notarized remote signatures.

    8. Handle the tax reporting

    Inherited property usually gets a stepped-up basis to fair market value at the date of death, which means your capital gains exposure is often small if you sell close to that value. Talk to a CPA before filing — this guide isn’t tax advice, and every estate’s basis calculation differs.

    Get a cash offer on inherited land

    Atlanta Land Buyers closes in 7-14 days, no agents or repairs required.

    Request an offer

    Troubleshooting

    • Multiple heirs disagree on selling — a buyout among heirs or a partition action in Fulton County Superior Court resolves it, but a partition suit can take a year or more. Try a written agreement among heirs first.
    • Property is still in probate — the sale can’t close until Letters Testamentary or Administration are issued. Ask the probate attorney for an expected timeline; Fulton County probate typically moves faster for smaller estates without disputes.
    • Land has back taxes near a tax sale date — move fast. Once Fulton County schedules a tax sale, you lose control of the timeline and the parcel can be sold at auction for the tax debt alone.
    • Deed has an old lien or judgment attached — a title search during step 6 catches this. The closing attorney negotiates payoff from proceeds; it rarely kills the deal, just adds a few days.
    • Parcel is landlocked or has no recorded access easement — this lowers value but doesn’t block a sale. Cash buyers who purchase raw land regularly account for access issues in the offer.
    • Out-of-state heir can’t attend closing — remote online notarization or a mailed, notarized deed handles this in Georgia without delaying the close by more than a few days.

    Tools and resources

    • Fulton County Board of Assessors — parcel value and tax ID lookup
    • Fulton County Probate Court — Letters Testamentary / Administration filings
    • Fulton County Clerk of Superior Court — deed and lien history
    • A Georgia-licensed real estate closing attorney — required for the deed transfer
    • Atlanta Land Buyers — direct cash offers on vacant lots, acreage, and inherited parcels in Fulton County

    What to do next

    Once you’ve confirmed your legal authority and pulled the tax history, the fastest next move is getting a written cash number to compare against a listing estimate. Run both numbers side by side, factor in the 6-12 month listing timeline against a 7-14 day cash close, and decide based on what the estate actually needs — speed, certainty, or maximum price over time.

    FAQ

    Can I sell inherited land before probate closes in Georgia?

    No, you need Letters Testamentary or Letters of Administration from the probate court before you can legally transfer the deed. A closing attorney or title company will require this document before funding any sale.

    Do I have to pay off back taxes before selling inherited land?

    No — back taxes and liens are usually deducted from your proceeds at closing rather than paid out of pocket beforehand. Get the deduction breakdown in writing before you sign.

    What if multiple heirs inherited the same parcel?

    Every heir with an ownership interest must sign the purchase agreement, or the title company will flag the deal. A written buyout agreement among heirs resolves most disputes faster than a court partition action.

    Is selling inherited land for cash taxable?

    Inherited land usually gets a stepped-up basis to its fair market value at the date of death, which limits capital gains if you sell close to that value. Confirm the exact basis with a CPA before filing.

    What happens if the land has an unrecorded access easement?

    A landlocked parcel or one without a recorded easement still sells, but it usually lowers the offer. Cash buyers who purchase raw land regularly factor access issues into the price rather than rejecting the parcel.

    Do I need a real estate agent to sell inherited land in Atlanta?

    No. Many agents avoid raw land listings because financing and buyer pools are thinner than for houses, and a direct cash sale skips the agent commission and listing timeline entirely.

    What documents does a title company need for an inherited land sale?

    A certified death certificate, Letters Testamentary or Administration, the deed or a clerk’s office copy, and the parcel’s tax ID number. Missing any of these delays the closing date.

    One last thing

    The detail most heirs miss: Fulton County doesn’t wait patiently on unpaid taxes tied to an estate. Interest and penalties accrue from the original due date regardless of whether probate has closed, so the parcel you inherited debt-free on paper can carry a real balance by the time you’re ready to sell. Check the tax assessor’s site before you do anything else — it’s the fastest way to know whether you’re negotiating from strength or against a clock.

    Atlanta, Georgia, 30307

    Ready To Sell Your Land? Start Here…

    We are direct land buyers. There are no commissions or fees and no obligation whatsoever. Start below by sharing where your property is and where we can send your offer…

    "*" indicates required fields

    Name*
    This field is for validation purposes and should be left unchanged.

  • Do All Heirs Need to Agree to Sell an Inherited Property?

    Do All Heirs Need to Agree to Sell an Inherited Property

    Short answer: not always. Whether every heir has to sign depends on how the property is passing — and most families get this wrong in the same direction, assuming one holdout can freeze everything indefinitely.

    In Georgia, sometimes an executor or administrator can sell without unanimous heir consent. Sometimes every co-owner must sign. And when co-owners genuinely deadlock, Georgia law provides a path forward — one that, since 2012, has been unusually protective of families holding inherited land.

    This guide walks through which situation you are in, what your options are if one heir refuses, and the specific pressure Fulton County applies while you are figuring it out.

    First: How Is the Property Actually Passing?

    Everything follows from this. Four scenarios cover almost every Fulton County case.

    1. There is a will and an executor was appointed

    The executor generally signs, not the beneficiaries. Depending on the will’s terms and what the Probate Court has authorized, the executor may sell estate property directly through an Executor’s Deed — particularly when a sale is needed to pay estate debts, taxes, or expenses.

    Heirs do not all need to agree in this scenario. They have a right to be informed and to object through the court, but the executor holds the authority.

    2. No will, and an administrator was appointed

    Similar structure. The administrator, appointed by Fulton County Probate Court, holds authority over estate property and can sell subject to the court’s requirements. Again, unanimous heir consent is generally not the operative question — the administrator’s authority is.

    3. No Administration Necessary

    Georgia allows an estate to skip formal administration when there is no will, no estate debts, and all heirs agree on how to divide the property. It is faster and cheaper — but the unanimity requirement is built into the front door. If one heir will not sign the petition, this route closes.

    4. The property is already titled in the heirs’ names

    This is the most common situation with older Fulton County family land, and the one that generates this question. Probate happened years ago, or the property passed by operation of law, and the heirs now hold title directly as tenants in common.

    Here, yes — every co-owner must sign to convey the whole property. A title company will not close a full sale without all recorded owners on the deed.

    If you are unsure which scenario applies, start by pulling the deed. Our guide to running a Fulton County property tax search by owner name walks through the tools, and the GSCCCA index shows every recorded deed.

    What Tenants in Common Actually Means

    When heirs inherit together, they each hold an undivided fractional interest in the entire property — not a specific room, acre, or corner.

    Three siblings inheriting a house each own one-third of all of it. Nobody owns the back bedroom. Nobody owns the eastern half of the lot. That distinction matters more than families expect, because it means:

    • Any co-owner may use and occupy the property, regardless of share size
    • No co-owner can sell, mortgage, or lease the whole property alone
    • Each co-owner is generally responsible for their share of taxes and upkeep
    • Any co-owner may sell their own fractional interest without the others’ permission

    That last point is the one nobody mentions, and it changes the negotiating dynamic considerably. You cannot sell the house out from under your siblings — but you are not trapped either.

    What If One Heir Refuses to Sell?

    Options, roughly in order of cost and difficulty.

    Understand the objection first

    Refusals usually have a reason underneath. Someone lives there. Someone grew up there. Someone believes the offer is too low. Someone cannot afford to lose the address. Someone does not trust whoever is driving the sale.

    A sentimental objection and a financial one require completely different responses, and families often spend a year fighting the wrong one.

    Buy them out

    The cleanest resolution. One or more heirs purchase the reluctant party’s fractional interest at a fair price. Get an independent appraisal so the number is defensible, and close through a title company with a recorded deed — not a handshake.

    Sell your own interest

    You are entitled to sell your fractional share. In practice the buyer pool is narrow, and the price reflects that — a partial interest in a co-owned property is a difficult asset. But the option exists, and simply raising it sometimes moves a stalled conversation.

    Let them keep it, with terms

    If the holdout wants the property and the others want cash, that is a solvable trade. They refinance or borrow against it to buy the others out. This works when there is equity and the person has borrowing capacity.

    Partition action

    The legal remedy of last resort: a co-owner petitions Fulton County Superior Court to divide or sell the property. It works, but it is expensive, slow, publicly filed, and reliably damaging to family relationships. Treat it as the fallback, not the opening move.

    And in Georgia, partition does not work the way most people assume.

    Georgia’s Heirs Property Act Changes the Math

    This is the part almost no article on this topic covers, and it matters enormously for Fulton County families.

    In 2012, Georgia enacted the Uniform Partition of Heirs Property Act, codified at O.C.G.A. §§ 44-6-180 through 44-6-189.1. It was written specifically to stop a pattern that had stripped enormous wealth from families holding inherited land — an outside investor buying one heir’s small fractional interest, filing for partition, and forcing the whole property to a courthouse auction at a fraction of its value.

    Does your property qualify?

    Under § 44-6-180(5), property is “heirs property” if, on the date a partition action is filed, all of these are true:

    • There is no written agreement binding all cotenants that governs partition
    • One or more cotenants acquired title from a relative, living or deceased
    • And any one of: 20% or more of the interests are held by relatives; or 20% or more of the interests are held by someone who acquired title from a relative; or 20% or more of the cotenants are relatives

    Most Fulton County family land meets this easily.

    The protections

    • The court must determine whether it is heirs property first. This is mandatory — in Faison v. Faison, 344 Ga. App. 600 (2018), the Court of Appeals reversed a trial court for skipping the determination.
    • The court must order an independent appraisal of fair market value under § 44-6-184. Also mandatory — Morton v. Pitts, 357 Ga. App. 513 (2020), reversed a trial court for failing to order one. If all cotenants agree on a value, the court adopts theirs.
    • Cotenants get a buyout right. Under § 44-6-185, any cotenant who did not request partition by sale may buy out the interests of those who did, priced at the appraised value of the whole parcel multiplied by that person’s fractional share.
    • Dividing is preferred over selling. Section 44-6-186 directs the court toward partition in kind where practical.
    • If a sale is ordered, it defaults to the open market. Section 44-6-187 requires an open-market sale through a broker rather than a courthouse auction — which is precisely where value used to evaporate.
    • Notice must be posted on the property itself under § 44-6-182, so absent heirs have a real chance of learning about the action.

    In practical terms: one heir cannot easily force a fire-sale auction of Fulton County family land. The others get the first chance to buy at an appraised price, and if the property must be sold, it sells on the open market. That is a meaningfully stronger position than heirs in many states hold.

    The Clock Nobody Is Watching: Fulton County Taxes

    Here is what actually decides most of these disputes, and it is not the law.

    Property taxes do not pause while heirs argue. Fulton County bills the parcel whether or not the family has reached agreement, whether or not probate is open, and whether or not anyone is living there.

    • Owners outside the City of Atlanta face an October 15 deadline — not the December 20 date used in many Georgia counties.
    • Interest accrues monthly at the federal prime rate plus 3% — 9.75% annually for 2026.
    • A 5% penalty is added at 120 days past due, with another 5% every additional 120 days, capped at 20% of the original principal.
    • Vacant land gets no homestead exemption, and neither does a house nobody lives in as their primary residence.

    Once the balance goes unresolved long enough, the county records a Fi.Fa. against the title. Eventually the parcel is levied, advertised, and sold at a tax sale on the first Tuesday of the month.

    The bitter irony is that a family can spend two years litigating who controls a property and lose it to the county for a few thousand dollars in the meantime. This is a documented pattern across south Fulton, the West End, Southwest Atlanta, and around Cascade, where land bought by families in the 1960s and 70s has passed through two or three generations without formal probate.

    If taxes are already behind, deal with that before you settle the disagreement — the deadline is real in a way the family argument is not. See selling tax-delinquent property, how many years you can be behind before the county acts, and our guide to the Fulton County tax sale process.

    If the parcel has already been through a sale, you may still have rights — and possibly money owed. See what happens when a property is sold at auction and Fulton County excess funds.

    Practical Steps for Fulton County Families

    1. Pull the deed. Search the GSCCCA index and the Fulton County Board of Assessors record. Confirm exactly whose names are on title — not who the family believes owns it.
    2. Check the tax status. Call the Fulton County Tax Commissioner at 404-613-6100 and get a written payoff. Ask whether the parcel has been levied or scheduled.
    3. Determine whether probate was ever opened. Fulton County Probate Court sits at 136 Pryor Street SW in downtown Atlanta. If your parent died and nothing was filed, that likely needs to happen before a full sale.
    4. Identify every heir. Two or three generations in, the list is often longer than anyone realizes. Missing an heir will stop a closing cold.
    5. Search for other liens. Code enforcement, HOA assessments, judgments, and old mortgages all surface in the GSCCCA index and all have to be cleared.
    6. Get one honest valuation everyone can see. Most family disagreements about price are really disagreements about information.
    7. Talk to a Georgia attorney before filing anything. The Georgia Heirs Property Law Center works specifically on this issue, and Atlanta Legal Aid Society serves qualifying residents at no cost.

    Questions & Answers

    Can one heir stop the sale of an inherited house in Georgia?

    If the heirs hold title directly as tenants in common, yes — a full sale needs every recorded owner’s signature. But that heir cannot stop the others from selling their own fractional interests, and cannot prevent a partition action. If an executor or administrator holds authority through the estate, one heir’s objection generally does not block a sale at all.

    What percentage of heirs is needed to sell?

    For a conventional sale of the entire property held in tenancy in common, 100% of recorded owners must sign. There is no majority-rules threshold. Ownership percentages affect how proceeds are divided, not who has to sign.

    Can the executor sell without all heirs agreeing?

    Often, yes. An executor or administrator with authority from Fulton County Probate Court can generally sell estate property, particularly when a sale is needed to pay debts, taxes, or expenses. Heirs are entitled to notice and can object through the court, but their individual consent is usually not the controlling factor.

    What is a partition action and how long does it take?

    A lawsuit asking Superior Court to divide the property or order it sold. Timelines vary widely with complexity, number of parties, and how much is contested. Under Georgia’s Heirs Property Act, qualifying cases add mandatory steps — an heirs property determination, an appraisal, and buyout windows — which lengthen the process but generally produce better outcomes for the family than the old fast-auction route.

    Can I sell just my share of inherited property?

    Yes. A tenant in common may convey their fractional interest without the others’ consent. Realistically the market is thin and pricing reflects that, but it is a legitimate option — and mentioning it sometimes unlocks a stalled negotiation.

    What if we cannot locate one of the heirs?

    Common two or three generations in. A title company will typically require that missing heirs be identified and their interests resolved before closing. Options include a diligent search, court proceedings to address unknown heirs, or a partition action where notice requirements including on-property posting under § 44-6-182 apply. This is attorney territory.

    Who pays the property taxes while we are deciding?

    Co-owners are generally responsible proportionally, though in practice one person usually pays to protect the asset. Keep records — an heir who has carried taxes and upkeep may be entitled to credit for those contributions in a partition or buyout. And the county does not care about the arrangement; it only cares whether the bill is paid.

    Does an heir living in the house have to pay rent to the others?

    Generally a tenant in common may occupy the property without paying rent to co-owners, since each holds an undivided interest in the whole. It gets more complicated where an occupying co-owner has excluded the others. Fact-specific, and worth legal advice.

    What if the property has back taxes and we still cannot agree?

    Then the tax deadline decides for you, and nobody gets the outcome they wanted. Confirm the payoff, determine how much time actually remains, and treat that as the operative deadline rather than the family timeline. Selling before a tax sale nearly always leaves the family better off than redeeming afterward — redemption requires paying the buyer’s full bid plus roughly a 20% premium.

    Do we owe capital gains tax on an inherited property?

    Often far less than families expect, because inherited property generally receives a stepped-up basis to its value at the date of death. See capital gains tax on inherited property, and confirm with a CPA for your situation.

    The land has no road access. Does that change anything?

    Not the consent question, but very much the value and the buyer pool. Georgia provides several routes to legal access, including a statutory petition for a private way. See land locked property in Fulton County.

    Some heirs live out of state. Does that complicate a sale?

    Not much. Documents can be signed remotely with proper notarization, and closings routinely accommodate out-of-state parties. See how we work with out-of-state owners.

    Local Resources

    If the Deadlock Is Costing You More Than the Disagreement Is Worth

    Some family disputes are worth having. Others quietly cost more each month than anyone would have accepted at the start — in taxes, in maintenance, in the value of a house sitting empty, and in relationships that get harder to repair the longer it runs.

    If you own inherited property in Fulton County and the family cannot get to agreement, we will give you a straight read on where things stand — what the property is realistically worth, what the taxes are actually costing, and whether selling is even the right move.

    We buy vacant land and property throughout metro Atlanta as-is, including parcels with a recorded Fi.Fa., and we settle the tax balance directly at closing. Most closings run 7 to 14 days once everyone who needs to sign is ready.

    Call (404) 913-7086 or request a no-obligation offer.

    No fees, no commissions, no obligation. And if the answer is that your family should buy out one heir, open probate, or talk to the Georgia Heirs Property Law Center before doing anything else — we will say that instead. Contact us with questions about your specific situation, or learn about our team first.

    Related: probate real estate in Atlanta · what happens if you inherit land in Georgia · land buyers near me in Atlanta · Georgia land buyers

    Atlanta, Georgia, 30307